Good Debt vs bad Debt: What’s the Difference?
Debt is a Common part of modern life. People buy homne, buy vehicle, pay dor education and manage unexpected expenses.
Not all debt are same.
Borrowing may helps you build assest, improve your earning potential or achive important financial goals.
In this article, we’ll explain good vs bad debt in simple words, with rpactical tips and helps you to make better boroorwing decisions.
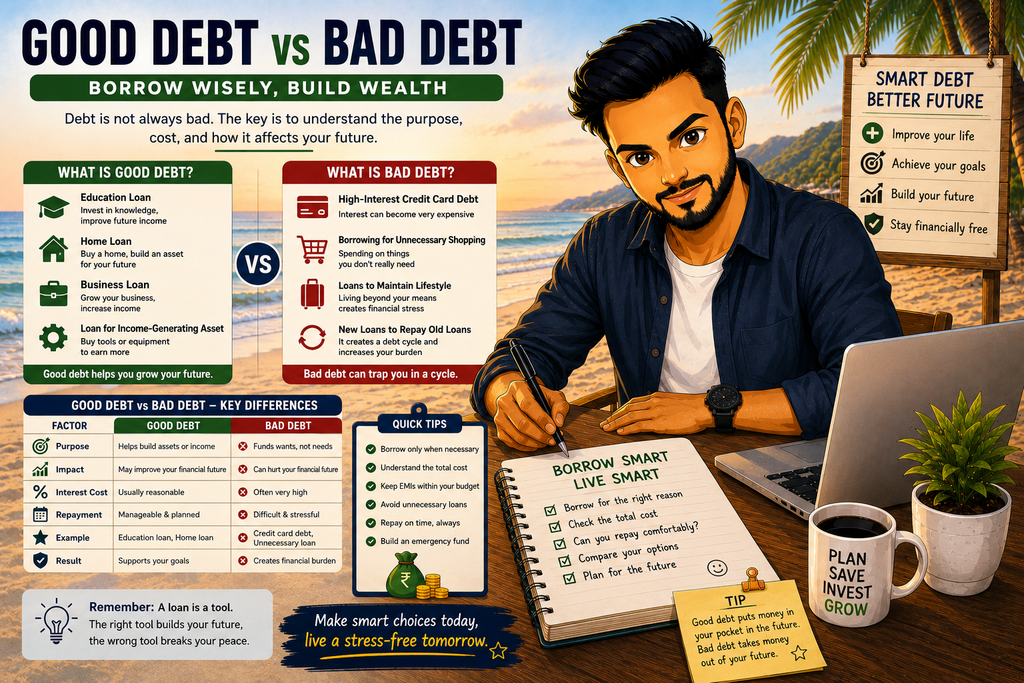
Table of Contents
What Is Good Debt?
Good Debt is borrowing that may help your improve your financial situation over time.
It’s main purpose to make manageble repayment and potential growth over time.
Exapmles of Good Debt
1. Education Loan
Borrowing for education may help you to skills or higher qualification that improves future earing.
the benefit depends on your course and ability to repay the loan.
2. Business Loan
A business loan may helps you to improve machaniery, equipment, expand or invest in business .
Borrowing should be planned with realistic for future genrating income and repayment the loan.
3. Home Loan:
A home loan may helps you to buy a property and grow asset over time.
But home comes with big borrowing cost, unaffordable EMis or buying big comes some sort of stress in life.
4. Loan for Income-generating Equipment
Borrowing money for improves gadget or equipment to genrate money may helpful when your expected income justify your the cost
Important:
Good Debt is not guaranted to make wealthy. it matter that repyment, cost and purpose.
What Is Bad Debt?
Bad Debt is borrowing that may xreate financial stress without fincial benefits.
It Provise like high cost interest rate, unimportant spending or unmanageable repayments.
Examples of Bad Debt
1. High-Interest Credit Cred Debt
Taking loan on high interest rate credit card it’s gives you unmanageable of interest and EMIs may be later you can not affordable.
2. Borrowing for Unnecessary Shopping
Taking a Loan or Usisng Cedit card to Buying things you do not need can reduce your future income potential.
3. Borrowing to Maintain a Lifestyle
SPending on vacation, expensive dinner out, and luxury purchases may create financial pressure if you don’t have prayment plan or stable income.
4. Taking a New Loan to Repay old Loans
Repeatedly borrowing to cover existing loan debt cane be dangerous cycle.
It may increase your stress and repayment burden. it make har to debt free for whole life.
Goood Debt vs Bad Debt:Key Differences
| Feature | Good Debt | Bad Debt |
| Main Purpose | May improve financial Situation | Often Fund for unimportant necessary |
| Potential Benefit | Education, assets or income | limited or no benefit |
| Repayment | should be managable | may be diffcult |
| Interest rate | should be reasonable | Cane be expensive |
| Example | Suitable education loan | credit card loan |
| Main Concern | Wheather benfits justify cost | creates financial stress |
Example:
Two people borrow ₹50,000.
Person 1: use money for education or skill course to increase your earning potential.
Person 2: Use money for umportant buying and shopiing and struggle to repayment it.
The amount is same , but purpose and repayment situation iis different.
That why understanding of debt matter.
Is Every Loan Good or Bad?
NO. Loan is not automatically Good or debt.
Same amount of loan or money may be help out and same loan for other person may be harmful .
Example:
Home loan with stable income maye be manageble and affordable EMIs.
Same loan with Unstable Income maye be unaffordable or create stress and gives more create debt to just repay.
Bedore Borrowing:
- Why do I Need this money?
- Can I afford the EMIs?
- What is the total cost of Loan?
- What happened if income may decreased?
How to Decide Whether Borrowing is Worth It
1. Understand the Purpose
Ask yourself, wheather is for unimortant purchases or gueine need.
2. Check the total Cost
Do math with overall cost of loan with repayment with interest. How much i Had to repayy to close this loan.
3. Check your Repayment Ability
Make sure with your budget that you are comfortable to repay his loans.
Income should be stable to end this loans.
4. Compare Your Options
Before Taking Loans, Compare repayment plan, Interest rate is important .
Loan Should not be to your financial stress.
How to Manage Existing Debt?
If you had already taken debt, You had to practical to mange it or finish this loan.
1. List all the debts
Write Down
- Oustanding loan amount
- Interest rate
- Monthy EMIs
- Remaining Repayment Period
Understand you totall debt amount.
2. Pay EMIs on time
Late payment create fines and heavy interest rates and affect financial credit history.
3. Avoid unncessary New Debt
try not to add up debt to for unimportart purchases.
4. Pay More When you can
If your loan allows it to make extra EMis may helps you to clear loans faster.
Check your loan condition before making extra repayments.
5.Build an Emergency Fund
Emergency fund is to cover you unexpected expense without trake another loan.
Common Debt Mistaks to Avoid
❌ Borrowing more than you needed
Taking latger loan than necessary can increase your repayment buden.
❌ Looking only EMIs
Low EMIs may come with longer repayment peroid with higher total costs.
❌Using Credit Card for every purchases
Credit can be useful but depnding on it all it slowly financial disaster and may create financial stress.
❌ Ingoring Interest Rates
Ingoring interest rate sis biggest mistake to avoid it makes difference repayment of loans.
❌ Taking Loans Without repayment plans.
Before borrowing. plan for repay your loans.
FAQs
1. What is the difference between good debt and bad debt?
Good Debt May helps you grow in your life like increase your income, higher education and rpayment afoordable.
Bad Debt may create financial burden and uncessary purchase with inaffordable EMIs.
2. Is a Home Loan Godd Debt?
Home loan may be useful when you has stable income with proper repayment plan. Borrowing money beyond create financial unstability.
3. Is an Educated Loan is Good Debt?
An education Loan may depend on the course, skills that you learn and repayment it easily by future income potential.
4. Is credit card Debt always Bad?
Credit card are not automatically bad. Paying in fullu balance on time can help you additional discount on many purchases. Carry unnecessary debt can rise your problems.
5. How can I avoid Bad Debt?
Create a budget, borrow only when necessary and plan the repay before take a loan and make sure repay goes on time. try to finish the loans as soon as possible.
Link this article to:
- What Is Money? Meaning and Importance of Money
- What is Financial Literacy?
- Financial Literacy Vs Financial Education : What Is the Difference?
- What Are The 5 Main Areas of Personal Finance?
- What Is Financial Planning? A Beginner’s Guide
- What Is Money Management? A Beginner’s Guide
- What is Saving?
- What Is a Budget? Meaning, Types & How to Create One
- What is Income?
- What is an Expense?
- What is Budget?
- What is Saving?
- What is Inflation?
- What is Investing?