What Is a Bond?
A bond is a financial instrument through which a government, company or other eligible issuer borrows money from investors.
When you buy a bond, you are essentially lending money to the issuer. In return, the agrees to pay interest according to the bond’s terms and repay the principal at maturity, subject to its ability to meet its obligations.
Example:
A company may issue bonds to raise money for expanding its business, purchasing equipment or funding new projects. A government may issue bonds to finance public speaking.
In Simple words:
A bond is a way to lend money to a government or company in exchange for interest and the agreed repayment of the principal.
Bonds are commonly called fixed-income investments, although not every bond pays a fixed interest rate and bond returns are not guaranteed.
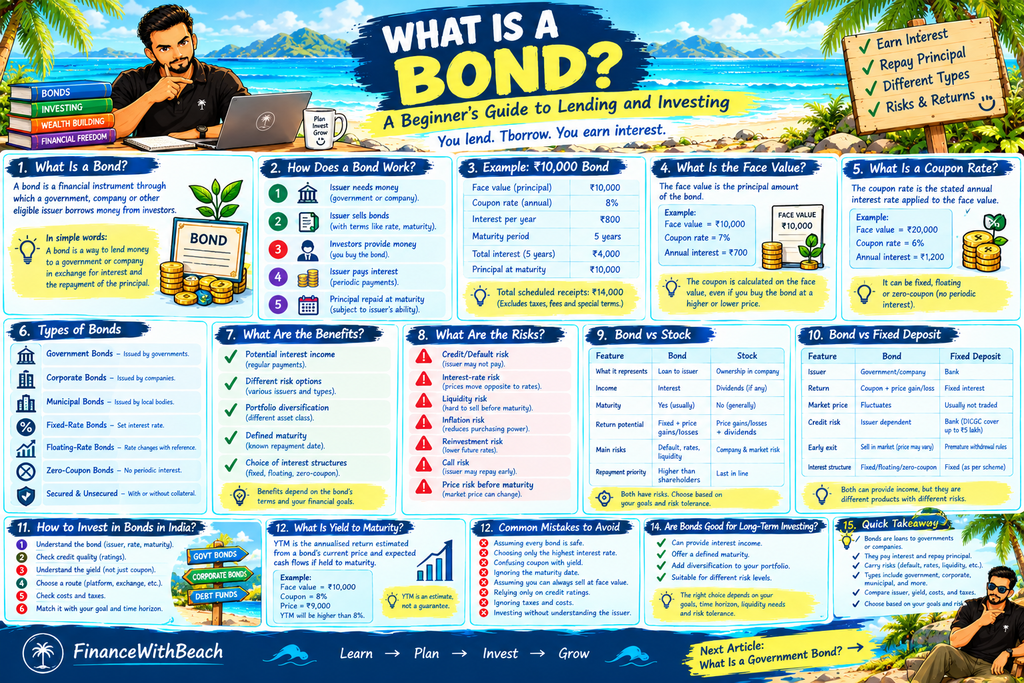
Table of Contents
How Does a Bond Work?
Let’s understand the basic process step by step.
Step 1: An issuer needs money
A government or company needs funds to finance its activities or projects.
Step 2: The issuer sells bonds
The issuer offers bonds to investors. Each bond has specfic terms, such as its face value, interest rate and maturity date.
Step 3: Investors provide money
When you purchase a bond, you lend money to the issuer under the bond’s terms.
Step 4: The issuer pays interest
Dpending on the bond, you may recieve interest payments monthly, quarterly, half yearly, annually or at another specfied time. SOme bonds do not make periodic interest payments.
Step 5: The bond reaches maturity
At maturity, the issuer is generally required to repay the principal according to the bond;s terms. However, repayment depends on the issuer fulfilling its obligation; default is possible.
Example: How Does a Bond Work?
Let’s say you buy a bond with these hypothetical terms:
| Feature | Example |
|---|---|
| Face value | ₹10,000 |
| Annual coupon rate | 8% |
| Interest per year | ₹800 |
| Maturity period | 5 years |
| Principal due at maturity | ₹10,000 |
If the bond pays an 8% annual coupon on its ₹10,000 face value, the scheduled interet would be ₹800 per year.
Over five years, you would recieive ₹4,000 in total interest if every scheduled payment is made. At maturity, the issuer would repay the ₹10,000 principal according to the bond’s terms.
Your total scheduled receipt would be ₹14,000 over five years, assuming the bond is held for the full term and and payments are made.
This example excludes taxes, fees and any special bond conditions. It also assumes you purchased the bond at face value. Of you a bond for more or less than its face value, your actual return can differ.
What Is the Face Value of a Bond?
The Face value, a;sp called the par value or nominal value, is the pricncipal amount specified for a bond.
Example:
A bond may have a face value of ₹1,000 or ₹10,000.
The face value is imoortant because the coupon payment is often calculated as a percentage of it.
Let’s say A bond has a face value of ₹10,000 and a coupon rate of 7%.
Annual coupon interest:
₹10,000 x 7% = ₹700
If you purchase that bond for ₹9,500 in the market, the coupon is still generally calculated on the face value of ₹10,000 according to the bond’s terms. Your overall return, however, also depends on th price you paid and the amount received at maturity.
What Is a coupon Rate?
The coupon rate is the stated annual interest rate applied to a bond’s face value.
Example:
A bond with a face of ₹20,000 and a 6% annual coupon rate would pay ₹1,200 in annual interest if it pays coupons annually and all payments are made.
Coupon payments may occur at different intervals depending on the bond’s terms.
Some bonds have fixed coupon rates, while others have variable of floating rates. Zero- coupon bonds generally do not pay periodic interest.
What Is the Maturity Date of a Bond?
The maturity date is th date on which a bond is scheduld to reach the end of its term.
On that date, the issuer is genrally expected to repay the outstanding principal according to the bond’s conditions.
Example:
- A Bond issued for one year has a one-year term.
- A bond issued for five year has A five-year term.
- A bond issued for ten year has A ten-year term.
The maturity date matters becuase it helps investors understand when repayments is scheduled and how long their money may remain committed.
However, if you sell a bond before maturity, you may reiceve more or less than the amount you orginally invested.
What Are the Different Types of Bonds?
Bonds differ according to who issues them, how they pay interest and the irsks involved.
1. Government bonds
Government bonds aree issued by governments to borrow money.
India, the Central Governement issues government securities, including longer-term dated securitites. State governments issue State development loans.
Government securitiescarry risks that differ from corporate bonds. Their market prices can still fluctuate, particularly when interest rate changes.
Example:
An investor purchases a government security that pays interest according to its stated terms.
2. Corporate Bonds
Corporate bonds are issued by companies to raise money for business purposes.
A company may use the funds for ecpansion, new equipment, infrastructure or refinancing existing debt.
Corporate bonds involve the risk that the company may not make its scheduled interest payments or repay the principal.
credit ratings can help investors assess credit risk, but a rating is an opinion, not a guarantee of repayment.
3. Municipal Bonds
Municipal bonds are debt instruments issued by egilable local government bodies or municipal entities to fund projects such as water supply, roads or ublic infrastructure.
Their availability, structure and risks depend on the specfic issue and applicable rules.
4. Fixed-rate Bonds
Fixed-rate bonds have a stated interest rate that generally remains unchanged during the relevant term.
Example:
A bond with a 7% annual coupon may continue paying that rate according to its terms, even if market interest rate change.
Its market price may nevertheless rise or fall.
5. Floating-Rate Bonds
Floating-rate bonds have interest payments linked to a reference rate or another specified formula.
Their interest payments may change when the reference rate changes.
6. Zero-coupon Bonds
Zero-coupon bonds generally do not pay regular interest.
They may be issued or purchased at a discount to their maturity value. If the issuer makes the required repayment, the difference between the purchase price and the maturity payment contributes to the investor’s return.
7. Secured and Unsecured Bonds
A secured bond is backed specified collateral, subject to its legal terms.
An unsecured bond does not have the same specific collateral backing. The recovery available in a default depends on the issuer’s financial position, legal arrangements and applicable insilvency rules.
Remember:
The name of a bond oes not tell you its complete risk profile. Review The terms, issuer, repyment obligation and relevent disclosures before investing.
What Are the Benefits of Bonds?
Bonds can play a role in an investment portfolio, depending on the investor’s goals and the bond’s charcheristics.
1. Potential interest income
Many bond pay interest according to schedule, which can help investors plan their expected cash flows.
However, payments depend on he bond’s terms and the issuer meeting its obligations.
2. Different risk options
Governement and coprorate bonds offer different types of exposure. Investors can compare maturity periods credit quality and interest structures.
Different option come with different risks.
3. Portfolio diversification
Bonds cn provide expsoure to adifferent asset class from stocks.
Their returns do not always move in the same way as equity returns, although bonds can also decline in value and diversification cannot eliminate investment risk.
4. Defined maturity
Many bonds have a specfied maturity date, which helps investors understand when principal repyament is scheduled.
This can be useful when matching investments with future financial goals, provided the investors accounts for repayments and market risks.
5. Choice of interest Structures
Investors may find fixed-rate, floating-rate and zero-coupon bonds depending on the market and available products.
Each structure behave differently when interest rates and ecnomic conditions change.
What Are the Risks of Bonds?
Bonds are not automatically safe simply because they pay interest.
1. Credit or Default Risk
The issuer may fail to pay interest or repay the principal as promised.
Example:
A financially troubled company may struggle to meet its bond obligations.
Coprorate bonds with higher credit risk may offer higher yields to compensate investors but a higher uiled does not make the investment better or safer.
2. Interest-Rate Risk
Bodn rpices generally move in the opposite diection to market interest rates, all else being equal.
when markey interest rates rise, existing bonds with lower coupon rates may beomce les attractive, causing their prices to fall. When market fall, existing bonds with higher coupon rates may become more attractive, potentially raising their prices.
3. Liquidity Risk
some bonds are not traded frequently
If you need to sell one before maturity, there may not be enough buyers at a reasonable price. You mighe have to accept a lower price or wait longer to sell.
4. Inflation Risk
Inflation reduces the purchasing power of money over time.
Even if a bond pays interest as cheduled, rising prices can reduce the real value of the income you receive.
5. Reinvestment Risk
if you receive interest payments and want to reinvest them future investment opportunites may offer lower rates than your orginal bond.
This can effecr the total return you earn over time.
6. Call Risk
Some bonds allow the issuer to repay them early under specified conditons.
If a bond is called when market interest rates are lower, you may have difficulty finding another investment with a similar yield.
7. Price Risk Beofre maturity
if you sell a bond before its maturity date, the market price may be above or below what you paid.
Even When a bond has scheduled interest payments, you can still expernience a loss if you sell it an unfavorable price.
What Is the difference Between a Bond and a Stock?
| Feature | Bond | Stock |
|---|---|---|
| What it represents | Money lent to an issuer | Ownership in a company |
| Investor’s role | Creditor or bondholder | Shareholder |
| Potential income | Interest payments, if specified and paid | Dividends, if declared |
| Maturity | Many bonds have a maturity date | Ordinary shares generally have no maturity date |
| Return potential | Interest plus possible price gains or losses | Dividends and possible share-price gains or losses |
| Main risks | Default, interest rates, liquidity, inflation | Company performance and market movements |
| Repayment priority | Bondholders generally rank ahead of shareholders, subject to the law and instrument terms | Shareholders generally rank behind creditors |
Neither investment tyoe is risk free. their suitability depends on your goals, time horizons and tolerence for losses.
What is the Difference Between a Bond and a Fixed Deposits?
Bothe can be used people looking for income, but they are different financial products.
| Feature | Bond | Bank Fixed Deposit |
|---|---|---|
| Who receives your money | A government or other bond issuer | A bank |
| Return | Depends on the bond’s coupon, purchase price, and other terms | Depends on the FD’s interest terms |
| Market price | Can fluctuate if the bond is traded | Usually not quoted like a traded bond; premature withdrawal is subject to the bank’s terms |
| Credit risk | Depends on the issuer and bond | Depends on the bank and applicable deposit-protection rules |
| Early exit | May require selling at the market price | May involve premature-withdrawal rules or penalties |
| Interest structure | Fixed, floating, zero-coupon, or other terms | Depends on the chosen deposit scheme |
In India, Eligible bank deposits are covered by DICGC insurance up to the applicable limit of ₹5 lakh per depositor per bank, including principal and interest, subject to the insurance rules. THis is different from bond protection and bonds should not be assumed to carry deposit insurance.
How can Beginners Invest in Bonds in India?
The process depends on th type of bond you want to buy.
Step 1: Understand the bond
Identify the issuer, maturity date, coupon rate, repayment terms and risks.
Step 2: Review credit quality
For corporate bonds, examine the credit rating and other infromation about the issuer’s ability to repay its debts. Never rely on a rating alone.
Step 3: Understand the Yield
The coupon rate is not the same as yield to maturity. Yeild to maturity estimates the annualised return implied by the bond’s price and cash flows, assumin the relvent payments occur as expected and the bond is held to maturity.
Step 4: Choose an appropriate route
Dpending on the security, Investors may access bonds thrugh official government-security platform, public issues, registered inetermediearies or the stock exchange.
The account requirements and avilable instruments vary.
Step 5: Check costs and taxes
Review trnsaction charges, applicable taxes and tax treatment of interest income and any capital gains.
Step 6: Consider your financial Goals
Think about when you may need the money, whether you can hold the bond until maturity anfd how much risk you can accept.
What IS Yield to Maturity?
Yield to maturity (YTM) is an estimate of the annualised return implied by a bond’s current price and its expected cash flows if held to maturity.
YTM cosniders factors suchs as the bond’s purchase price, coupon payments, fsce value, and remaining time until maturity.
Example:
A bond purhchased below it face value may have a higher yield to maturity than its coupon rate, assuming the issuer makes all requiredpayments. A bond purchased above face value may have a lower yiled to maturity than its coupon rate.
YTM is an estimate, not gurnateed. The actual outcome may differ if the bond is sold early, oayments are missed or other assumpption do not hold.
Common Beginner Mistakes to Avoid
Mistake 1: Assuming every bond is safe
bonds have different levels odf credit, interest-rate and liqudity risk.
Mistake 2: Choosing only the highest interest rate
A high advestised rate may reflect higher risk. Understand why the bond offers that rate.
Mistake 3: confusing coupon rate with yield
The coupon is based on the bond’s terms, while yield also depends on the price you pay and other factors.
Mistake 4: Ignoring the maturity date
Make sure the inevstment period suits when you expect to need the money.
Mistake 5: Assuming you can always sell at face value
A bond’s market price may change before maturity.
Mistake 6: relying only on credit ratings
Ratings can chnage and do not gurantee repayement. Read the avialable issuer and bond information.
Mistake 7: ignoring taxes and costs
Taxes and transaction charges can reduce your net worth.
Mistake 8: Investing without understanding the issuer
Before invsting, check who owes you the money and howthe issuer is expected to repay it.
Are Bonds Good for Long-Term investing?
Bonds may be useful for investors who want interest incopme, a defined maturity or exposure beyond stocks. However. different bonds have different risks and returns charcterisitcs.
Example:
A governemtn security and a lower-rated corporate bond should not be treated as equivalent investments. Even givernement bonds can flucluate in market price before maturity.
The right coice depends on your financial goals, time horizons, liquidity needs and risk tolerence.
there is no single bond that is best for everyone.
FAQs
What is a bond in simple words?
A bond is a way to lend money to a government or company in exchange for interest and the agreed repayment of the principal as scheduled.
How do bonds make Money
Investors may earn interest payments and may also make a gain igf they sella bond for more than they paid. Theyu can als experience losses.
Are bond risk-free?
No. Bonds can carry default risk, interest-rate risk, liquidty risk, inflation risk and other risks.
What is the difference between a bond and a stock?
A bond rperesnetsa loan to an issuer, while a stock generally represents ownership in a company.
What is the maturity date of a bond?
It is the date on wich the bond is scheduled to mature and the principal is genrally due for repayment according to its terms.
What is a coupon rate?
The coupon rate is the stated annual interest rate applied to the bond’s face value.
Can I Lose money in bonds?
Yes. You may lose money if the issuer defaults or if you sell the bond for less than you paid. The exact risk depend on the bond.
Can beginners invest in bonds in India?
Yes, subject to the eligibility and requirements of the investment route. Beginners should first understand the bond’s terms, risk costs and tax treatment.
Link this article to:
- What Is Bank Account?
- What Is ATM?
- What Is UPI payment?
- What Is Recurring Deposit?
- What Is a Asset?
- What Is a Dividend?
- Simple Interest and Compound Interest
- What Is a Return on Investment?
- What Is Risk in Investing?
- What Is Diversification
- What Is a Portfolio?
- What Is an Index?
- What Is an Stock MArket Index?
- What Is an Mutual Fund?
- What Is an SIP?
- What Is an Index Fund?
- What Is an ETF?
One thought on “What Is a Bond? — A Beginner’s Guide to Lending and Investing”