What Is a Fixed Deposit (FD)?
A Fixed Deposit (FD) is a savings product where you deposits a specfic amount of money with a bank or financial institutions for a fixed period at agreed interest rate.
In simple Words:
A fixed deposits allows you to keep money for specfic period and earn interest according to the FD terms.
Unlike a saving account, whereyou can access your money whenever you need it, an FD is designed for specfic period.
Example
You might deposit ₹1,00,000 for 3 years.
The bank pay you fixed interest rate in that tenure will added into account of FD. At the maturity time, all the orginal deposits and applicable interest with taxes, deduction and agreed terms combined comes to your bank saving accounts.
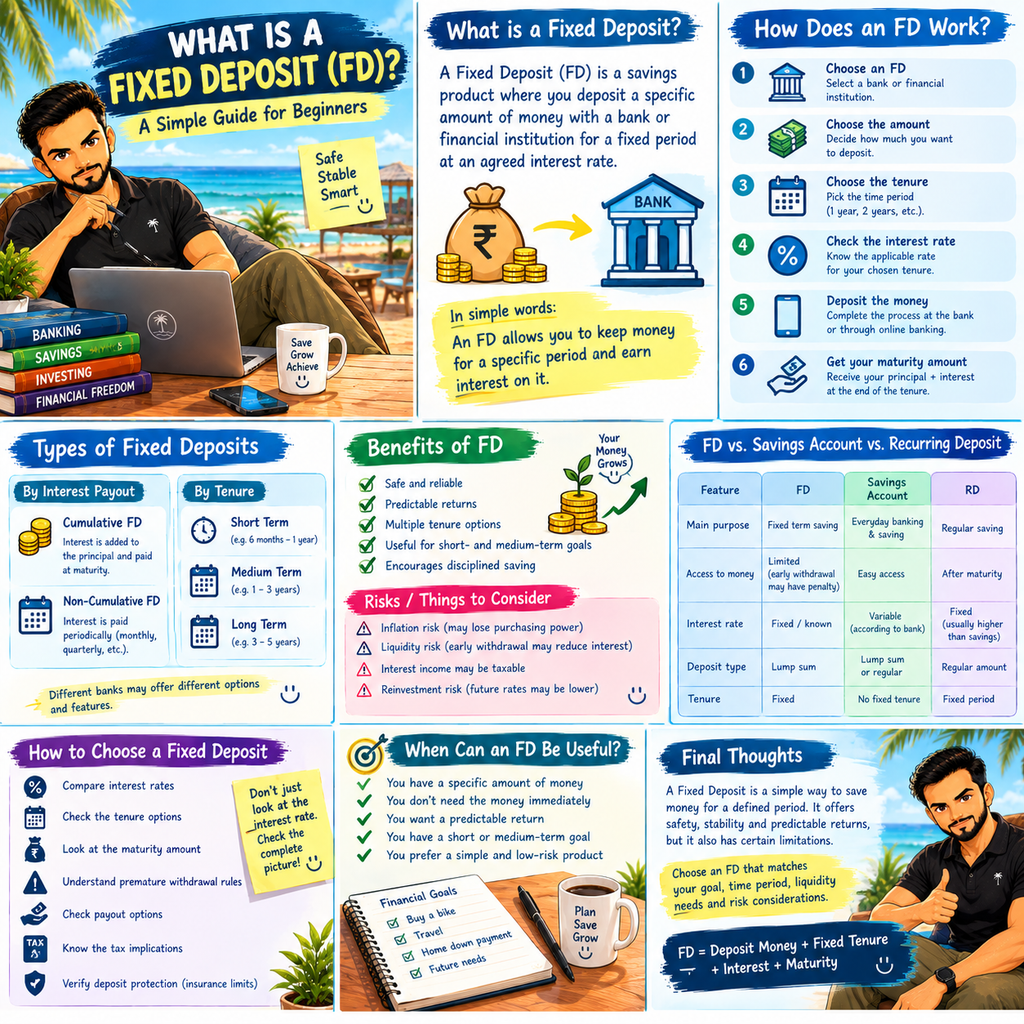
Table of Contents
How Does A Fxed Deposit Work?
The process is retatively simple.
Step 1: Choose an FD
You select a bank or eligable financial istitution and review its avauilable FD options.
Step 2: Choose your Deposit Amount
Example:
₹1,50,000 for 3 years
Step 3: Choose your Tenure
You select how long you want to keep your money into deposits accounts
Example
1 year, 2 year, 3 year, 4 year and goes on.
Step 4 : Check your Interest Rate
The financial institutions provides an interst rate for slected tenure and FD.
Step 5: Deposit your money
You pace your money into your FD.
Step 6: Wait Untill Maturity
The deposit will mature which you slected your tenure and FD agreed terms. Till ten you have to wait till maturity period or tenure gets completes as agreed in FD Terms.
Step 7: Receive the matuirty Amount
At Maturity, you receive the deposit plus applicable deposit, subject to prdouct term’s.
What Is FD Interest?
FD interest is th amount the bank or fiancial insitutions pays you for keeping your money deposited for the agreed period.
Example:
Deposit:₹1,50,000
Insterest rate: 7% for a year
The interest calculate according to the FD term’s.
Some deposits may offers compound interest, whilew others may offers periodic interest payout.
Check the actuall total maturity amount and pay structure.
What Is FD Tenure?
Tenure means the length of uour deposits how much long you can keep your deposits in the FD.
Example:
- 6 months
- 1 year
- 2 year
- 4 year
- 3 year
- 10 years
Teh available option depends on the bank or financial istitutions.
you should choose your tenure according to your need, when i need this money.
If you need very soon, ther may deduction + charge for per matuirty to witdraw your money earlier. choose your tenure wisley your tenure.
What Is FD Maturity?
Maturity is the date on which the agreed Fd tenure ends.
Example:
If you open in 1st january 2026 tenure for 2 years.
the maturity date will be 1st january 2027
At maturity the deposits can genrally be apis according to the terms.
Dpedning on the product, you may have options such as:
- Renew your FD
- Total maturity amount to recieved
- Recive month to month od quartarly if you agree
Always check bank specfic terms.
What Happens If You Withdraw an FD Early?
Sometime somthing happen in life you required sudden money for emergency. So required Fd before matuirty.
Thos is called Permature Withdrawal.
Dpending on your bank and terms of FD, Premature may results into:
- A lower applicable interest rate
- A penatly
- Reduce earing interest
- Other applicable conditions
Before opening your FD, understand the premature withdrawal rules.
Cumulative vs. Non-cumulative FD
Fixed deposits can have different payout stuctures.
Cumulative FD:
Cumulative FD, interest is generally accumalated and paid along with priccipal at maturity.
This can be useful if you wanted total money in pay to help in your achieve goal of purchases.
Non-Cumulative FD:
Witha Non-cmumulative Fd, you get interest and principal amount in periodically payout structure:
Example:
- Monthy
- Yearly
- Quartarly
- Half yearly
Teh avaiulable payout vary Fd terms and Conditions with BAd or financial Institutions.
FD vs. Savings Account
Both can be used witha bank, but they serve differently purposes.
| Feature | Savings Account | Fixed Deposit |
|---|---|---|
| Main purpose | Everyday saving & banking | Fixed-term saving |
| Access to money | Generally easier | May have restrictions |
| Interest | Usually variable according to account terms | Fixed/known according to FD terms |
| Tenure | No fixed maturity | Fixed tenure |
| Premature withdrawal | Usually not applicable in the same way | Conditions may apply |
| Suitable for | Emergency & everyday funds | Money you may not need immediately |
FD vs. Recurring Deposit
A Fixed deposits and Recurring deposits(RD) are both savings products, but they work differently.
Fixed Deposit
You genraslly deposit a lump sum once.
Example:
₹1,00,00 → FD
Recurring Deposit
You generally deposit a fixed amount regularly.
Example:
₹3,000 every month → RD
FD = Lump sum deposit
RD = Regular deposits
Benefits of Fixed Deposits
1. Simple to Understand
FDs are retatively very simple and straightforward in terms to invest and returns and compared with other investment products.
2. Predictable Returns
For Fixed-rate FD, the interest rate is generally known when you open the deposit, subject to the products terms.
3. Diffferent Tenures
You had different time period of investment options.
4. Useful for short or Medium Term Goals
An FD may be considered for money you expect to need for specfic time period.
5. Can Encourage Disciplined Saving
Because the money is placed for a defined period, it may reduce your immediately spending.
What Are the Risks of an FD?
Athough it is alow risk than a larket linked investment,there are not competely withut cosnerations.
1. Inflation Risk
If the FD’s after tax return is lower than inflation, your money may lose purchasing power over time.
Example:
If your FD earn 6% but inflation is 7% your money is growing in niminal terms but losing Purchasing power over time.
2. Liquidity Risk
You may need to pay a penatly or charges if you withdrwal the money premature.
3. Tax
Inetrest earned on FD may be Taxable according to applicable tax rules.
4. Reinvestment Risk
When you mature Fd, Next FD may be diffrent interest rate.
Is an FD Completely Risk-Free?
It is never be risk free or any other investment products.
It can be minimum risk but never be Risk free investment.
Factors scuh as:
- The Financial Insituations
- Applicable deposits insurance
- Deposits limits
- Pemature charges and penatlies
- Tax rules
- Inflation
- Terms and conditions
Before putting larger amount of money deposits check your terms and safety to secure your investment before misfortune happens.
Should You Put Your Emergency Fund in an FD?
An emergency fund should be easily accessible at any time.
Because premature withdrawal may have charges or involves conditions ot reduced interest, you do not want your emrgencies fund lock gor long term.
A possible approcah should highly accessible with same day payout with very low deduction and taxes also nominal.
Your fiancial situation and conditions defines your approach.
How to Choose a Fixed Deposit?
Before Opening FD, compare more than the interest rate.
Check:
1. Interest Rate
Compare the rate offeres to your desried value.
2. Tenure
Choose your period that matches your financial goals.
3. Maturity Amount
Check how much you got at the time of maturity.
4. Premature Withdrawal Rules
Understand what happen when you needed your early.
5. Payout Option
Check whethewr interest is paid periodically or at maturity.
6. Tax Treatment
Udnerstand how the interest wiil be treated udner applicable tax rules.
7. Deposit Protection
Check the aplicable deposit isnurance coverage and limits.
Whan Can an FD Be USeful?
An FD may cosnsidered when you:
- Have specfic amount of money
- Knwo your won’t money immediately
- Have a short and medium term financial goals
- Pefer simple Saving product
You Might compare an FD with ther suitable saving or investment option based on:
Safety +Liquidity + Return + Tax + Time horizon
FAQs
What is a Fixed Deposit?
A Fixed Deposit (FD) is a savings product where you deposits a specfic amount of money with a bank or financial institutions for a fixed period at agreed interest rate.
What does FD stand For?
FD stand for Fixed Deposit.
How does an FD Work?
You choose to deposit specfic amount, choose the tenure and earn interest according to your FD’s terms. At maturity, you generally recieve the principal plus Applicable interest.
Can I with draw my FD before Matuirty.
Many FD allows you to premature withdrawal but odnitions, penalties or rduced interest rate may apply. Check your bank’s terms before with drawing.
Is FD interest Taxable?
FD interest may be taxable dpending on your indivdual income tax slab and applicable tax rules.
What is FD Maturity?
Maturity is the date when the Selected FD Tenure ends and deposits become payable according to your bank term’s.
What is the difference between Cumulative and non-cumulative FD?
With cumulative FD, Interest is generally accumalated and paid along with priccipal at maturity.Witha Non-cmumulative FD, you get interest and principal amount in periodically payout structure.
For Standard bank account UPI payment, you generally required to registration details.
Link this article to:
- What is Saving?
- What is Income?
- What is Compound Interest?
- What Is Inflation?
- What is Insurance?
- What is investing?
- Types of Investment?
- What is Budget?
- Saving vs Investing
- What is Net worth?
- What Is Exapenses?
- What is Cash Flow?
- What is Liquidity
- What Is Loans?
- What Is EMI?
- What Is Credit Card?
- What Is Bank Account?
- What Is ATM?
- What Is UPI payment?
One thought on “What Is a Fixed Deposit (FD)? A Simple Guide for Beginners”