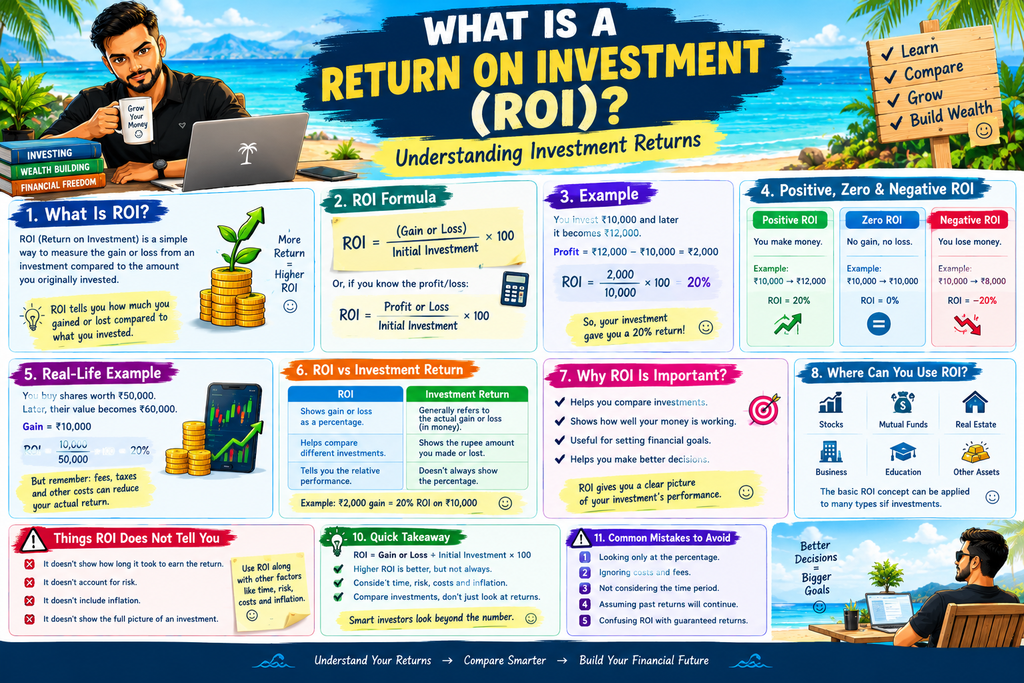
What Is a Return on Investment (ROI)? — Understanding Investment Returns

What Is a Return on Investment (ROI)?

When you invest your money one of the first question you may have is:

“How much did I actually make from this investment?”

This is where Return On Investment, commonly called ROI becomes useful.

ROI is a simple way to measure the gain or loss from an investment compared with the amount of money you orginally invested.

In simple Words:

ROI tells you how much you gained or lost compared with that you invested.

Understanding ROI can help beginners compare diferent investments and understand whether an investment produced a profit or loss.
What Does ROI mean?

ROI stands for Return on Investment.

It measures the return generated by an investment relative to its original cost.

Example

Let say you invested ₹10,000 in something and later sell at ₹12,000.

Your profits on

₹12,000 – ₹10,000 = ₹2,000

Your ROI is:

₹2,000 ÷ ₹10,000 x 100 = 20%

So your investment produced a 20% ROI.

ROI Formula

The basic formula is:

ROI = (Investment Gain – Investment Cost) ÷ Investmetn Cost x 100

or if you already know the profit or loss

ROI = Profit or loss ÷ Initial Investment x 100

Example

You Invest ₹20,000.

After some time, your investment becomes ₹24,000.

Your gain is:

₹24,000 – ₹20,000 = ₹4,000.

Therefore:

ROI = ₹4,000 ÷ ₹20,000 x 100

ROI = 20%

Your ROI is 20%.

Understanding Positive and Negative ROI

ROI can be positive,zero or Negative.

Positive ROI

If you make money, your ROI is positive.

Example:

Investment = ₹10,000

Final value = ₹12,000

ROI = +20%

Zero ROI

If you neither gain nor lose money, your ROI is Zero.

Example:

Investment = ₹10,000

Final value = ₹10,000

ROI = 0%

Negative ROI

If you lose money, your ROI is negative.

Example:

Investment = ₹10,000

Final value = ₹8,000

Loss:

₹8,000 – ₹10,000 x 100 = -20%

ROI = -20%

ROI vs Investment Return

These terms are related but should not always be treated as exactly the same thing.

Investment rteurn generally refers to th gain or loss genrated by an investment.

ROI expresses that gain or loss relative to the amount invested usually as percentage.

Example:

  • Investment: ₹10,000
  • Gain: ₹2,000
  • ROI: 20%

The ₹2,000 is th gain.

The 20% is th ROI.

Why is ROI Important.

ROI provides a simple way to understand invetment performance.

Let say have two investments:

Investment A

  • Investment: ₹10,000
  • Gain: ₹1,000
  • ROI: 10%

Investment B

  • Investment: ₹10,000
  • Gain: ₹2,000
  • ROI: 20%

Looking only at the rupee profit shows that Investment B Genrated More Profits.

ROI also Puts the returns into percentage terms, making it easier to compare investments with diferent amounts.

Can ROI Be Used for Different Investments?

YES.

The baisc ROI concept can be applied to many Situations.

Example:

Stocks

You can claculate the gain or loss compared with the amount invested.

Mutual Funds

You can Campare your investment amount with its current or final value.

Real Estate

You can compare the gain from selling a property with the amount invested, athough a complete property analysis may need to include expenses such as maintenance, taxes, financing cost5s and transaction costs.

Business

A business owner can compare the profit generated by a project with amount spend on it.

Education

People sometimes use ROI as framework for thinking about education by comparing its costs with potential financial benefits, although many non-financial factors also matter.

ROI Does Not Tell the WHole Story

ROI is useful, but it hase an important Limitation:

It doen’t automatically tell you how long it took to earn the return.

Investment A

You invest ₹10,000 and make a 20% return in 1 year.

Investment B

You invest ₹10,000 and make a 20% return in 5 year.

Both have ROI 20% total ROI.

But the time period is very different.

This is why you should consider time when comparing investment returns.

ROI vs Annualized Return

If two investment have different time periods, a simple ROI comparison may not be enough.

Example:

Investment A: 20% ROI in 1 Year

Investment B: 20% ROI in 5 Year

The total ROI is the same, but the investment periods are not.

Measures such as annualized return can help provide a time adjusted view investment performance.

For investment that compared, the annualized return of often more informative than simply dividing total ROI by the number of years.

ROI and Compound Growth

ROI and Compound growth are coonnected, but they are not the same concept.

ROI tells you the overall percentage gain or loss relative to the original investment.

Compounding describes how reurns hat remain invested can contribute to futre growth.

Example: Let say ₹10,000 grows at a hypothetical 10% annual rate:

  • Year 1 – ₹11,000
  • Year 2 – ₹12,100
  • Year 3 – ₹13,310

The total gain after three years is ₹3,310 giving a total ROI of 33.1%

This example assumes the same return every year and is purely for illustration.

ROI Example With a Loss

ROI isn’t only about profits.

Let say you invest ₹25,000 i n an investment.

Later, its value falls to ₹22,500.

Your loss is:

₹22,500 − ₹25,000 = −₹2,500

ROI:

−₹2,500 ÷ ₹25,000 × 100 = −10%

Your ROI is therefore −10%.

This is why investments should not be judged only by the possibility of making money. Investment values can also decline.

What Can Affect Your Actual ROI?

The simple ROI formula does not automatically account for every cost.

Dpedning on the investment you may need ot consider:

  • Brokerage fees
  • Transaction charges
  • Taxes
  • Managment fess
  • Maintenance costs
  • Pruchase and selling costs
  • Loan interest
  • Other investment related expenses

Simple Example

Suppose:

Investment = ₹10,000

Final value = ₹12,000

Before costs, your profit is ₹2,000.

But suppose you paid ₹200 in relevant costs.

Your net gain becomes:

₹2,000 − ₹200 = ₹1,800

Your net ROI would then be:

₹1,800 ÷ ₹10,000 × 100 = 18%

So the return after costs can be lower than the headline ROI.

ROI IS NOt teh Same as Risk

A high ROI does not automatically mean an investment is suitable for everyone.

Two investment could produce different returns while also having very different levels of risks.

Example:

  • Investment A may have a lower potential return and lower risk.
  • Investment B may have a higher potential return but greater uncertainly.

ROI measueres the return, not the complete risk profile of an investment.

This is why investors should cosnider both risk and returns.

Common Mistakes Beginnerss Make With ROI

1. Looking onaly at percentage

A 50% ROI sound large, but you should also understand the amount invested and the time time involved.

2. Ignoring Costs

Fees, Taxes and other expenses can reduce your actual return.

3. Ignoring the time period

A 20% return over one year is different from a 20% return over five years.

4. Assuming past ROI will continue

A pervious return does mot guarantee that the sam return will happen in the future.

5. Confusing ROI with Guaranteed returns

ROI can be positive or Negative. Investment involving market risk do not guarantee a particular ROI.

ROI and Inflation

Another Important consideration is Inflation.

Let’s your investment grows by 6% over a period while prices increase significantly during the same period.

Your money may have have increased in nominal valu but its purchasing power may not have increased by the same amount.

Therefore, when evaluating long term investment, it can be useful to think about both:

Investment return + Inflation

rather than looking only ROI alone.

FAQs

What does ROI stand For?

ROI stands for Return on Investment.

What is a good ROI?

There is no sim=ngle ROI percentage that is automatically “good” for ecery investment. it’s all dpends on time horizon, fees , taxes, costs and market conditions.

How do you calculate ROI?

ROI = Profit or loss ÷ Initial Investment x 100

Is ROI the same as profit?

No.

Profit is usally expressed as money amount while ROI expresses the gain or loss relative to the investment as a perecentage.

Can ROI be Negative?

Yes.

A negative ROI means the investment lost value relative to the Original Investment.

Link this article to:

Simple Interest vs Compound Interest — What’s the Difference?

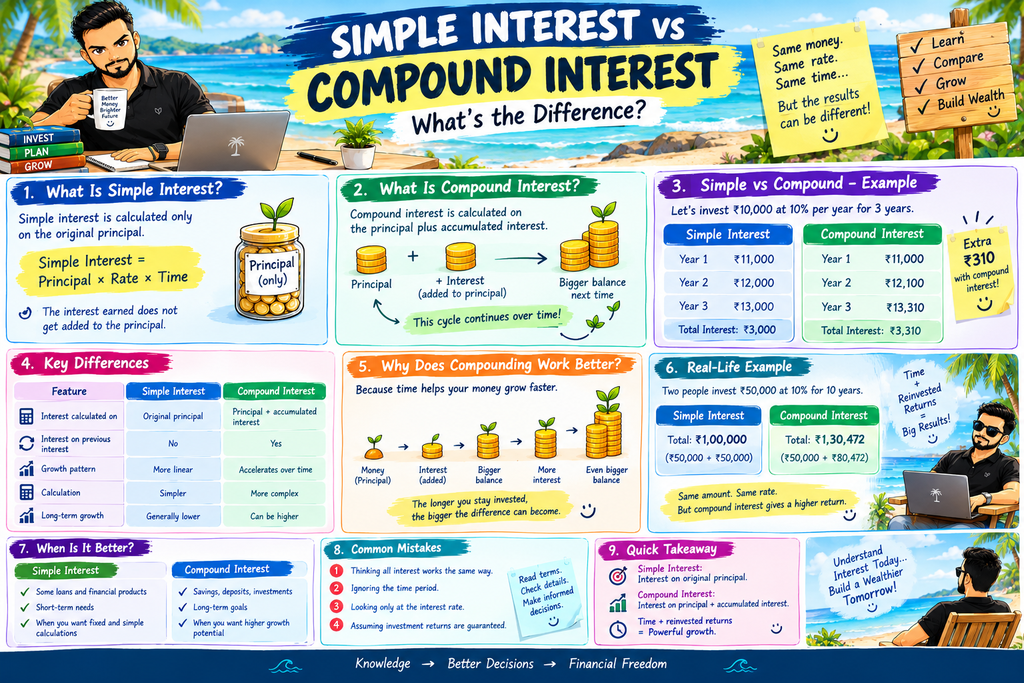
Simple Interest vs Compound Interest — What’s the Difference?

When you saver, or invest money you will often come across the word interest.

Interest is the extra money earned on savings or investments or the extra money paid when norrowing money.

There two ways to caluclated the interest:

  • Simple Interest
  • Compound Interest

Athough boyh include interest, they work diffrently. understadning the difference is important because is can affect how quickly your money grows or how much you eventually pay on a loan.

In this article, we will explain simple and compund interest using easy example.

What is Simple Interest?

Simple Interest is calculated only on the original amount of money, called Principal.

The interest earned does not get added to the principal when calculating interest for the next period.

Simple Interest Formula

Simple Interest = Principal x Rate x Time

Example:

Let’s say you invests ₹10,000 at 10% simple interest per year for 3 years.

  • Principal = ₹10,000
  • Interest Rate = 10%
  • Time = 3 years

Interest Earned:

₹10,000 z 10% x 3 = ₹3,000

So after 3 years:

Total = ₹10,000 + ₹3,000 = ₹13,000

The interest is calculated on the original ₹10,000 eavet year.

What Is Compound Interest?

Compound Interest is different because the inetrest you earn can be added to your original money.

Then, Future interest can be calculated on both:

Original Money + Previously earned money

This is often described as “interest on interest.”

FV=PV(1+r)nFV=PV(1+r)^n

Example:

Let’s say you invests ₹10,000 at 10% simple interest per year for 3 years.

Year 1

₹10,000 earns ₹1,000 interest

Balance = ₹11,000

Year 2

Now the 10% interest is claculated on ₹11,000.

Interest = ₹1,100

Balance = ₹12,100

Year 3

Interest is calculated on ₹12,100.

Interest = ₹1,210

Balance = ₹13,310

So after 3 years:

Total = ₹13,310

This is higher than the ₹13,000 produced by simple interest.

Simple Interest Vs Compound Interest:

Example

Let’s compare noth using the same starting amount.

Suppose:

  • Intial amount = ₹10,000
  • Interest rate = 10% per year
  • Period = 3 years
YearSimple Interest BalanceCompound Interest Balance
Start₹10,000₹10,000
Year 1₹11,000₹11,000
Year 2₹12,000₹12,100
Year 3₹13,000₹13,310

Difference

After 3 years:

Simple Interest = ₹13,000

Compound Interest = ₹13,310

The difference is ₹310.

The difference may look small over small year, but it can become much larger when money compounds for many years.

Key Difference Between Simple and Compound Interest

The easiest way to remember the difference is:

Simple Interest works on the original Principal. Compound interest works can be calculated on the principal plus accumlated interest.

Simple Interest

You earn interest on the original amount.

Compound Interest

You can earn interst on the original amount and perviously earned interest.

Simple Interest vs Compound Interest

FeatureSimple InterestCompound Interest
Interest calculated onOriginal principalPrincipal + accumulated interest
Interest on previous interestNoYes
GrowthMore linearCan accelerate over time
CalculationSimplerMore complex
Long-term growthGenerally lowerCan be higher at the same rate
Common useCertain loans and financial calculationsSavings, deposits, investments and some loans

The exact way interest is applied depends on the financial product ans its terms.

Why Does Coompound Interest Become Powerful Over Time?

The biggest difference between the two becomes visible over a longer period.

With simple interest, the interest amount remains based on the principal original princicpal.

With compound interest, the base used to calculate future interest can keep investing.

Example:

Your investment earn interest and you leave that interest invested instaed of taking it out.

Your money can follow a cycle lile this:

Money ➔ Interest ➔ Larger Balance ➔ More Interest ➔ Even Larger balance

This is why is an important part of compounding.

The longer money remains invetsed and compounds, the greater the potential difference can become.

Is Compound Interest Always Better?

Nit necessarily.

It depends on whether you earning interest or paying it.

When you are earning interest

Compound interest can help your money grow because previously earned interest can generate additional interest.

When you are brorrowing money

Compound interest can increase amount you owe when unpaid interest is added to the balance and subsequently acruese more interest.

That’s why very important to understanding the temr sof loans, credit products, deposits and investment before making financial decisions.

Simple Interest vs Compound Interest In Everyday Finance

You may encounter these concept in different areas of personal finance.

Savings

Some savings products may pay interest according to specfic compounding rules.

Fixed Deposits

Interest may be calculated and compounded according to the terms of the deposits.

Loans

Some loans use interest clalculations that can involve compounding while others use different methods.

Investments

Compounding is an important mathematical concept behind long term investment growth when returns remains invested.

Always check the specfic product’s terms rather than asuming that every financial product uses the same interest method.

Why Started Early Matters?

One of the important lessons from compound interest is the value of time.

Supppose two investors eventually invest the sme amount of money, but one starts several years earlier.

The earlier investor has more time for returns to portentially generate additional returns.

Example:

₹10,000 ➔ Returns ➔ Larger Returns ➔ more returns ➔ Larger balance

Over a long period, this repested process can have a signifcant effect.

This is ine reason compound interest is often discussed when learning about long-term investing and wealth building.

Simple Interest vs Compound Interest:Which Formula Should You Know?

For Simple Interest:

Simple Interest = P x R x T

Where

  • P = Principal
  • R = Interest rate
  • T = Time

For Compound Growth, a commonly used annual-compounding formula is:

A = P(1 + r)ⁿ

where:

  • A = Final amount
  • P = Principal
  • r = Annual interest rate expressed as decimal
  • n = Number of years

the actual calulation can differ when interest compund monthy, quarterly or at another frequency.

Common Mistakes Beginners Make

1. Thinking all interest works the same way

Different financial products can use different interest calculations.

2. Ignoring the time period

A rate tht looks attractive overa shor period may have a very different effect over period a long period.

3. Looking only at the interest rate

Fees, taxation,inflation, compunding freuqency and prdsouct terms can also affect the actual outcome.

4. Assuming investment returns are guaranteed

Compound growth examples often use a fixed rate for simplicity. Real market investments can rise and fall and actual returns may differ.

FAQs

Is Compound intereet better than simple interest?

When you are earning interest, compound interest can produce more growth than simple interest at the same rate and over the same period because perviously earned interest can also genenrate interest.

What is the main difference between simple and compound interest?

Simple Interest works on the original Principal. Compound interest works can be calculated on the principal plus accumlated interest.

Does Compound Interest Help investment Grow?

Compounding can cintrubute to long term growth when returns remains invested, However, market investment do not guarantee a fixed returns.

Can compound Interest increase Debt?

Yes. Depending on the product’s terms, unpaid interest can become part of the balance on which future returns is calulated.

Why is compound interest important?

it helps explain why money can gorw increasingly faster over long periods when reurns remain invested.

Link this article to:

What Is a Dividend? A Simple Guide for Beginners

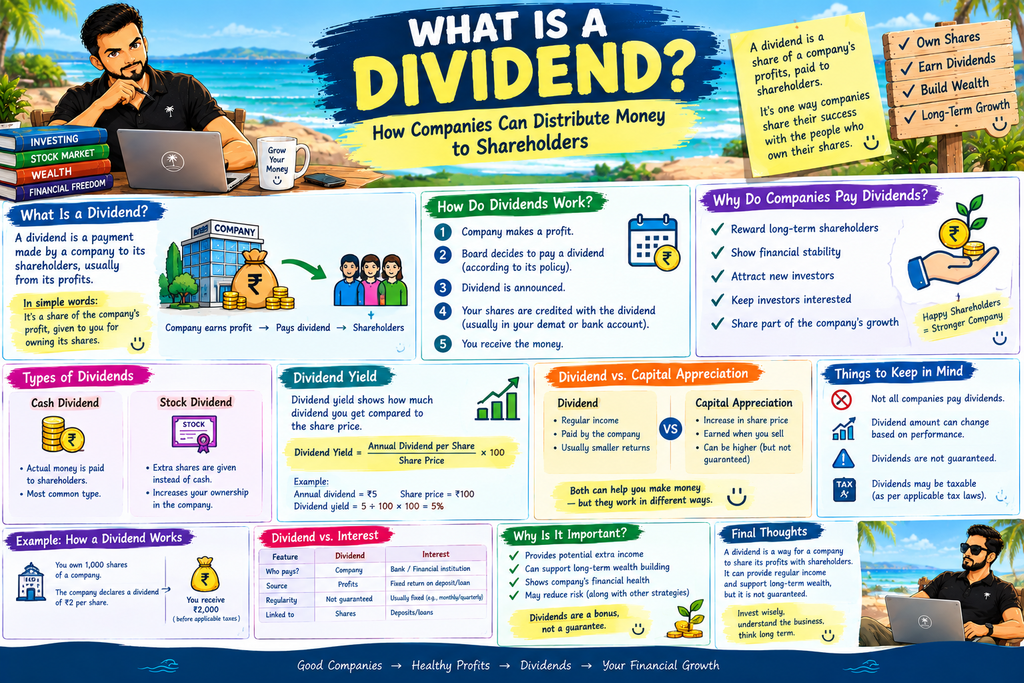
What Is a Dividend?

Hwn you start learning about stocks, you may hear the word dividend quite often.

But what exactly is dividend?

In Simple Words:

A dividend is a payment thaat a company may distribute to its shareholder, often from its profits or accumulated earnings.

When you own shares of a company that declares a dividend, you may receive money based on the number of eligible shares you own.

Example:

let you have 100 shares of a company.

If the company declare a dividend of:

₹6 per share

you could receive:

100 x 6 = ₹600

Before any applicable taxes or other consideration.

Companies are not required to pay divends simply because thay make a profit. Whether a dividend is declared depends onthe company’s policies, financial position, board decisions, applicables laws and other factors.

How Do Dividends Work?

The basic process is relatively simple.

Step 1: The company earns Money

A company operates it business and may generate profits.

Step 2: The company Decides what to Do with its Money

The company mau use it money for things such as:

  • Expanding the business
  • Buying Equipment
  • Developing Products
  • Paying debts
  • maintaining Cash reserves
  • Acquireing another business
  • Distributing money to shareholders

Step 3: A Dividend Id declared

If he company decides to ditribute a dividend, it announces the relevent details.

Step 4: Eligible Shareholders Receive the Dividend

Shareholders who meet the applicable eligibility requirements receive the dividend according to the company’s announced terms.

The payment may be credited to the investor’ bank account through the appplicable process.

Why Do Companies Pay Dividends?

Companies may pay dividends for several reasons.

1. Sharing Profits With shareholders

A company may distributes part of its earnings to shareholders.

2. Returing Capital to investors

Dividends can be one wayt to return capital to investors.

3. Attracting Certain Investors

Some investors prefer companies that have a history od ditributing dividends.

4. Showing Financial Strength

A consistent dividend history may be viewed by investors as one part of a company’s Financial profile athough a dividend by itself does not guarantee that a company if fiancially strong.

Do all Companies Pay Dividends?

NO.

This is one of the important things beginners should understand.

Some companies pay regular dividend, while other reinvest in company.

Example, instead of paying:

10 crore rupees in dividends.

A company might use that money to:

  • Open new location
  • Develop new procduct
  • Hire employees
  • Purchases machinary
  • Exapand internationally

The company’s approach depends on its busness strategy and financial circumstances.

Types of Dividends

There are different ways companies can distributes values to share holders.

1. Cash Dividends

A cahs divdiend is the most familier type.

The company pays aligible shareholders money.

Example:

  • ₹4 per share
  • If you own 500 shares:
  • 500 × ₹4 = ₹2,000

2. stock Dividend

Instead of paying cash. a company may distribute additional shares eligable shareholders under the applicable terms. Example

A company could distribute additional shares based on a specfied ratio.

This increases the number of shares an investor owns, athough the overall ecnomic eggects depdnds on the company’s valuation and terms od the distributions.

3. Special Dividend

A company may sometimes declares a speical dividend which is anadditional; or unusal distrubution outside its regular divdiend pattern.

This can happen when a company has excess cash or experiences an unusal financial event. Special divdiend are not necessarily recurring.

What Is Dividend Yield?

Another Important terms is Dividend Yield

Dividend yield shows the annual dividend relative to the current share price.

The basic formula is:

Dividend Yield = Annual Dividend Per share ÷ Share Price x 100

Example

Annual Dividend = ₹ per share

Share price =₹100

Tehre fore:

₹5 ÷ ₹100 x 100 = 5%

Dividend Yield = 5%

Dividend yield can change when the share price changes, even if the company dividend amount remains the same.

Simple Dividend Yield Example

Imagine Company A pays:

₹8 annual dividend per share

Its current share price is:

₹200

Dividend yield:

₹8 ÷ ₹200 × 100 = 4%

So the dividend yield is:

4%

But remember that dividend yield is based on the share price and dividend amount; it should not be interpreted as a guaranteed future return.

Dividend vs. Capital Appreciation

There are two different ways shareholders may potentially benfits from owning Stocks.

Dividend

Money distributed by the company to eligible shareholders.

Capital Appreciation

An icnrease in the market price of the shares.

Example:

But a share ₹100

Later sell at ₹140

The increase of ₹40 represent a ptoential cpaital gain if you sell at that price, before cosndiering taxes and transaction costs.

If tyhe company also pay dividend you may recieve noth:

Dividend + Potential Capital Appreciation

Neithe is guaranteed..

Dividend vs. Interest

Dividend and Interest are also different.

DividendInterest
Paid by a company to eligible shareholdersPaid according to a debt, deposit, or lending arrangement
Linked to share ownershipLinked to deposited or borrowed money, depending on the arrangement
Usually not guaranteedTerms depend on the financial product
Amount can changeRate may be fixed or variable depending on the product
Company decides according to applicable rulesUsually determined by the agreement/product terms

What Is a Dividend-Paying Stock?

A dividend paying stock is a company’s stock whose shareholders recieve divdiend when the company decalres and distributes them.

Some companies have along history of paying dividends.

Other may pay occasionally.

And some companies nolt pay any Kind of dividends at all.

Simple looking for whether a copmpany pay dividends is not enough to udnerstand whether the stock suitable for a particular investor.

Are Dividends Guaranteed?

No.

A company can change, rduce, suspend or stop its divdiend depending on its circumstances and applicbale rules.

Even long histoires f dividend company can change their policies.

This is why investor should not assume:

“The company paid a dividend last year, so it must pay th same divdind last year.”

Dividend are not guaranteed returns.

What Is a Divdiend Payout Ratio?

The dividend payout ratio indicates how much of a company’s earning are distributed as dividends.

A simple formula:

Dividend Payout Ratio = Dividends ÷ Earning x 100

Example

Company earning =₹100 crore

Dividend = ₹40 crore

Payout ratio

₹40 crore ÷ ₹100 crore x 100 = 40%

The interpretation of this ratioo depends on the company’s industry, fiancial position, accounting results and ther results.

Why Do Some Companies Not Pay Dividends?

There are several reasons.

A company may prefer to use its money for:

  • Business expansion
  • Research and development
  • New products
  • Acquistions
  • Debt reduction
  • working capital

Example:

A young companies with many growth opportunities ma choose to reinevst its earning isnted of sistributing them.

That doesn’t automatically means company is good or worse; its refects how the company chooses to alloacate capital.

What Should You Check Before Investing in Dividend Stocks?

If you are lookin for dividends paying compaqnies don’t look just on dividend pay out:

1. Dividend History

Has the company paids dividends consistently?

2. Profitability

Does the business generate sustainable profits?

3. Cash Flow

Does the company genrate enough Cash to support its operations and distributions?

4. debts

How much debt does the company have?

5. Payout Ratio

How muchof its earning is being Distributed?

6. Business Growth

Is the underlying business grwoing, stable or declining?

7. Dividend Yield

Is the yield reasonable relative to the company’s Circumstances.

A very highly divdiend yield should not automatically be cosndiered attractive because a falling share price can make yield appear unusually high.

Common Dividend Mistakes Beginners Make

1. Thinking Dividends Are Free Money

A divdiend is a distrbution asociated with owning shares. it isn’t free money separate from the ecnomics of the investment.

2. Looking Only at Dividend Yield

A high yield does not automatically mean a better insvestment.

3. Assuming Dividends Are Guaranteed

Companies can reduced or stop dividends.

4. Lgnoring The business

A divdiend should bot be only thing you research.

5. Forgetting Taxes

Divdiend income may ahve tax implications dpending on your country and circumstances.

Why Dividends Matter to Investors?

Dividends can be used for investors who want to understand how companies distribute cash to share holders.

They can poitentially provide:

  • An additional income of investment income
  • Cahs distributions
  • A way to paryicipate in company profits
  • Another companonets of total investment returns

Investors should consider divdiend alongside the company’s overall financial health, valuation, growth risks, and thier own goals.

FAQs

What is a divdiend in simple words?

A dividend is a payment thaat a company may distribute to its shareholder, often from its profits or accumulated earnings.

How do Dividend Work?

A company decides to distribute a divdiend, announces the relvent terms and dates and eligible shareholders recieve the declared amount according to those terms.

Do all Companies pays dividends?

No. some companies pays dividends,whle others reinevst their earnings into the business.

How is a dividend calculated?

Simple calculation

Dividend Recieved = Number of shares x Divdiend Per share

Example

100 shares x ₹5 dividend =₹500 before applicable taxes

What is dividend yield?

Dividend yield shows the annual dividend relative to the current share price.

The basic formula is:

Dividend Yield = Annual Dividend Per share ÷ Share Price x 100

Are dividends guaranteed?

No.

A company can change, rduce, suspend or stop its divdiend depending on its circumstances and applicable rules.

What is cash dividend?

A cash divdiend is a dividend paid in money to eligble shareholders.

Link this article to:

What Is an Asset? A Simple Guide to Things That Have Financial Value

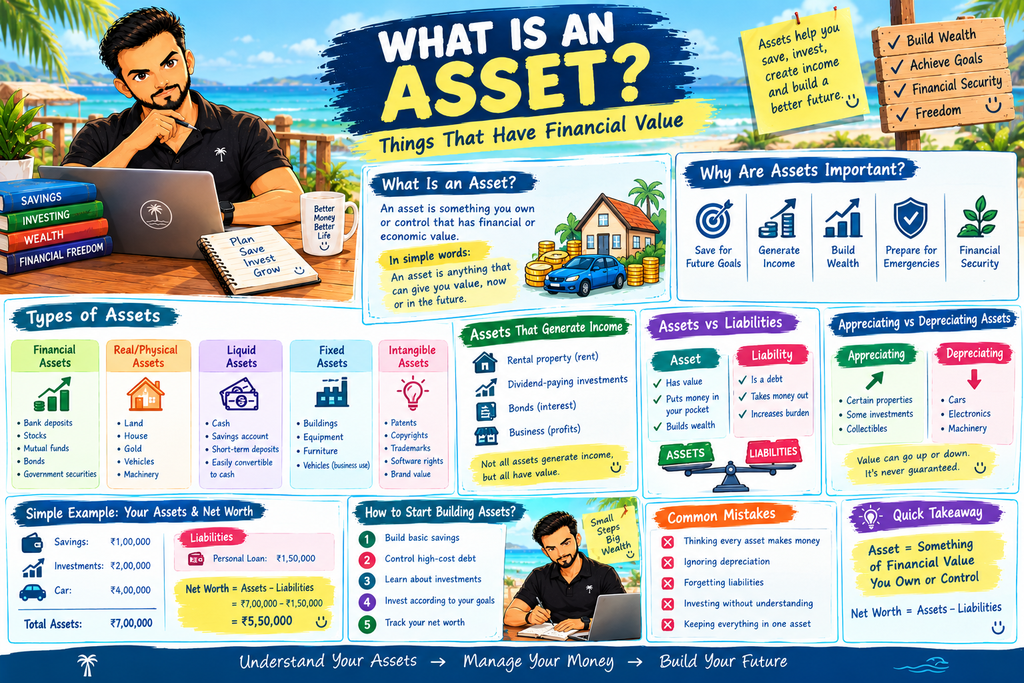
What Is an Asset?

When you start learning about personal finance, you will often hear the word Asset.

But what exactly it’s mean?

In simple Terms:

An asset is something you own or control that has financial or economic value.

Assets include money in your bank account, investment, property, vhicles, valuable items and certian business resources.

Example:

  • Money in your bank account
  • Stocks
  • Mutual Fund
  • Gold
  • A house
  • Land
  • A business
  • Certain Valuable Equipments
  • Valuable or rare Arts

All of these can be considered assets because they have economic value.

Wht are Assets Important?

Assets is very important part of your fiancial Position.

Let say you have:

  • ₹ 2,00,000 in Investment accounts
  • ₹ 1,00,000 in saving account
  • ₹ 3,00,000 of car value

Thes things represents your own value.

Building assets can help you:

  • Generate Income
  • Buld Wealth
  • Be prepare for emergencies
  • Icnrease Financial stability
  • Save for future goals
  • Create long term financial independence

Not every assets produces income and the value of assets rise or fall.

Different Types of Assets

Assets can be classified in different ways depending on their purpose and accounting treatment.

For Beginners, it is useful to understand the following Broad categories.

1. Financial Assets

Financial aassets are assets that reprents financial value or financial claim.

Example:

  • Bank deposits
  • Stocks
  • Bonds
  • Mtual Fund Invetments
  • Certain govermnet securities

For Example, If you own ₹75,000 worth od invesment, those are part of Financial Assets.

2. Physical or Real Estate

These things are physical existence and ecnomic value.

Examples:

  • Lands
  • Houses
  • Gold Vehilces
  • Machinery
  • Equipment

A house is physical asset value that may have significant fiancial value.

3. Liquid Assets

A Liquid assets is an assets that convert into cash without quickly losing its value.

Example

  • Cash
  • Bank Deposits
  • Highly traded investments

Liquidity are important because you may need accessible money for emergencies and short term expenses.

4. Fixed assets

Fixed assets are generally long term physical assets used by business.

Example:

  • Building
  • Machinery
  • Equipment
  • Furniture
  • Vehicles used for business

These assets are generally used for long term business and it not for resale.

5. Intangible assets

Not all assets are physical.

An intangible asset has value but you cannot Physically touched.

Examples

  • Patents
  • Copyrights
  • Trademarks
  • Certain software rights
  • Brans related intellectual property

These types of aassets are very importane modern day business.

Assets that generate Income

Some assets can generates income.

Example:

Rental Property

A property may generates rental incomes.

Dividends related investments

Certain investment provide dividends monthy.

Bonds

Some Bonds provides interest according to their terms.

Business

Abusiness can generate profits.

These are called income -producing assets.

Income are not guaranteed and value or perfoemence od an assets can changes.

Assets That Do Not Generate Regular Income

Some assets may have financial valuw withou producing regular income. Example:

Gold

Gold can have significant market value, bit simply owning in physical gols does not produce monthy income.

Simliarly, a personal use vehicle may be valuable but generally doesn’t valuables unless you use in monthy incomes ghenerate activity.

This is why is useful to difference between:

An asset that value and an assets that generates incomes.

Thet are not necessarily same thing.

Asset vs. Liability

One of the most important concepts in personal finace is understanding the difference between assets and liabilities.

Assets

An assetsis something you own or control that has financial or economic value.

Liability

A liability is an obligation or debt uou owe.

Example:

AssetLiability
Money in bankCredit card debt
StocksPersonal loan
GoldOutstanding loan
PropertyHome loan
Business assetsBusiness debt

Underatsnding both sides give you a better picturte of your financial position.

Simple Example of Assets and Liabilities

Imagine you own:

Savings: ₹1,00,000
Investments: ₹2,00,000
Car: ₹4,00,000

Your total assets would be:

₹7,00,000

Now imagine you also have:

Personal loan: ₹1,50,000

Your liabilities would be:

₹1,50,000

A simplified calculation of your net worth would be:

Net Worth = Assets − Liabilities

₹7,00,000 − ₹1,50,000 = ₹5,50,000

This is a simplified example, but it shows why both assets and liabilities matter.

Assets and Net Worth

Your net Worth gives you idea of tour overall financial position.

Basic formula is:

Net Worth = Total Assets – Total Liabilities

Example:

Total Assets = ₹10 lakhs

Total Liabilties = ₹ 5 lakhs

Net Worth = ₹10 lakh – ₹5 lakh = ₹5lakh

As your financial life devlops, tracking your assets and liabiltities can help you to understand whether your financial position is improvng or not.

Good Assets vs. Bad Assets?

“GOOd assets make you money and bad money costs you money.“

This can be simple idea, but real life more complicated.

An asset can have value without genrating income.

Example:

A family home can provide you provide to live even though it is not genrating rental income.

A car can provide transportation nut usually loses it values over time.

Insted of saying “good” or “Bad” ask:

  • Does it have value?
  • Does it genrate income?
  • It is decresing or increasing in value?
  • How easily to seet it?
  • Does it support ot my financial goals?

Appreciating vs. Depreciating Assets

Some assets may increase in valye, whule may lose in value.

Appreicating Assets

These are may increase market value may increases over time.

Example:

  • Properties
  • Some invetsments
  • Certain Collectibles

But appreciation never guaranteed.

Depreciating Assets

These are assets that generally lose value over time.

Example:

  • Cars
  • Motocycles
  • Electronics
  • Some not in use machinery

Example

Car ism worth 10lakhs in new showrooms at time of purchased, but after some time goes gradually get depreicating in value over time.

Why Should You Build Assets?

Building Assets can be important part of long term financial planning goals.

Instead of using all your income in consumption or unnecessary expenses, you can allocate in assets building option for long term for your goals.

Example:

Income ⇒ Expenses ⇒ Savings ⇒ Investments ⇒ Assets

Over period of time, your collection of financial and physical assets can be come an important part of your financial journey.

How Can a Beginner Start Building Assets?

Your don’t need big amount of money to start learning about assets building.

Step 1: Build Basic savings

Start by keeping some money avaiable for emergencies and short term goals.

Step 2: Control high-cost debt

Understand your existing debts and their costs.

Step 3: Learn abou Investments

Learn the basic of investment option before putting money into them.

Step 4: Investing According to Your Goals

Your Invetsments should your match:

  • Time horizon
  • Risk tolerence
  • Financial Goals
  • Available money

Step 5: Track your Net Worth

Periodically calculate :

Assets – Liabilities = Net Worth

This help you saee your financial Progress.

Common Mistakes About Assets

Mistake 1: Thinking Every Asset Makes Money

Some assets have value but doen’t generate regular income.

Mistake 2: Ignoring Depreciation

Cars, Electronic and other physical items can lose value over time.

Mistake 3: Forgettinmg Liabilities

Owing valuable things doent’ necesaarily mean you are weathy if you also have large debts.

Mistake 4: Investing Without Understanding

An Asset value can rise or fall. Always understand what you are buying.

Mistake 5: Keeping Everything in Onje asset

Depending too heavily on one type of asset can create concentration risk.

FAQs

What is an asset in simple words?

An asset is something you own or control that has financial or economic value.

What are examples of assets?

Example: Cash, bank deposits, stocks, mutual funds, gold, property, vehicles, businesses and certain intelluctual property.

Is money in a bank account an asset?

Yes. money you have in bank account is generally considered a fiancial asset.

Is car an asset?

Yes. A car has fiancial value and can therefore be considered an asset. vehicle get commonly depreicate over time.

Is a house an asset?

Yes. A house you own is generally considered a physicl asset and has financial value.

What is the diffwerence between an assets and liability?

An assetsis something you own or control that has financial or economic value, A liability is an obligation or debt you owe.

What is net worth?

Net worth is th value of your assets after subracting your liabilities.

Net Worth = Assets – Liabilities

Some bank allow permature closure, but reduced interest, penalties or other indcidual circumstances.

Link this article to:

What Is a Recurring Deposit (RD)? — Saving a fixed amount every month

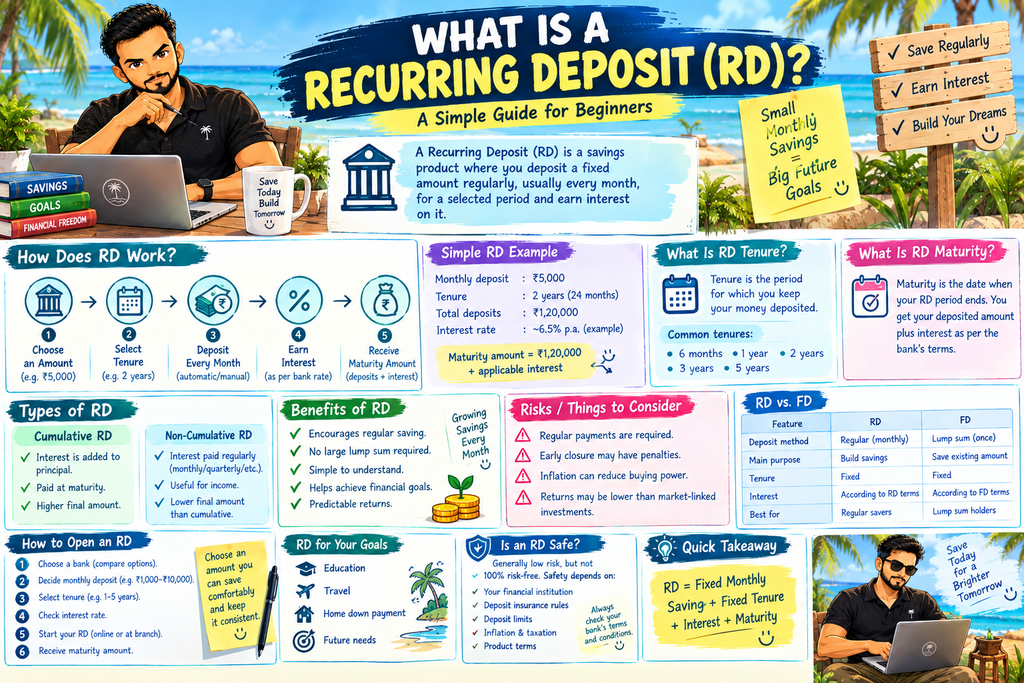
What Is a Recurring Deposit (RD)?

A Reccuring Deposit (RD) is a saving product that allows you to deposit a fixed amount of money regularly, generally month, for the selceted period.

In simple Word,

A RD is a savings by putting aside a fixed amount of money for regularly month and earn interest on its deposits.

Example:

Instead of investing lumpsum of ₹60,000 at once within period

₹5,000 every month regularly for 12 months.

Ar the end of a RD temure, you generally recieved your deposited money and applicable interest on it.

How Does a Recurring Deposit Work?

An RD works through regular invested.

The Bsic Process is:

Choose monthy Payment – Choose Tenure – Deposit every month – Earn Interest – Receive MAturity Amount.

Example

  • Monthy Deposit:₹5,000
  • Tenure: 3 Year
  • Total Deposits: ₹5,000 X 36 months = ₹1,80,000

The final Maturity amount would inlcude applicable interest as per agreed.

The exact maturity amount depends on the interest rate, compound interest mehtod, tenure, and bank’ Rd Terms.

How to Open an RD?

Open an Rd is simple Process and some simlar to FD:

Step 1: Choose a Bank

Compare a Rd option avilable from our bank or other eligible financial institutions.

Step 2: Decide Your Monthy Deposit

Choose the amount that you can comfortably save every month.

Example

₹1,000, ₹4,000, ₹5,000, ₹10,000 per month

The minimum amount depend on the various institutuions.

Step 3: Select the Tenure

Choose hwo long you want to keep continue in deposit.

Available tenure vary on banks.

Step 4: Check the Interest Rate

Look at the applicable interest rate and choose your as your tenure.

Step 5: Start Your RD

Ste up recurring seposit and make a required monthy payment.

Step 6: Receive the Maturity Amount

Once the RD reached maturity, you generally recieve your deposits plus applicable Interest.

Why Do People Use Recurring Deposits?

An RD cn be useful for people who want to develop a regular saving habits.

Inbsted waiting until you have lumpsum of that amount, you can save smaller amount for every month.

Example:

₹3,000 per month

may feel and confident this amount easier to save this amount of money.

₹60,000

This makes an RD paryiculary easy to understand for beginners.

What Is a Tenure?

Tenure means the length of time for which you make youir recurring deposits.

Example, an Tenure could have tenure of:

  • 6 Months
  • 1 Year
  • 2 Year
  • 4 Year
  • 3 Year
  • 5 year

The avialable tenure dpenod on your bank or financial Institutions.

Choose your tenure as per your financial goals and when you expect to need this money.

What Is RD Maturity?

MNAturity is date when your selected RD Period ends.

Example:

You genreally make the required monthy deposits throughout the selected period.

At maturity, you recieve the accumlated deposits and applicable inetrest according to the RD Terms.

RD vs. FD: What Is the Difference?

Both RD and Fd are deposits savings but work differently

FeatureRecurring Deposit (RD)Fixed Deposit (FD)
Deposit methodRegular depositsUsually one lump-sum deposit
Example₹5,000 every month₹1,20,000 once
Main purposeBuild savings graduallySave an existing lump sum
Regular saving requiredYesNo
TenureFixedFixed
InterestAccording to RD termsAccording to FD terms
Suitable forPeople saving monthlyPeople with a lump sum

Sumple Difference:

RD = save fixed amount every month regualrly

FD = Depositsa Lumpsum for fixed Period

Rd vs. Savings Accounts

A Saving and RD serve diffrently.

FeatureSavings AccountRecurring Deposit
Main purposeEveryday banking & savingRegular planned saving
Access to moneyGenerally easyConditions may apply
Fixed tenureNoYes
Regular depositNot requiredRequired
InterestAccording to account termsAccording to RD terms
Best suited forEveryday money & liquidityGoal-based regular saving

Benefits of a Recurring Deposits

1. Encourages Regular Saving

You commit to saving a fixed a amount every month.

2. No Large Lump Sump Required

You don’t necessarily need a large amount of money to get started.

3. Simple to Understand

The Basic Concept:

Deposited every month – Earn Interest – Receive Maturity amount.

4. Helps With Fiancial Goals

An RD can be used for planned expenses such as:

  • Education
  • Travel
  • A future Purchases
  • Annual Expenses
  • Short or medium terms goals

5. Predictable Structure

You know hoe much you are expected to deposited each month and the slected tenure.

What Are the Dis advantages of an RD?

An RD also has Limitations.

1. Regular Payments Are required

You need amaintain enough money in your account ot make the schedule deposits.

2. Early closure may have conditions

If you closure the RD before maturity the bank may appl specfic rules or reduces the interest payables.

3. Inflation Can reduce Purchasing power

If inflation is higher than your effective returns, your money may lose purchasing power over time.

What Happens If You Miss an RD payment?

If you don’t have enough money in your account when the monthy installment is due, the bank may apply its applicable rules:

Possible cosmeueences can include:

  • A late peyments penatly
  • Additional Charges
  • Changes to the account status
  • Resitrictiopn or closure after on other miss payment

The exact cosnequreneces dpend on the bank term and rules.

Can You Withdraw an RD Before Maturity?

Soem banks allow premature closure of an Rd, but the codntions vary.

You may receive:

  • A different applicable interest rate
  • Reduced interest
  • A pently or adjustment
  • other applicable charges

Before opening an RD check the Bank’s rules regarding premature charges.

Is an RD Suitable for Beginners?

An RD can be easy for bignners to understand because it creates an simplke saving routine.

Example:

Monthy income – set aside ₹3,000 – RD – continue Every month

Before staring one, make sure uou have enough money available for:

  • Everyday Expenses
  • Emeregency Needs
  • Existing Financial Commitments

How Much Should You Save in an RD?

There is no single amount for everyone.

A simple starting point it top choose a amount easily can save and invest regualry without pressure on your monthy budget.

If your monthy budget allow you to comfortably save ₹3,000 uou might cosnider your amount of Rd nearer to it.

The goals is to consistency.

RD for Financial Goal

Let say you want a plan vacation 2 year from now.

You estimated around that you needed:

₹1,20,000

Insted of finding lumpsum of ₹1,20,000 immediately, you could create a regular saving plans.

Example:

₹5,000 x 24 month =₹1,20,000

Any applicable ineterest may apply as per FD terms.

This make how regularly monthy saving can make larger financial goals easier to approach.

Is an RD Risk-Free?

It is beeter not to describe any fiancial product simply as “100% risk free.”

Factor such as:

  • Financial institutions
  • Applicable deposist isnurance
  • Deposits limits
  • Prduct tems
  • Inflation
  • Taxation

If you decide that deposits latger amount read the terms before putting larger sum of money protection and bank or instituions rules.

Things to Check Before Opening an RD?

Before Opening RD, compare more than the interest rate.

Check:

1. Interest Rate

Compare the rate offeres to your desried value.

2. Tenure

Choose your period that matches your financial goals.

3. Maturity Amount

Check how much you got at the time of maturity.

4. Premature Withdrawal Rules

Understand what happen when you needed your early.

5. Payout Option

Check whethewr interest is paid periodically or at maturity.

6. Tax Treatment

Udnerstand how the interest wiil be treated udner applicable tax rules.

7. Deposit Protection

Check the aplicable deposit isnurance coverage and limits.

8. Monthy Deposits

Make sure the amount fits comfortably into your budgets.

FAQs

What is a Recurring Deposit?

A RD is a savings by putting aside a fixed amount of money for regularly month and earn interest on its deposits.

What Does RD Stand For?

Rd stands for Recurring Deposit.

How Does an RD work?

You choose a monthy deposit amount and tenure, make rgular dpeosits and ecirve the accumlated deposits plus applicable insterest.

What is the difference between FD and RD?

An RD involves monthy deposits and Fd is lumpum amount of money once for a fixed period.

Can I Start and RD with a small Amount?

Many banks offers RDs with retatively small minums monthy deposits but the exact minumum varies by insitutions.

What happen if I miss and RD payments?

You bank charge a pently or apply other conditons. The Exact cosnequeences dp[ends on th bank’s RD rules.

Can I Withdraw an RD before maturity?

Some bank allow permature closure, but reduced interest, penalties or other indcidual circumstances.

Link this article to:

What Is a Fixed Deposit (FD)? A Simple Guide for Beginners

What Is a Fixed Deposit (FD)?

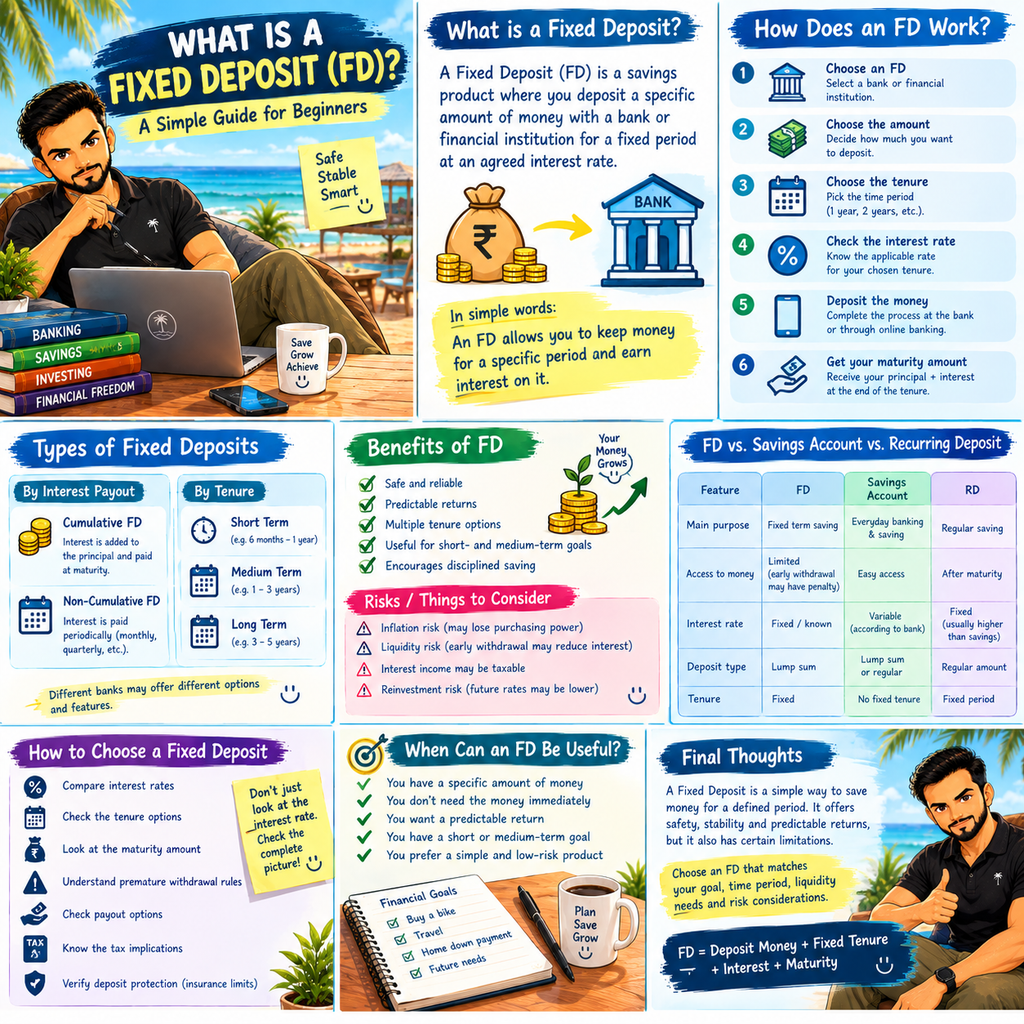
A Fixed Deposit (FD) is a savings product where you deposits a specfic amount of money with a bank or financial institutions for a fixed period at agreed interest rate.

In simple Words:

A fixed deposits allows you to keep money for specfic period and earn interest according to the FD terms.

Unlike a saving account, whereyou can access your money whenever you need it, an FD is designed for specfic period.

Example

You might deposit ₹1,00,000 for 3 years.

The bank pay you fixed interest rate in that tenure will added into account of FD. At the maturity time, all the orginal deposits and applicable interest with taxes, deduction and agreed terms combined comes to your bank saving accounts.

How Does A Fxed Deposit Work?

The process is retatively simple.

Step 1: Choose an FD

You select a bank or eligable financial istitution and review its avauilable FD options.

Step 2: Choose your Deposit Amount

Example:

₹1,50,000 for 3 years

Step 3: Choose your Tenure

You select how long you want to keep your money into deposits accounts

Example

1 year, 2 year, 3 year, 4 year and goes on.

Step 4 : Check your Interest Rate

The financial institutions provides an interst rate for slected tenure and FD.

Step 5: Deposit your money

You pace your money into your FD.

Step 6: Wait Untill Maturity

The deposit will mature which you slected your tenure and FD agreed terms. Till ten you have to wait till maturity period or tenure gets completes as agreed in FD Terms.

Step 7: Receive the matuirty Amount

At Maturity, you receive the deposit plus applicable deposit, subject to prdouct term’s.

What Is FD Interest?

FD interest is th amount the bank or fiancial insitutions pays you for keeping your money deposited for the agreed period.

Example:

Deposit:₹1,50,000

Insterest rate: 7% for a year

The interest calculate according to the FD term’s.

Some deposits may offers compound interest, whilew others may offers periodic interest payout.

Check the actuall total maturity amount and pay structure.

What Is FD Tenure?

Tenure means the length of uour deposits how much long you can keep your deposits in the FD.

Example:

  • 6 months
  • 1 year
  • 2 year
  • 4 year
  • 3 year
  • 10 years

Teh available option depends on the bank or financial istitutions.

you should choose your tenure according to your need, when i need this money.

If you need very soon, ther may deduction + charge for per matuirty to witdraw your money earlier. choose your tenure wisley your tenure.

What Is FD Maturity?

Maturity is the date on which the agreed Fd tenure ends.

Example:

If you open in 1st january 2026 tenure for 2 years.

the maturity date will be 1st january 2027

At maturity the deposits can genrally be apis according to the terms.

Dpedning on the product, you may have options such as:

  • Renew your FD
  • Total maturity amount to recieved
  • Recive month to month od quartarly if you agree

Always check bank specfic terms.

What Happens If You Withdraw an FD Early?

Sometime somthing happen in life you required sudden money for emergency. So required Fd before matuirty.

Thos is called Permature Withdrawal.

Dpending on your bank and terms of FD, Premature may results into:

  • A lower applicable interest rate
  • A penatly
  • Reduce earing interest
  • Other applicable conditions

Before opening your FD, understand the premature withdrawal rules.

Cumulative vs. Non-cumulative FD

Fixed deposits can have different payout stuctures.

Cumulative FD:

Cumulative FD, interest is generally accumalated and paid along with priccipal at maturity.

This can be useful if you wanted total money in pay to help in your achieve goal of purchases.

Non-Cumulative FD:

Witha Non-cmumulative Fd, you get interest and principal amount in periodically payout structure:

Example:

  • Monthy
  • Yearly
  • Quartarly
  • Half yearly

Teh avaiulable payout vary Fd terms and Conditions with BAd or financial Institutions.

FD vs. Savings Account

Both can be used witha bank, but they serve differently purposes.

FeatureSavings AccountFixed Deposit
Main purposeEveryday saving & bankingFixed-term saving
Access to moneyGenerally easierMay have restrictions
InterestUsually variable according to account termsFixed/known according to FD terms
TenureNo fixed maturityFixed tenure
Premature withdrawalUsually not applicable in the same wayConditions may apply
Suitable forEmergency & everyday fundsMoney you may not need immediately

FD vs. Recurring Deposit

A Fixed deposits and Recurring deposits(RD) are both savings products, but they work differently.

Fixed Deposit

You genraslly deposit a lump sum once.

Example:

₹1,00,00 → FD

Recurring Deposit

You generally deposit a fixed amount regularly.

Example:

₹3,000 every month → RD

FD = Lump sum deposit

RD = Regular deposits

Benefits of Fixed Deposits

1. Simple to Understand

FDs are retatively very simple and straightforward in terms to invest and returns and compared with other investment products.

2. Predictable Returns

For Fixed-rate FD, the interest rate is generally known when you open the deposit, subject to the products terms.

3. Diffferent Tenures

You had different time period of investment options.

4. Useful for short or Medium Term Goals

An FD may be considered for money you expect to need for specfic time period.

5. Can Encourage Disciplined Saving

Because the money is placed for a defined period, it may reduce your immediately spending.

What Are the Risks of an FD?

Athough it is alow risk than a larket linked investment,there are not competely withut cosnerations.

1. Inflation Risk

If the FD’s after tax return is lower than inflation, your money may lose purchasing power over time.

Example:

If your FD earn 6% but inflation is 7% your money is growing in niminal terms but losing Purchasing power over time.

2. Liquidity Risk

You may need to pay a penatly or charges if you withdrwal the money premature.

3. Tax

Inetrest earned on FD may be Taxable according to applicable tax rules.

4. Reinvestment Risk

When you mature Fd, Next FD may be diffrent interest rate.

Is an FD Completely Risk-Free?

It is never be risk free or any other investment products.

It can be minimum risk but never be Risk free investment.

Factors scuh as:

  • The Financial Insituations
  • Applicable deposits insurance
  • Deposits limits
  • Pemature charges and penatlies
  • Tax rules
  • Inflation
  • Terms and conditions

Before putting larger amount of money deposits check your terms and safety to secure your investment before misfortune happens.

Should You Put Your Emergency Fund in an FD?

An emergency fund should be easily accessible at any time.

Because premature withdrawal may have charges or involves conditions ot reduced interest, you do not want your emrgencies fund lock gor long term.

A possible approcah should highly accessible with same day payout with very low deduction and taxes also nominal.

Your fiancial situation and conditions defines your approach.

How to Choose a Fixed Deposit?

Before Opening FD, compare more than the interest rate.

Check:

1. Interest Rate

Compare the rate offeres to your desried value.

2. Tenure

Choose your period that matches your financial goals.

3. Maturity Amount

Check how much you got at the time of maturity.

4. Premature Withdrawal Rules

Understand what happen when you needed your early.

5. Payout Option

Check whethewr interest is paid periodically or at maturity.

6. Tax Treatment

Udnerstand how the interest wiil be treated udner applicable tax rules.

7. Deposit Protection

Check the aplicable deposit isnurance coverage and limits.

Whan Can an FD Be USeful?

An FD may cosnsidered when you:

  • Have specfic amount of money
  • Knwo your won’t money immediately
  • Have a short and medium term financial goals
  • Pefer simple Saving product

You Might compare an FD with ther suitable saving or investment option based on:

Safety +Liquidity + Return + Tax + Time horizon

FAQs

What is a Fixed Deposit?

A Fixed Deposit (FD) is a savings product where you deposits a specfic amount of money with a bank or financial institutions for a fixed period at agreed interest rate.

What does FD stand For?

FD stand for Fixed Deposit.

How does an FD Work?

You choose to deposit specfic amount, choose the tenure and earn interest according to your FD’s terms. At maturity, you generally recieve the principal plus Applicable interest.

Can I with draw my FD before Matuirty.

Many FD allows you to premature withdrawal but odnitions, penalties or rduced interest rate may apply. Check your bank’s terms before with drawing.

Is FD interest Taxable?

FD interest may be taxable dpending on your indivdual income tax slab and applicable tax rules.

What is FD Maturity?

Maturity is the date when the Selected FD Tenure ends and deposits become payable according to your bank term’s.

What is the difference between Cumulative and non-cumulative FD?

With cumulative FD, Interest is generally accumalated and paid along with priccipal at maturity.Witha Non-cmumulative FD, you get interest and principal amount in periodically payout structure.

For Standard bank account UPI payment, you generally required to registration details.

Link this article to:

What Is a UPI Payment ? — How digital payments work

What Is a UPI Payment?

Today Time, you can pay for groceries, ffod, shopping, bills and even small everyday purchases using your smartphones.

One of the most popular digital payment method in Indiia is UPI.

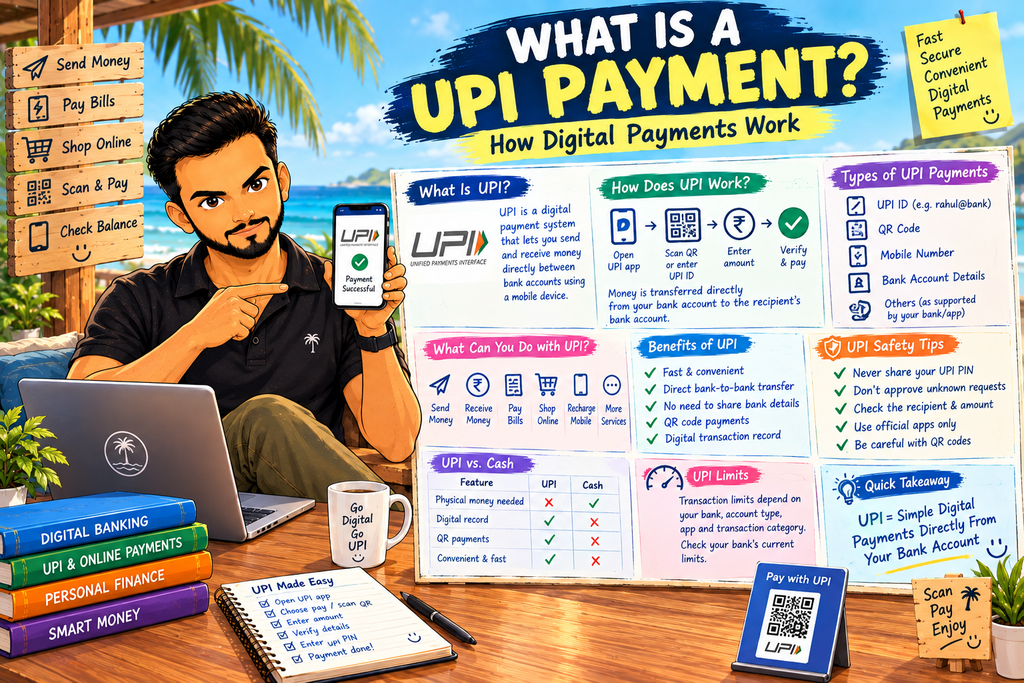
UPI stands for Unified Payments Interface.

In simple words:

UPI is digital payment system allows people to send and receive directly between bank accounts using mobile devices.

Instaed of using cash or entering long banka ccount details every tansaction, uou often make a payment using UPI ID, OR code, Mobile Number or other supported payment method.

How Does UPI Work?

IPI connect your bank account link with aUPI- enabled application.

When you make apayment the system securely communications with the relvent banks and payment infrsastructure to process the transaction.

A simple UPI payment can process like:

Open UPI app ➔ Scan OR Code ➔ Enter Amount ➔ Verify payment ➔ Money Transferred

The money genrally tansfer directly from linked ban k to receiver bank account.

You don’t need normally needed manually enter receiver account number and other details for every UPI transaction.

What Is a UPI ID?

A UPI ID, also known as Virtual Payment Address(VPA), is an address used to send and rcieve money through UPI.

It genrally look like:

Username@bankname

Example:

Princekumar@bank

The exact format may be difference on thr UPI app and bank.

A UPI ID makes easier to receive money without sharing your bank accounts details for every transactions.

What Is a UPI QR Code?

A UPI QR Code is sacannable code that can obtain reciever’s payment details.

You may see QR code at:

  • Showrroms
  • SHopping malls
  • Restaurants
  • Petrol Stations
  • Online stores
  • Service providers

To make payment, you just need to open supported UPI apps, scan the QR Code, enter the amount if required and authorize by set pin and payment is done.

This makes UPI payment faster and easier.

How to Make a UPI Payment?

The general apps process is simple.

Step 1: Open your UPI Apps

Open a UPI supported Apps on your smart phones.

Step 2: Choose the payment Option

You may choose an option such as:

Pay ➔ OR code ➔ send money

Step 3: Select the receiever

You can often pay using:

  • UPI ID
  • QR Code
  • Mobile Number
  • Bank Account details
  • Other supported options

Step 4: Enter the amount

Enter the amount you want to send

Example:

₹500

Step 5: Check the Reciever

Check the name and details of reciever displays on your UPI Apps on it.

Step 6: Authorize the payment

You mau need authorize by UPI PIN for transaction.

Step 7: Payment Confirmation

After successful transaction the pps genrally show transaction details on confirmation page or message.

What Is UPI PIN?

A UPI PIN is Personal authenication number is used to authorize UPI Transaction from your bank account.

It is extremely important to keep your UPI PIN private.

Nevr share your UPI PIN With:

  • Friends
  • Strangers
  • Shopkeepers
  • Customer Care Services
  • Anyone claiming ther are from your bank

Your bank or legitmate payment provider should not required to reveala your UPI PIN to recieve money.

Sending Money vs. Receiving Money

One improtant thing to understand about UPI is the difference between sender and receiver money

When you send Money

You authorize a transactionm to transfer money from your lonked bank account.

You generally needa authenticate the payment.

When you Receive Money

Some one ealse send money through UPI Id , qr code or other payment method .

Your genreally do not need UPI PIN to recieve money from others.

What Can You Pay for Using UPI?

UPi can be based for many everyday transaction, depending on the merchant and service provider.

Example:

  • Restaurants bills
  • Grocery Purchases
  • Online Shopping
  • Utility bills
  • Mobile recharges
  • Travels payment
  • Small business payments
  • Person to person transfers

Teh Availability of specfic services can vary.

Benefits of UPI Payments

1. Fast Payments

UPI enables elctronic money transfers without needing to handle phsical cash.

2. Convenient

You can make using your smartphones

3. Direct Bank-to-bank Transfer

UPI transaction can trasnfer money directly to Linked bank to bank accounts.

4. QR Code Payments

You can oftern scan QR code send money to others.

5. No Needs to Remember Bank Details

For many transaction, a UPI ID or QR can be used isntead of manually entering full bank details.

6. Digital Record

Transactions are generally recorded electronically, making it easier to review your payment history.

UPI vs. Cash

FeatureUPICash
Physical money requiredNoYes
Smartphone usually neededYesNo
Digital transaction recordYesUsually no
QR paymentsYesNo
Person-to-person transferYesYes
Risk of physical lossLowerHigher
Internet/network dependencyUsually requiredNo

UPI vs. Debit Card

UPI and Debit Cards both allow digital payment, but they work didfernetly.

UPI

Money is transfer directly from your linked bank account after you authorize the transaction.

Debit Card

A Debit Cards can be used at supported merchants and ATMs, with the transaction linked to your bank account.

UPI is particular canvenient fpor QR code payments and perosn to person payments.

Are UPI Payments Safe?

UPI uses multiple security mechanisms, but usrs stil have to careful.

Most UPI related frauds often involve social engineering or tricking users into authorizing a transaction, rather than simply someone knowing your UPI ID.

Follow these basic rules:

Never share Your UPI ID

Your UPI PIN should remain private.

Don’t approve Unknown Collect Requests

IF you recieve a payment request from someone you don’t recongize, don’t recongize it withut verifythe reson.

Check the Recipient

Bedore competing your transaction or Enter UPI PIN, verify reciever name and UPI ID and main check your enter amount.

Don’t Install Unknown Apps

Someone claiming to be customer support may ask you to install a remot access application. avoid doing this unless you are certain about the source.

Be careful With QR Codes

Scaning a Qr code can initiate a payment process. Scaning a Qr code does not mean you will recive money.

Use Official Apps

Download bank Official bank app to payment and net banking keep them updated tiem to time.

Do You Need a Bank Account for UPI?

For Standard bank account UPI payment, you generally required:

  • A bank account
  • A supported mobile number linked as required by the bank
  • A UPI enabled applcation or banking services
  • A supported debit card or other required steup information for registration, depending on the bank

The eaxct requirements can vary between bank and UPI services.

What Happens If a UPI Payment Fails?

Sometimes a UPI transaction may fail because of:

  • Bank server issues
  • Networks problem(Apps run on internet)
  • Incorrect payments details
  • Bank account restrictions
  • Transaction limits
  • Tecahanicla problems

If money is debited but recipemnt does not recieve it, check the transaction history in your UPI apps status in your UPI app and bank account.

It the issue is not reslove automatically, use the apps or bank’s official support or dispute resolution process.

Keep the tansaction eference number , its help you to report a problems easily.

Are There Limits on UPI Payments?

UPI Tansaction can be subjects to limits.

Thes may depnds on:

  • Types of transaction
  • Your bank
  • Your account
  • UPI transaction
  • Transaction catgeory and limits
  • Applicables rules

Dosen’t assume that every transaction or UPI apps has exactly same transaction limits.

For large or unsual transacton payments, check the current limits provided by your bank or payment srvices.

UPI and Personal Finance

UPI makes Spending conenient, but convenience can also make it easier to spend without thinking.

Example:

Paying ₹100 digitally may feel very lees unnoticable than handling an ₹100.

This is why tracking your spendings must be nowadays.

Categories them into:

  • Food
  • Shopping
  • Transport
  • Bills
  • Tavels
  • Entertainments
  • Savings

Digital is useful, but good money habits stills matters.

Some ATMs supports cash deposits, while other only provide with drawals and basic account services.

FAQs

What is UPI in Simple Words?

UPI is digital payment system allows people to send and receive directly between bank accounts using mobile devices.

What is the full form of UPI?

UPI stands for Unified Payments Interface.

What is a UPI ID?

A UPI ID, also known as Virtual Payment Address(VPA), is an address used to send and recieve money through UPI. It genrally look like: Username@bankname

What is a UPI PIN?

A UPI PIN is Personal authenication number is used to authorize UPI Transaction from your bank account.

Do I need a bank account to use UPI?

For Standard bank account UPI payment, you generally required to registration details.

Link this article to:

What Is a Bank Account? A Simple Guide to Savings, Current & Other Account Types

What Is a Bank Account?

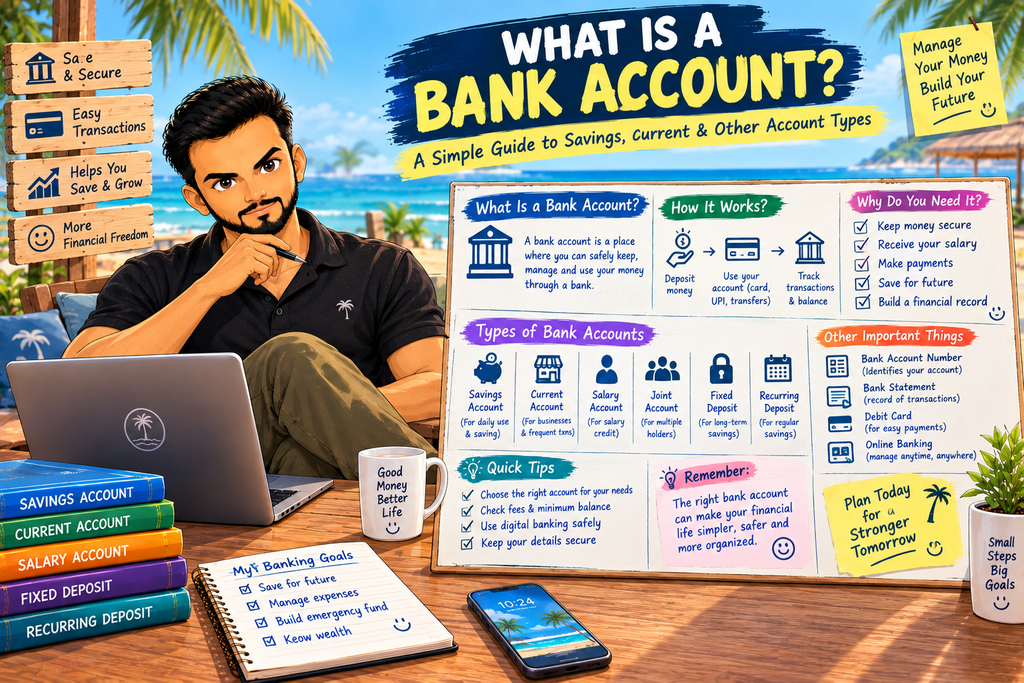
A bank account is a account hat allows you to keep, manage, transfer fund and deposits for daily to daily rountine life through financial institutions or Bank.

Insteding of keeping all your money as physical cash, you can deposit it into a bank account and yse service such as:

  • Depositing money
  • Withdrawing money
  • Receiving money
  • Sending money to others
  • Paying bills
  • Usding a debit cardsa
  • Saving money
  • Online payments

SImple words:

A bank account is aplace that keep your money safe and manage your money through a bank.

Different types of account have different purposes.

Students, salaried employees, businessman, and company uses different types of accounts.

How Does a Bank Account Work?

Opening a bank account creates your relation between you and bank.

You deposit money into a account and bank records show your deposits avauilable to you.

Example:

Let say you have saving of ₹10,000 and you go to bank branch or ATMs deposits machine to deposits your money.

Your account will niw show your available balance with applicable interest, any transaction, fees or other applicable adjustments.

You can use your money as a:

  • Withdraw cash
  • paying bills
  • Transfer to friends or relatives
  • Make purchases
  • Receive payments

Your provides statements every of transactions or records in your bank passbook of incoming and out going in your bank accounts.

Why Do People Need a Bank Account?

A bank account can make everyday managment money easier.

People commonly use bank account to:

1. Keep Money secure

A bank account can reduce the need to keep large amount of cash money from your house.

2. Receive money

A bank account allows you recieve money from other like in form of salary, transfer from relatives or friends, freelancing work payments and large transaction of your business from your clients etc . and many other purposes.

3. Make Payments

You canuse bank accounts for online transactions, bill payments, card payments and other transactions.

4. Save Money

Savings accounts allows you to keep money aside from daily spending.

5. Build a Financial Record

Bank Statements can provide your record of deposits, transactions, withdrawns, Transfer and other transactions.

Types of Bank Accounts

Banks offers differents types of account depends on customer needs.

Here are some common types.

1. Savings Accounts

A saving accounts is designed primarily for individual who wants to keep in the bank safely and easy access for daily routine.

It may offers interest rate on eligible balances, dpending on your bank and account terms.

People commonly uses for:

  • Emergency savings
  • Monthy savings
  • everyday banking
  • Short term financial goals

Example

Let say your salary is ₹50,000 per month.

You could received your salary in your bank account every month ans set aside for saving small portionfrom your salary.

Example:

  • Income: ₹50,000
  • Expenses: ₹35,000
  • Savings: ₹15,000

The ₹15,000 could remains in your bank accounts for future needs and uses.

2. Current Account

A cureent account is suitable for business and customers who frequent daily transactions.

Current accounts may be useful for:

  • Business
  • Traders
  • Companies
  • Professionals
  • Organizations

Thet may offers features designed for frequent payments and payments collections.

Unlike saving accounts this is not designed for earn interest on your balanced, it is for frequent transaction on daily.

3. Salary Accounts

A salary accounts is genrally an account for recieving salary from employer.

An employer may have agreement with bank or institution whroiugh which employee’s go to that bank directly.

Common feature includes:

  • Salary deposits
  • Debit card access
  • Online banking
  • Digital payments
  • ATM access

The benfits and minmium balances depends on agreements between employer and bank.

4. Joint Account

A joint account is an account is accounts holder two or more people.

Eaxmple:

Two family member may open account and shared equally shared responsibities to hold that account.

Dpendign on the accoutn mandate, may have different rules regarding who can operate the account and how transaction are authorized.

Always check bank term before opening your joint accounts.

5. Fixed Deposits Accounts

A Fixed deposits (FD) is different from normal savings accounts.

Fixed Deposits, you generally deposits a specfic amount for a chosen period at an agreed inetrest rate.

Example:

Deposits: ₹5,00,000

Tenure: ₹5 years

The money you earn interest dpends on your FDs Terms.

With drawing before maturity it may be charges applied on it as per Bank policies,. Other penatly, reduced inetrest rate dpending on your bank terms.

This means Fd is less felxible than normal savings accounts.

6. Recurring Deposit account

A redurring accounts allows that to save your money every month or yearly regularly for a specfied period.

Example

Monthy Seposits: ₹5,000

You keep putting your regular savings every time after agreed period you get good amount of yourdeposits with applicable Interest.

RD is a good financial products for who wants to save regularly.

Saving Account vs. Current Savings

FeatureSavings AccountCurrent Account
Main purposeSaving and everyday bankingFrequent business transactions
Typical usersIndividualsBusinesses and professionals
TransactionsRegular personal transactionsOften higher transaction activity
InterestMay earn interestOften not designed primarily for interest
Business useUsually limited/subject to termsCommonly designed for business use

The exact festure, fees, charges all policies depends on the bank.

What Is a Bank Account Number?

A Bank Account Number is a unique number associated with your bank account.

It Helps identify your specfic account of your when you deposits, transaction, recieved or transferred.

You may need money such things like:

  • Receiving Money
  • Bank Transfers
  • Setting up salary accounts
  • Provide bank details to organization for any payments

Your account Number is unique ans should be handled carefully and shared only to safely and geniue things.

What Is Bank Statements?

A Bank Statements is record of your account transaction, associated with your account over period of time.

It may Shows:

  • Deposits
  • Income
  • Withdrawals
  • Payments
  • Fees
  • Interest
  • Account Balance

Reviewing your records you can understand your where is your money and come from and identify any that you don’t recogize.

What Is a Debit Card?

A Debit Card is Linked to your bank account.

When you make elgible purchase using your card, money is genrally taken from your linked bank accounts according to your transaction.

You can also use a debit at supported ATMs to withdrawls of money.

A Debit Card is different from Credit card.

Debit Card is uses for transaction when your available balance is there in your bank accounts.

Credit Card is use transaction depends on your credit limits of your cards.

What Is Online Banking?

Online banking allows you to manage online transactions and activities through a bank websites or apps.

Dpending on your bank, you may be able to:

  • Check your balances
  • Pay bills
  • View transactions
  • Transfer money
  • Open deposits accounts
  • Manage cards
  • Download statements

Digital Banking has made everyday banking very easier. Within the seconds transaction is done you ready to go.

You should portects your card pins, OTPs transaction pins or passwords and keep it private. Don’t tell anyone.

How to Choose the Right Bank Accounts?

Before opening an account, think about how you plan it.

If you want to save money

A saving account may be suitable for everyday saving and access to funds.

If you run a business

A Current Account may be more appropriate for frequent business transaction.

If you receive a salary

A salary account may provide convenient slary dpeosits and relate Banking services.

If you want fixed Savings

An RD or Fd may be worth reasearching on your financial goal, time horizon and needs for access to your money.

Always Compare

  • Fees
  • ATMs charges
  • Minimum Requirements
  • Interest rate
  • Transaction limits
  • Withdrawls rules
  • Digtial banking features

FAQs

1. What is a bank account in simple words?

A bank account is a account hat allows you to keep, manage, transfer fund and deposits for daily to daily rountine life through financial institutions or Bank.

2. What is a Current Account?

A cureent account is suitable for business and customers who frequent daily transactions like traders, business, professional and organizations.

3. What is a Salary account?

A salary accounts is genrally ab account for recieving salary from employer.

4. What is a joint Bank account?

A joint account is an account is accounts holder two or more people. Two family member may open account and shared equally shared responsibities to hold that account

5. Can I have more than one bank account?

Yes. Aperson can have mutliple bank account, subject to bank rules and requirements.

6. What is a Debit Card?

When you make elgible purchase using your card, money is genrally taken from your linked bank accounts according to your transaction.

In details article will come soon.

Link this article to:

What Is a Loan? A Simple Guide to Understanding Loans

What Is a Loan?

Sometimes happens you reuired lot of money than you currently have.

It could be anything bigger purchase buy a house, a car, paying for higher education, starting business, or any unexpected expenses.

A loanm is money borrow from fbank, financial instituation, company or lender that you agree repay over a time in monthy fixed amount with interest.

In simple words:

a loan means borrowing money today and repayment later in small amopunt with fixed amount over a certain time with interest.

Understanding how loans works and what to kept in mind before and after in mind to not affect your future financial and monthy budget.

How Does a Loan Work?

The basi process of taking loan is simple.

Suppose you want to borrow ₹2,00,000 from a bank.

The bank may gives you money after checkng your incomes, credit hsitory, prevoius loans (if any) and abitity to repay.

You have to repay this amount with interest in cetain period of time over agreed terms.

Your Repayment include:

  • Principal – The orginial amount you borrowed
  • Interest – the cost of borrowing money
  • Fees or charges – dpend on the types of loans and lender

Example:

If you borrow money ₹2,00,000 from an bank is th your principal. The additional amount of money you had to pay with this generally interest.

What Is Principal in a Loan?

Principal amount is the orginal money amount you had borrow.

Example:

If you has take a loan of ₹2,00,000 from a bank . This amount is initial principal amount of ₹2,00,000.

As you make repayment of loan this principal amount gradually decreases.

The interest calculated of loan basically is all on this principal amount, depending on loan structure and terms you agreed.

What Is EMI?

Many loans mainly repays in EMIs or Equal Monthy Instalments.

An EMI is a regular monthy installment made towards a loans.

An EMi generally include both:

  • A Portion towards a principal amount
  • A portion towards a Interest amount
  • Example:

If you borrow for any vehicle, you may agree to repay in monthy payments for several years.

The EMI amount depends on your:

  • Loan Amount
  • Tenure
  • Interest Rate

The longer loan tenure reduces in monthy payments, but it may be also reults you paying more interest than your orginial loan amount.

Common Types of Loans

There are many such types of loans and each designed for different purposes.

1. Home Loan

A Home loan is genrally used to purchase, renovate a property or construct a properties.

This loans is larger amount and repayment tenure is longer, so undeerstanding your loans tenrure, repayment stucture , interest are all important factor included.

2. Personal loan

A Personal loans is genrally an unsecured loan that can be used for varoius purposes.

Depending on the lender and temrs, you may not need to provide any asset for collateral.

This loans may have retatively higher interest rate. due to unsecured loan.

3. Vehicle loan

A vehicle loan is used to purchase vehicle like motorcycle, car truck and other vehicle.

It can be purchase of new one or older car both comes in this loans.

This loans also depending on your how much you can afford that vehicle this calculted form income and saving capacity.

4. Education Loan

An Education loan used for helping covering higher education tutition fees and other expenses.

This may includes tution fees and other essential expenses that incvolved in appproval.

5. Business loan

A Business loan can provide for egible business purposes such as expansion, equipment, working capital or other busiiness expenses.

Secured Vs unsecured loan

Loans iare divided into two categories:

Secured Loans

A secured loans basically backled by assets for colleteral

Examples:

  • Home loan
  • Vehicle loan
  • Loans against home

If the borrower does not repay according to terms agreed, the lender may have rights relating colleterals, subject to appicable laws and rights.

Unsecured loan

An unsecured loan does not require of colleteral.

Example:

  • Personal loans
  • Credit score based loans

Because of borower do not have any colleteral terms, interest rate and tenure Emi may be different from secured loans.

Why Do People Take Loans?

People borrow money for many purposes.

Examples:

  • Buying a home
  • Purchase a vehicle
  • upgrade gadgets
  • Renovate house
  • Higher education
  • Handling larger expenses
  • Starting or expanding a business

Loan gives access of money rather you had to saved in full amount.

Borrowing may creates problems in repayments.

What Should You Check Before Taking a Loan?

Before taking loans, don’t look only on EMIs.

Consider the complete cost and conditions:

1. Interest Rate

Check the interest rate and understand whether it is fixed, variables or subject or change.

2. Loan Tenure

Understand how much long you will be making repayment.

3. Total Repayment

Calculate or check full repayment of a loan. Includes principal amount , iwth interest rate total, prepayments charges or other costs.

4. Processing fees and other charges

Some loans may have processings charges, late payments, prepayments charges or other costs.

Read the loans agreements.

5. Your monthy Budgets

Make sure repayments fit comfortably your income and expenses.

A loan repayemnts that is to larger can put pressure on your monthy cash flow.

Loan vs Saving: What’s the Difference?

Saving means puttuing your money aside for future use.

A loan means using borrowing money and repaying later.

Example:

Saving:

You save ₹10,000 every month and eventually use saving to purchase something.

Loan:

You borrow the money now and pay it later.

Saving generally avoids borrowing costs, while allows to access money and repay it later.

FAQs

What is a loan in simple words?

A loan means borrowing money today and repayment later in small amopunt with fixed amount over a certain time with interest

What is the principal amount of a loan?

Principal amount is the orginal money amount you had borrow.

What is loan interest?

Loan interest is a cost of borrowing money. It is charged according to the interest rate and terms agreed.

What is an EMI?

EMI stands for Equalled Monthy Instalment. An EMI is a regular monthy installment made towards a loans.

What are the mains types of loans?

Common types includes house loans, vehicle loans, education loan,personal loan and business loans.

What is the difference between a secured and unsecured Loan?

A secured loan is backed by colleteral while unsecured loan does not require specfice collateral.

Link this article to:

What Is Cash Flow? A Simple Guide for Beginners

What Is Cash Flow?

Cash flow simply means that movement of money coming in and out of your finances.

In simple words:

Money comes in = Cash inflow

Money hoing out = Cash outflow

Your cash flow show that your situation with expenses and income that wheather you have enough to cover your financial commitment and expesnes.

Example:

Let’s say you have income ₹50,000 and you spend ₹30,000 in that month.

₹50,000 – ₹30,000 = ₹20,000

You have ₹20,000 left after you spend.

Cash flow is important because just by earning money doesn’t automatically mean you have money available.

WHy Is Cash Flow Important?

Cash flows help you to understand with your money where is in month to month.

It can help your:

  • Make your better spending habits or decisions.
  • Plan Saving
  • Planned purchases
  • Unnecessary spending
  • Prepare for upcoming expenses
  • Manage debt payments
  • Avoid out of money before pay day comes

A good salary person still experience cash flow problems it too much money are spend each money.

Cash Inflow: Money Coming In

Cash Inclow is money that comes in your bank account before available for you.

Example:

Salary

Most common way of cash inflow that money you take home every month.

Freelance Income

Money recieved form freelancer project for potential income.

Business Income

A business income can be generates from sales and profits.

Rental Income

Rent recieved from your property that generates your cash inflow.

Interest or other investment source

Certain investment generates like dividends, interest etc.

your total monthy cash inflow is the amount of comes into your accounts.

Cash Outflow: Money Going Out

Cash outflow is money is goes out from your account.

Examples:

  • Rent
  • Groceries
  • Electricity bills
  • Transportation
  • Loan Payment
  • Insurances
  • Shopping
  • Enterainment
  • Subscriptions
  • Investment and saving transfers

Not every cash outflow is a bad things.

Example:

Transfer to your investment from your saving account but it is build assest for your future.

Positive Cash Flow Vs Negative Cash Flow

there are only two cashs flow.

Positive Cash Flows

you have positive cahs flows when more money comes in than money goes out during that financial period.

Example:

Income: ₹50,000

Outflows: ₹30,000

Cash flow:₹20,000

That ₹20,000 is your positive cash flow and can used for saving, investment, use to make other assets.

Negative cash Flow

Negative cash flow is when your money goes out more than your money comes in your fiancial period.

Example:

Income: ₹50,000

Outflows: ₹55,000

Cash flow:₹-5,000

If this happen regularly month after month then you required use your saving, investment and other debt or borrow money.

Once occasionally negative cash flow moneth it not concern. But bigger concern when it happened repeated onth after month of negative cash flow.

How to Calculate Your cash Flow?

Cash Flow = Total Cash Inflows – Total Cash outflows

Example:

Salary: ₹50,000

Freelancer income: ₹5,000

Total Inflow: ₹55,000

Your monthy outflows are:

Rent = ₹12,000

Food = ₹7,000

Transport = ₹3,000

Bills = ₹3,000

Enterainment = ₹2,000

Other spending = ₹3,000

Total Outflows: ₹30,000

₹55,000 – ₹30,000 = ₹25,000

Your toatal monthy Cash flow is +₹25,000.

Cash Flow Is Not the Same as Income

Income tell you ho much money you earn or recieve.

Cash Flow looks ar both the money coming in and money goes out.

Example:

Your Earning ₹50,000.

But you spend ₹45,000.

Your income is:

₹50,000

Your remaining cah flow is ₹5,000.

Knowing your income alone doesn’t tell you how much money you actually have avilable after your otuflows.

Cash Flow Is Not the Same as Profits

The word “Cash flow” is aslo commonly used in business.

A business might make a profit on paper but still have cash floew problems if customers haven’t paid yet or if large bills need to be paid immediately.

Simple concept for personal finance

Cash flow focus on the movement and avilability of money.

How to Improve Your Cash Flow

If your cash flow regulary tight, you genrally have borad options:

Increase money Coming In

Here are some practical steps:

1. Track Your Money

For one month, recoed your every cash inflow and outflows.

you may unnecessary expenses that you might not aware of.

2. Reduce Unnecessary Expenses

Look At subscriptions, impulse purchases, eating out,shopping and optional spending.

You have to eliminate your enjoyable expenses.

you have to just have aware of where your money goes.

3. Plan for Irregular Savings

Some expenses don’t happen every month.

Examples:

  • Annual Insurance premium
  • Repairs
  • Festivals
  • Travels
  • Schools fees
  • Property expenses

Ste money aside ahead of time so you get disrupt your monthy cash flow.

4. Build an Emergency Fund

An Emergency fund can helps you handle your unexpected expenses without immediately relying on expensive debt.

5. Increase your Income

You could potentially increase your cash inflo. doiung freelancing work, rent a you own things, buying assets and learning new skills and many more ways to increase your cash inflows.

A Simple Monthy Cash-Flow Table

CategoryAmount
Salary₹50,000
Other income₹5,000
Total inflow₹55,000
Rent & bills₹15,000
Food₹7,000
Transport₹3,000
Entertainment₹2,000
Other expenses₹3,000
Total outflow₹30,000
Cash flow₹25,000

A Simple speedsheet is enough.

What Should You Do With Positive Cash Flow?

If you consistently have money left over, don’t le it disappear withour plkan.

You can surplus between:

  • Emergency plan
  • Short-term goals
  • Debt Repayments
  • Lifestyle spending
  • Long-terms investment

The ridht between financial goals and situations.

What If Your Cash Flow Is Negative?

Don’t Panic.

Start by identify why it’s negative.

Ask:

  • Are my essential expensive too high?
  • Am I spending too much on wnarts?
  • Di i have large debt repayments?
  • Can I increase my income?
  • Aim I spending without tracking?

Once you know your reason, start appropriate step toward the solutions.

FAQs

WHat is Cash Flow in Simple words?

Cash flow simply means that movement of money coming in and out of your finances.

What is Positive Cash Flow?

Positive cashs flows when more money comes in than money goes out during that financial period.

What is Negative cash Flow?

Negative cash flow is when your money goes out more than your money comes in your fiancial period.

How Do I calculate cash flow?

Subract your total cash outflow from total cash inflow.

Is Saving money part of cash flow?

Moving money into saving is and utflow from your spending account, but it is still remains your money becaome part of saving.

Link this article to: