What Is a Recurring Deposit (RD)?
A Reccuring Deposit (RD) is a saving product that allows you to deposit a fixed amount of money regularly, generally month, for the selceted period.
In simple Word,
A RD is a savings by putting aside a fixed amount of money for regularly month and earn interest on its deposits.
Example:
Instead of investing lumpsum of ₹60,000 at once within period
₹5,000 every month regularly for 12 months.
Ar the end of a RD temure, you generally recieved your deposited money and applicable interest on it.
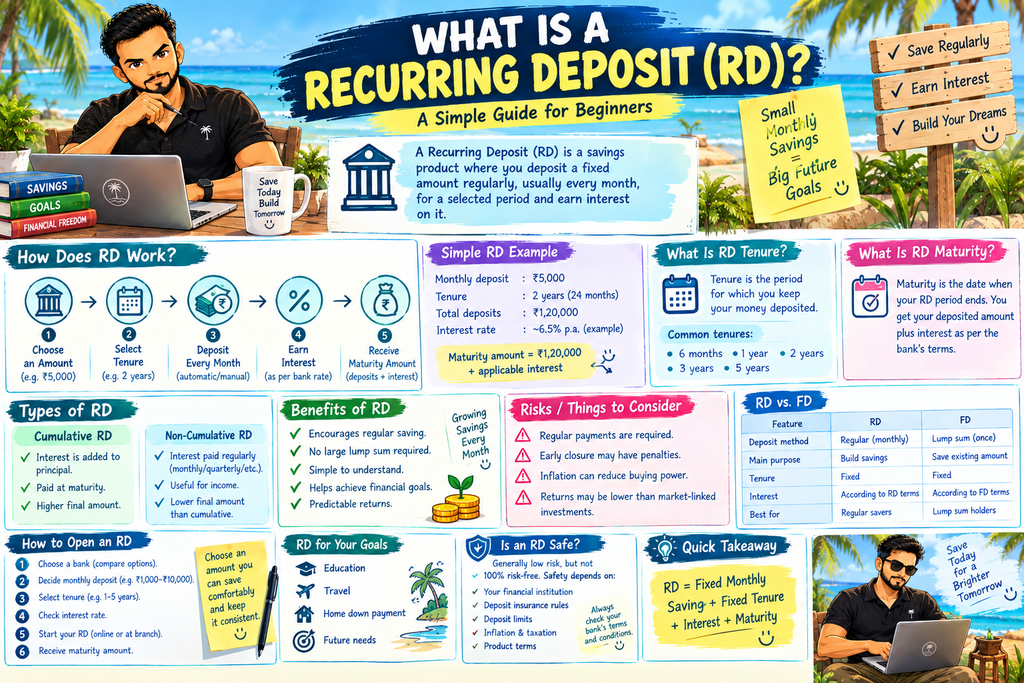
Table of Contents
How Does a Recurring Deposit Work?
An RD works through regular invested.
The Bsic Process is:
Choose monthy Payment – Choose Tenure – Deposit every month – Earn Interest – Receive MAturity Amount.
Example
- Monthy Deposit:₹5,000
- Tenure: 3 Year
- Total Deposits: ₹5,000 X 36 months = ₹1,80,000
The final Maturity amount would inlcude applicable interest as per agreed.
The exact maturity amount depends on the interest rate, compound interest mehtod, tenure, and bank’ Rd Terms.
How to Open an RD?
Open an Rd is simple Process and some simlar to FD:
Step 1: Choose a Bank
Compare a Rd option avilable from our bank or other eligible financial institutions.
Step 2: Decide Your Monthy Deposit
Choose the amount that you can comfortably save every month.
Example
₹1,000, ₹4,000, ₹5,000, ₹10,000 per month
The minimum amount depend on the various institutuions.
Step 3: Select the Tenure
Choose hwo long you want to keep continue in deposit.
Available tenure vary on banks.
Step 4: Check the Interest Rate
Look at the applicable interest rate and choose your as your tenure.
Step 5: Start Your RD
Ste up recurring seposit and make a required monthy payment.
Step 6: Receive the Maturity Amount
Once the RD reached maturity, you generally recieve your deposits plus applicable Interest.
Why Do People Use Recurring Deposits?
An RD cn be useful for people who want to develop a regular saving habits.
Inbsted waiting until you have lumpsum of that amount, you can save smaller amount for every month.
Example:
₹3,000 per month
may feel and confident this amount easier to save this amount of money.
₹60,000
This makes an RD paryiculary easy to understand for beginners.
What Is a Tenure?
Tenure means the length of time for which you make youir recurring deposits.
Example, an Tenure could have tenure of:
- 6 Months
- 1 Year
- 2 Year
- 4 Year
- 3 Year
- 5 year
The avialable tenure dpenod on your bank or financial Institutions.
Choose your tenure as per your financial goals and when you expect to need this money.
What Is RD Maturity?
MNAturity is date when your selected RD Period ends.
Example:
You genreally make the required monthy deposits throughout the selected period.
At maturity, you recieve the accumlated deposits and applicable inetrest according to the RD Terms.
RD vs. FD: What Is the Difference?
Both RD and Fd are deposits savings but work differently
| Feature | Recurring Deposit (RD) | Fixed Deposit (FD) |
|---|---|---|
| Deposit method | Regular deposits | Usually one lump-sum deposit |
| Example | ₹5,000 every month | ₹1,20,000 once |
| Main purpose | Build savings gradually | Save an existing lump sum |
| Regular saving required | Yes | No |
| Tenure | Fixed | Fixed |
| Interest | According to RD terms | According to FD terms |
| Suitable for | People saving monthly | People with a lump sum |
Sumple Difference:
RD = save fixed amount every month regualrly
FD = Depositsa Lumpsum for fixed Period
Rd vs. Savings Accounts
A Saving and RD serve diffrently.
| Feature | Savings Account | Recurring Deposit |
|---|---|---|
| Main purpose | Everyday banking & saving | Regular planned saving |
| Access to money | Generally easy | Conditions may apply |
| Fixed tenure | No | Yes |
| Regular deposit | Not required | Required |
| Interest | According to account terms | According to RD terms |
| Best suited for | Everyday money & liquidity | Goal-based regular saving |
Benefits of a Recurring Deposits
1. Encourages Regular Saving
You commit to saving a fixed a amount every month.
2. No Large Lump Sump Required
You don’t necessarily need a large amount of money to get started.
3. Simple to Understand
The Basic Concept:
Deposited every month – Earn Interest – Receive Maturity amount.
4. Helps With Fiancial Goals
An RD can be used for planned expenses such as:
- Education
- Travel
- A future Purchases
- Annual Expenses
- Short or medium terms goals
5. Predictable Structure
You know hoe much you are expected to deposited each month and the slected tenure.
What Are the Dis advantages of an RD?
An RD also has Limitations.
1. Regular Payments Are required
You need amaintain enough money in your account ot make the schedule deposits.
2. Early closure may have conditions
If you closure the RD before maturity the bank may appl specfic rules or reduces the interest payables.
3. Inflation Can reduce Purchasing power
If inflation is higher than your effective returns, your money may lose purchasing power over time.
What Happens If You Miss an RD payment?
If you don’t have enough money in your account when the monthy installment is due, the bank may apply its applicable rules:
Possible cosmeueences can include:
- A late peyments penatly
- Additional Charges
- Changes to the account status
- Resitrictiopn or closure after on other miss payment
The exact cosnequreneces dpend on the bank term and rules.
Can You Withdraw an RD Before Maturity?
Soem banks allow premature closure of an Rd, but the codntions vary.
You may receive:
- A different applicable interest rate
- Reduced interest
- A pently or adjustment
- other applicable charges
Before opening an RD check the Bank’s rules regarding premature charges.
Is an RD Suitable for Beginners?
An RD can be easy for bignners to understand because it creates an simplke saving routine.
Example:
Monthy income – set aside ₹3,000 – RD – continue Every month
Before staring one, make sure uou have enough money available for:
- Everyday Expenses
- Emeregency Needs
- Existing Financial Commitments
How Much Should You Save in an RD?
There is no single amount for everyone.
A simple starting point it top choose a amount easily can save and invest regualry without pressure on your monthy budget.
If your monthy budget allow you to comfortably save ₹3,000 uou might cosnider your amount of Rd nearer to it.
The goals is to consistency.
RD for Financial Goal
Let say you want a plan vacation 2 year from now.
You estimated around that you needed:
₹1,20,000
Insted of finding lumpsum of ₹1,20,000 immediately, you could create a regular saving plans.
Example:
₹5,000 x 24 month =₹1,20,000
Any applicable ineterest may apply as per FD terms.
This make how regularly monthy saving can make larger financial goals easier to approach.
Is an RD Risk-Free?
It is beeter not to describe any fiancial product simply as “100% risk free.”
Factor such as:
- Financial institutions
- Applicable deposist isnurance
- Deposits limits
- Prduct tems
- Inflation
- Taxation
If you decide that deposits latger amount read the terms before putting larger sum of money protection and bank or instituions rules.
Things to Check Before Opening an RD?
Before Opening RD, compare more than the interest rate.
Check:
1. Interest Rate
Compare the rate offeres to your desried value.
2. Tenure
Choose your period that matches your financial goals.
3. Maturity Amount
Check how much you got at the time of maturity.
4. Premature Withdrawal Rules
Understand what happen when you needed your early.
5. Payout Option
Check whethewr interest is paid periodically or at maturity.
6. Tax Treatment
Udnerstand how the interest wiil be treated udner applicable tax rules.
7. Deposit Protection
Check the aplicable deposit isnurance coverage and limits.
8. Monthy Deposits
Make sure the amount fits comfortably into your budgets.
FAQs
What is a Recurring Deposit?
A RD is a savings by putting aside a fixed amount of money for regularly month and earn interest on its deposits.
What Does RD Stand For?
Rd stands for Recurring Deposit.
How Does an RD work?
You choose a monthy deposit amount and tenure, make rgular dpeosits and ecirve the accumlated deposits plus applicable insterest.
What is the difference between FD and RD?
An RD involves monthy deposits and Fd is lumpum amount of money once for a fixed period.
Can I Start and RD with a small Amount?
Many banks offers RDs with retatively small minums monthy deposits but the exact minumum varies by insitutions.
What happen if I miss and RD payments?
You bank charge a pently or apply other conditons. The Exact cosnequeences dp[ends on th bank’s RD rules.
Can I Withdraw an RD before maturity?
Some bank allow permature closure, but reduced interest, penalties or other indcidual circumstances.
Link this article to:
- What is Saving?
- What is Income?
- What is Compound Interest?
- What Is Inflation?
- What is Insurance?
- What is investing?
- Types of Investment?
- What is Budget?
- Saving vs Investing
- What is Net worth?
- What Is Exapenses?
- What is Cash Flow?
- What is Liquidity
- What Is Loans?
- What Is EMI?
- What Is Credit Card?
- What Is Bank Account?
- What Is ATM?
- What Is UPI payment?