What Is a Bank Account? A Simple Guide to Savings, Current & Other Account Types

What Is a Bank Account?

A bank account is a account hat allows you to keep, manage, transfer fund and deposits for daily to daily rountine life through financial institutions or Bank.

Insteding of keeping all your money as physical cash, you can deposit it into a bank account and yse service such as:

  • Depositing money
  • Withdrawing money
  • Receiving money
  • Sending money to others
  • Paying bills
  • Usding a debit cardsa
  • Saving money
  • Online payments

SImple words:

A bank account is aplace that keep your money safe and manage your money through a bank.

Different types of account have different purposes.

Students, salaried employees, businessman, and company uses different types of accounts.
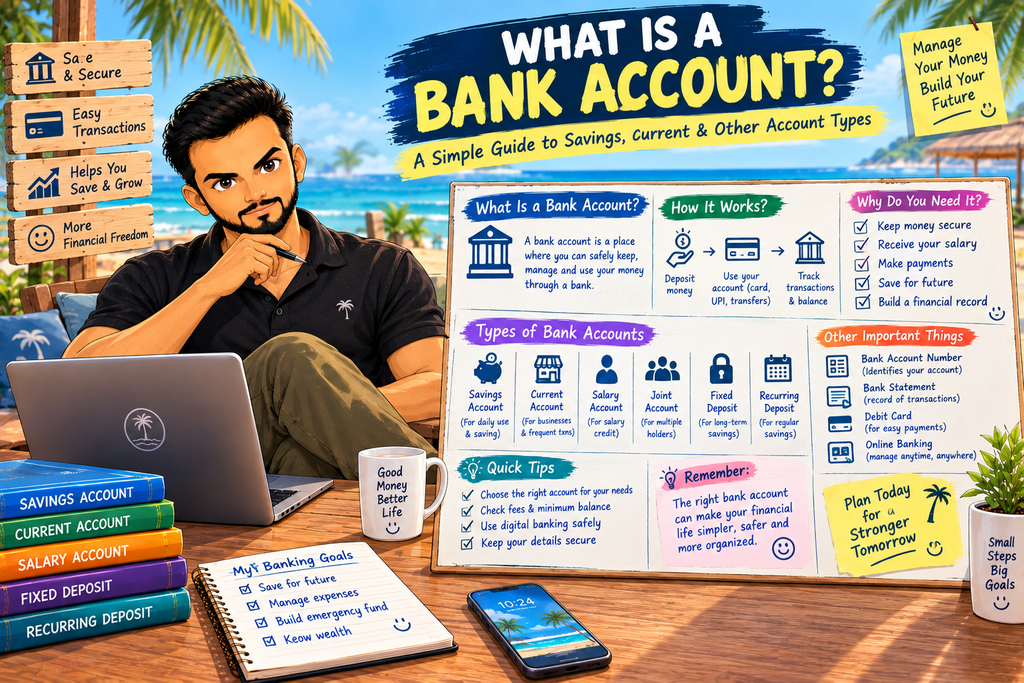
How Does a Bank Account Work?

Opening a bank account creates your relation between you and bank.

You deposit money into a account and bank records show your deposits avauilable to you.

Example:

Let say you have saving of ₹10,000 and you go to bank branch or ATMs deposits machine to deposits your money.

Your account will niw show your available balance with applicable interest, any transaction, fees or other applicable adjustments.

You can use your money as a:

  • Withdraw cash
  • paying bills
  • Transfer to friends or relatives
  • Make purchases
  • Receive payments

Your provides statements every of transactions or records in your bank passbook of incoming and out going in your bank accounts.

Why Do People Need a Bank Account?

A bank account can make everyday managment money easier.

People commonly use bank account to:

1. Keep Money secure

A bank account can reduce the need to keep large amount of cash money from your house.

2. Receive money

A bank account allows you recieve money from other like in form of salary, transfer from relatives or friends, freelancing work payments and large transaction of your business from your clients etc . and many other purposes.

3. Make Payments

You canuse bank accounts for online transactions, bill payments, card payments and other transactions.

4. Save Money

Savings accounts allows you to keep money aside from daily spending.

5. Build a Financial Record

Bank Statements can provide your record of deposits, transactions, withdrawns, Transfer and other transactions.

Types of Bank Accounts

Banks offers differents types of account depends on customer needs.

Here are some common types.

1. Savings Accounts

A saving accounts is designed primarily for individual who wants to keep in the bank safely and easy access for daily routine.

It may offers interest rate on eligible balances, dpending on your bank and account terms.

People commonly uses for:

  • Emergency savings
  • Monthy savings
  • everyday banking
  • Short term financial goals

Example

Let say your salary is ₹50,000 per month.

You could received your salary in your bank account every month ans set aside for saving small portionfrom your salary.

Example:

  • Income: ₹50,000
  • Expenses: ₹35,000
  • Savings: ₹15,000

The ₹15,000 could remains in your bank accounts for future needs and uses.

2. Current Account

A cureent account is suitable for business and customers who frequent daily transactions.

Current accounts may be useful for:

  • Business
  • Traders
  • Companies
  • Professionals
  • Organizations

Thet may offers features designed for frequent payments and payments collections.

Unlike saving accounts this is not designed for earn interest on your balanced, it is for frequent transaction on daily.

3. Salary Accounts

A salary accounts is genrally an account for recieving salary from employer.

An employer may have agreement with bank or institution whroiugh which employee’s go to that bank directly.

Common feature includes:

  • Salary deposits
  • Debit card access
  • Online banking
  • Digital payments
  • ATM access

The benfits and minmium balances depends on agreements between employer and bank.

4. Joint Account

A joint account is an account is accounts holder two or more people.

Eaxmple:

Two family member may open account and shared equally shared responsibities to hold that account.

Dpendign on the accoutn mandate, may have different rules regarding who can operate the account and how transaction are authorized.

Always check bank term before opening your joint accounts.

5. Fixed Deposits Accounts

A Fixed deposits (FD) is different from normal savings accounts.

Fixed Deposits, you generally deposits a specfic amount for a chosen period at an agreed inetrest rate.

Example:

Deposits: ₹5,00,000

Tenure: ₹5 years

The money you earn interest dpends on your FDs Terms.

With drawing before maturity it may be charges applied on it as per Bank policies,. Other penatly, reduced inetrest rate dpending on your bank terms.

This means Fd is less felxible than normal savings accounts.

6. Recurring Deposit account

A redurring accounts allows that to save your money every month or yearly regularly for a specfied period.

Example

Monthy Seposits: ₹5,000

You keep putting your regular savings every time after agreed period you get good amount of yourdeposits with applicable Interest.

RD is a good financial products for who wants to save regularly.

Saving Account vs. Current Savings

FeatureSavings AccountCurrent Account
Main purposeSaving and everyday bankingFrequent business transactions
Typical usersIndividualsBusinesses and professionals
TransactionsRegular personal transactionsOften higher transaction activity
InterestMay earn interestOften not designed primarily for interest
Business useUsually limited/subject to termsCommonly designed for business use

The exact festure, fees, charges all policies depends on the bank.

What Is a Bank Account Number?

A Bank Account Number is a unique number associated with your bank account.

It Helps identify your specfic account of your when you deposits, transaction, recieved or transferred.

You may need money such things like:

  • Receiving Money
  • Bank Transfers
  • Setting up salary accounts
  • Provide bank details to organization for any payments

Your account Number is unique ans should be handled carefully and shared only to safely and geniue things.

What Is Bank Statements?

A Bank Statements is record of your account transaction, associated with your account over period of time.

It may Shows:

  • Deposits
  • Income
  • Withdrawals
  • Payments
  • Fees
  • Interest
  • Account Balance

Reviewing your records you can understand your where is your money and come from and identify any that you don’t recogize.

What Is a Debit Card?

A Debit Card is Linked to your bank account.

When you make elgible purchase using your card, money is genrally taken from your linked bank accounts according to your transaction.

You can also use a debit at supported ATMs to withdrawls of money.

A Debit Card is different from Credit card.

Debit Card is uses for transaction when your available balance is there in your bank accounts.

Credit Card is use transaction depends on your credit limits of your cards.

What Is Online Banking?

Online banking allows you to manage online transactions and activities through a bank websites or apps.

Dpending on your bank, you may be able to:

  • Check your balances
  • Pay bills
  • View transactions
  • Transfer money
  • Open deposits accounts
  • Manage cards
  • Download statements

Digital Banking has made everyday banking very easier. Within the seconds transaction is done you ready to go.

You should portects your card pins, OTPs transaction pins or passwords and keep it private. Don’t tell anyone.

How to Choose the Right Bank Accounts?

Before opening an account, think about how you plan it.

If you want to save money

A saving account may be suitable for everyday saving and access to funds.

If you run a business

A Current Account may be more appropriate for frequent business transaction.

If you receive a salary

A salary account may provide convenient slary dpeosits and relate Banking services.

If you want fixed Savings

An RD or Fd may be worth reasearching on your financial goal, time horizon and needs for access to your money.

Always Compare

  • Fees
  • ATMs charges
  • Minimum Requirements
  • Interest rate
  • Transaction limits
  • Withdrawls rules
  • Digtial banking features

FAQs

1. What is a bank account in simple words?

A bank account is a account hat allows you to keep, manage, transfer fund and deposits for daily to daily rountine life through financial institutions or Bank.

2. What is a Current Account?

A cureent account is suitable for business and customers who frequent daily transactions like traders, business, professional and organizations.

3. What is a Salary account?

A salary accounts is genrally ab account for recieving salary from employer.

4. What is a joint Bank account?

A joint account is an account is accounts holder two or more people. Two family member may open account and shared equally shared responsibities to hold that account

5. Can I have more than one bank account?

Yes. Aperson can have mutliple bank account, subject to bank rules and requirements.

6. What is a Debit Card?

When you make elgible purchase using your card, money is genrally taken from your linked bank accounts according to your transaction.

In details article will come soon.
Link this article to:

What Is a Loan? A Simple Guide to Understanding Loans

What Is a Loan?

Sometimes happens you reuired lot of money than you currently have.

It could be anything bigger purchase buy a house, a car, paying for higher education, starting business, or any unexpected expenses.

A loanm is money borrow from fbank, financial instituation, company or lender that you agree repay over a time in monthy fixed amount with interest.

In simple words:

a loan means borrowing money today and repayment later in small amopunt with fixed amount over a certain time with interest.

Understanding how loans works and what to kept in mind before and after in mind to not affect your future financial and monthy budget.

How Does a Loan Work?

The basi process of taking loan is simple.

Suppose you want to borrow ₹2,00,000 from a bank.

The bank may gives you money after checkng your incomes, credit hsitory, prevoius loans (if any) and abitity to repay.

You have to repay this amount with interest in cetain period of time over agreed terms.

Your Repayment include:

  • Principal – The orginial amount you borrowed
  • Interest – the cost of borrowing money
  • Fees or charges – dpend on the types of loans and lender

Example:

If you borrow money ₹2,00,000 from an bank is th your principal. The additional amount of money you had to pay with this generally interest.

What Is Principal in a Loan?

Principal amount is the orginal money amount you had borrow.

Example:

If you has take a loan of ₹2,00,000 from a bank . This amount is initial principal amount of ₹2,00,000.

As you make repayment of loan this principal amount gradually decreases.

The interest calculated of loan basically is all on this principal amount, depending on loan structure and terms you agreed.

What Is EMI?

Many loans mainly repays in EMIs or Equal Monthy Instalments.

An EMI is a regular monthy installment made towards a loans.

An EMi generally include both:

  • A Portion towards a principal amount
  • A portion towards a Interest amount
  • Example:

If you borrow for any vehicle, you may agree to repay in monthy payments for several years.

The EMI amount depends on your:

  • Loan Amount
  • Tenure
  • Interest Rate

The longer loan tenure reduces in monthy payments, but it may be also reults you paying more interest than your orginial loan amount.

Common Types of Loans

There are many such types of loans and each designed for different purposes.

1. Home Loan

A Home loan is genrally used to purchase, renovate a property or construct a properties.

This loans is larger amount and repayment tenure is longer, so undeerstanding your loans tenrure, repayment stucture , interest are all important factor included.

2. Personal loan

A Personal loans is genrally an unsecured loan that can be used for varoius purposes.

Depending on the lender and temrs, you may not need to provide any asset for collateral.

This loans may have retatively higher interest rate. due to unsecured loan.

3. Vehicle loan

A vehicle loan is used to purchase vehicle like motorcycle, car truck and other vehicle.

It can be purchase of new one or older car both comes in this loans.

This loans also depending on your how much you can afford that vehicle this calculted form income and saving capacity.

4. Education Loan

An Education loan used for helping covering higher education tutition fees and other expenses.

This may includes tution fees and other essential expenses that incvolved in appproval.

5. Business loan

A Business loan can provide for egible business purposes such as expansion, equipment, working capital or other busiiness expenses.

Secured Vs unsecured loan

Loans iare divided into two categories:

Secured Loans

A secured loans basically backled by assets for colleteral

Examples:

  • Home loan
  • Vehicle loan
  • Loans against home

If the borrower does not repay according to terms agreed, the lender may have rights relating colleterals, subject to appicable laws and rights.

Unsecured loan

An unsecured loan does not require of colleteral.

Example:

  • Personal loans
  • Credit score based loans

Because of borower do not have any colleteral terms, interest rate and tenure Emi may be different from secured loans.

Why Do People Take Loans?

People borrow money for many purposes.

Examples:

  • Buying a home
  • Purchase a vehicle
  • upgrade gadgets
  • Renovate house
  • Higher education
  • Handling larger expenses
  • Starting or expanding a business

Loan gives access of money rather you had to saved in full amount.

Borrowing may creates problems in repayments.

What Should You Check Before Taking a Loan?

Before taking loans, don’t look only on EMIs.

Consider the complete cost and conditions:

1. Interest Rate

Check the interest rate and understand whether it is fixed, variables or subject or change.

2. Loan Tenure

Understand how much long you will be making repayment.

3. Total Repayment

Calculate or check full repayment of a loan. Includes principal amount , iwth interest rate total, prepayments charges or other costs.

4. Processing fees and other charges

Some loans may have processings charges, late payments, prepayments charges or other costs.

Read the loans agreements.

5. Your monthy Budgets

Make sure repayments fit comfortably your income and expenses.

A loan repayemnts that is to larger can put pressure on your monthy cash flow.

Loan vs Saving: What’s the Difference?

Saving means puttuing your money aside for future use.

A loan means using borrowing money and repaying later.

Example:

Saving:

You save ₹10,000 every month and eventually use saving to purchase something.

Loan:

You borrow the money now and pay it later.

Saving generally avoids borrowing costs, while allows to access money and repay it later.

FAQs

What is a loan in simple words?

A loan means borrowing money today and repayment later in small amopunt with fixed amount over a certain time with interest

What is the principal amount of a loan?

Principal amount is the orginal money amount you had borrow.

What is loan interest?

Loan interest is a cost of borrowing money. It is charged according to the interest rate and terms agreed.

What is an EMI?

EMI stands for Equalled Monthy Instalment. An EMI is a regular monthy installment made towards a loans.

What are the mains types of loans?

Common types includes house loans, vehicle loans, education loan,personal loan and business loans.

What is the difference between a secured and unsecured Loan?

A secured loan is backed by colleteral while unsecured loan does not require specfice collateral.

Link this article to:

What Is Liquidity? A Simple Guide to Understanding How Quickly You Can Access Your Money

What Is Liquidity?

Whn managing your money, it is important to know how quickly you can access your money when you need it.

This is where the concept of liquidity vecome important.

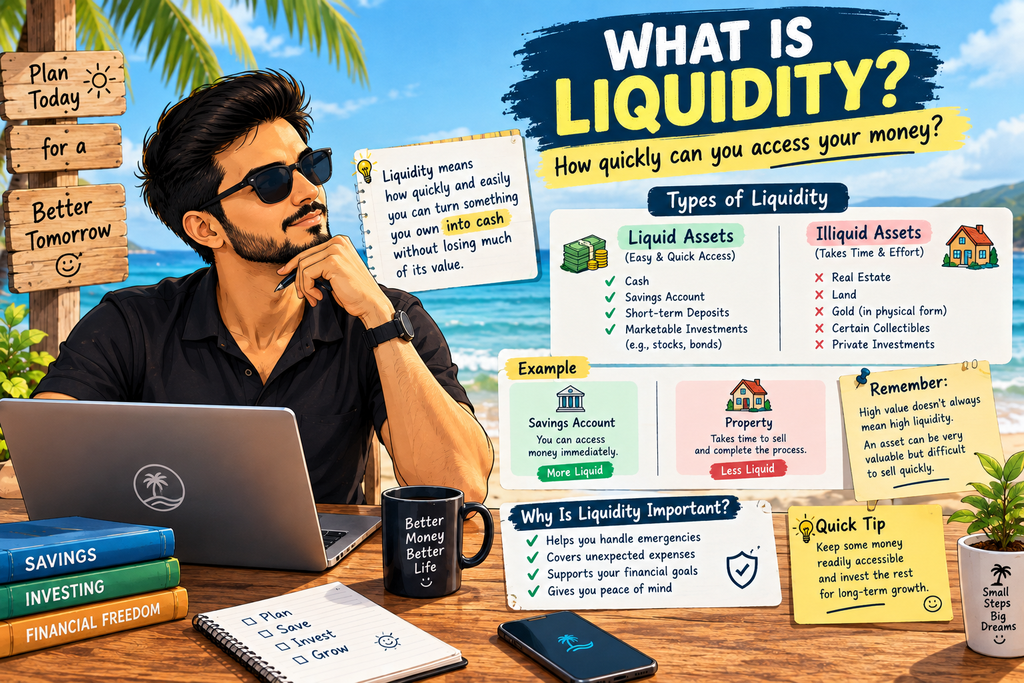
In simple words, Liquidity means to how quickly and easily you can turn into something you own into cash without losing much its value.

Example:

Money in your bank account is highly liquid because it can easily cash out, in other uour house is very less liquid because it will take week or months to sell.

Understanding liquidity can help you make better decision in saving, investing, and keep money for emergencies.

What Does Liquidity Means?

Liquidity means how easily an asset can be converted into cash.

Think it in this way:

Easily and quick access = High Liquidity

Difficult or slow proces to liquidity = low liquidity

Example:

  • Cash – very high liquidity
  • Saving accounts – high liquidity
  • FDs – Medium liquidity
  • Property – Very low liquidity

The Exact liquidity of an asset can depend on other factors market condition and trends, situation of asset and any ristriction or selling it.

Simple Example of Liquidity

Imagine you suddenly need ₹20,000 for an unexpected expense.

You have two options:

Option 1: ₹20,000 in your savings account.

You can generally access the money immediately.

Option 2: You own a piece of property worth ₹20 lakh.

Although the property has significant value, you cannot normally turn it into ₹20,000 immediately. You would need to find a buyer, complete the transaction, and receive the money.

Therefore, the savings account is more liquid than the property.

This shows an important point:

Having valuable assets does not always mean having money that is easily available.

What Are Liquid Assets?

A Liquid asset is an asset that can converted into cash easily and very loss of value.

Common Exmaple:

1. Cash

Cash is th most liquid form of money because you can use it directly to pay things.

2. Money In saving Account

Money in a saving account is genrally highly account because you access this cash from anywhere in the world through like ATMs, Bank Branches, UPI and other online apps and money online mehtods.

3. Short-Term Deposits

Some Deposits can provide relatively easy access to money, athough withdrawal rules and other charges may apply.

4. Marketable Investments

Certain investment can easyily access to buy or sell such as stocks and bonds but is can be done open market hours.

Selling an investment is does not means you will get exact amount of money that you invest init.

What are Illiquid Assets?

An Illiquid assets that considerable takes time or effort to convert in cash.

Example:

  • Real eastate
  • Land
  • Certain collectibles
  • Manchinery or specialized equipment

Example:

Your house to sell is time taking process may be takes weeks or months yo find right buyer, negotiating, completing paperworks and transfers fund .

Property is a very low liquidity than any cash .

Liquidity Vs Value

Liquidity and value are two different things.

An assets can be valuable but not easily liquidity.

Example:

Your watches collectibles are very valuables of ₹50,00,000. it is low liquidity.

₹50,000 in bank account : low value, higher liquidity.

This is why personal finance is not only about how much you own it. it is also about how much you can cash in when you need it most.

Why Is Liquidity Important?

Liquidity is very important when unxepected expenses happen.

Suppose your monthy salary is ₹50,000, but most of your wealth in long term investment and it in bear market and other are in property.

Ugent emergencies happen and you required of 1 lakhs rupees to pay save your family memebers without taking any loans or selling.

Keep Liquidity in such situations like:

  • Medical expenses
  • Unexpected repairs
  • Temporary loss of income
  • Urgent travel
  • Important houshold expenses

This one improtant reason you should build your emergency fund to this type of situations.

Is More Liquidity Always Better?

Not Necessarily.

Keeping all money in to easily access in cash also create a problems for financial life, it’s not helps out for long term financial goals. easy access to cash you make more expenses from it.

On the other hand, keeping all wealth into assest aslo make difficult to seel when you need it. it is harder to cash in unexpected expenses.

A Balanced approach make you comfortable for short term access in cash and for long term goasl is suitable in asset that build your wealth in over period of time.

Keep easy to access 20% to 30 % of your wealth in highly liquidity products.

Liquidity and Investment

Liquidity is an important factor before investing.

Before putting money into an investment ask yourself

“If I needed this money suddenly, how easily can I get it back?”

For Short term money, It is easy to access to money such as saving bank acccount money, debt card, bonds etc.

For long term money, It is should be placed into longer period investment instrument such , golds, stocks, MFs, bonds and ETFs.

Remember liquidity is doe not means safety.

An Investment may be easy to sell but can fall in value.

How Can You Improve Your Financial Liquidity?

You can improves your financial liquidity by keeping an appropriate amount of money in easily accessible account or assets.

Simple Step Includes

  • Build your Emergency Funds
  • Keep some money ready accessible for regular expenses
  • Understanding rules and charges before putting into deposits
  • Avoid all the money into iiliquidity assets and financial products.
  • Know your investment how quickly you can converted into cash

The right amount of money is not same to everyone it may different factors depends such on income, expenses, saving, invesment size and risk tolerence.

FAQS

What is Liquidity in simple terms?

Liquidity means to how quickly and easily you can turn into something you own into cash without losing much its value

What is Liquidity?

Liquidity means how easily an asset can be converted into cash. example suchs money in saving bank accounts, cash and certain pubicly traded investments.

Is cash the most liquid assets?

Yes. cash is genrally highly liquidity assest because it can be easily accessible and you immediately without any seeling or convert anything.

Link this article to:

What Is Cash Flow? A Simple Guide for Beginners

What Is Cash Flow?

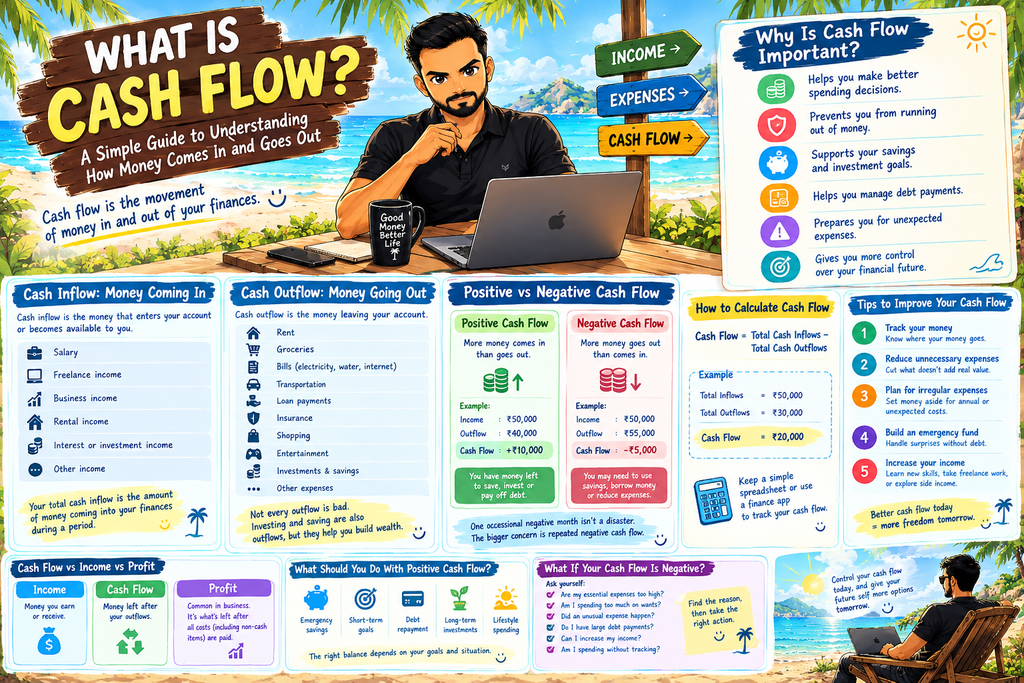
Cash flow simply means that movement of money coming in and out of your finances.

In simple words:

Money comes in = Cash inflow

Money hoing out = Cash outflow

Your cash flow show that your situation with expenses and income that wheather you have enough to cover your financial commitment and expesnes.

Example:

Let’s say you have income ₹50,000 and you spend ₹30,000 in that month.

₹50,000 – ₹30,000 = ₹20,000

You have ₹20,000 left after you spend.

Cash flow is important because just by earning money doesn’t automatically mean you have money available.

WHy Is Cash Flow Important?

Cash flows help you to understand with your money where is in month to month.

It can help your:

  • Make your better spending habits or decisions.
  • Plan Saving
  • Planned purchases
  • Unnecessary spending
  • Prepare for upcoming expenses
  • Manage debt payments
  • Avoid out of money before pay day comes

A good salary person still experience cash flow problems it too much money are spend each money.

Cash Inflow: Money Coming In

Cash Inclow is money that comes in your bank account before available for you.

Example:

Salary

Most common way of cash inflow that money you take home every month.

Freelance Income

Money recieved form freelancer project for potential income.

Business Income

A business income can be generates from sales and profits.

Rental Income

Rent recieved from your property that generates your cash inflow.

Interest or other investment source

Certain investment generates like dividends, interest etc.

your total monthy cash inflow is the amount of comes into your accounts.

Cash Outflow: Money Going Out

Cash outflow is money is goes out from your account.

Examples:

  • Rent
  • Groceries
  • Electricity bills
  • Transportation
  • Loan Payment
  • Insurances
  • Shopping
  • Enterainment
  • Subscriptions
  • Investment and saving transfers

Not every cash outflow is a bad things.

Example:

Transfer to your investment from your saving account but it is build assest for your future.

Positive Cash Flow Vs Negative Cash Flow

there are only two cashs flow.

Positive Cash Flows

you have positive cahs flows when more money comes in than money goes out during that financial period.

Example:

Income: ₹50,000

Outflows: ₹30,000

Cash flow:₹20,000

That ₹20,000 is your positive cash flow and can used for saving, investment, use to make other assets.

Negative cash Flow

Negative cash flow is when your money goes out more than your money comes in your fiancial period.

Example:

Income: ₹50,000

Outflows: ₹55,000

Cash flow:₹-5,000

If this happen regularly month after month then you required use your saving, investment and other debt or borrow money.

Once occasionally negative cash flow moneth it not concern. But bigger concern when it happened repeated onth after month of negative cash flow.

How to Calculate Your cash Flow?

Cash Flow = Total Cash Inflows – Total Cash outflows

Example:

Salary: ₹50,000

Freelancer income: ₹5,000

Total Inflow: ₹55,000

Your monthy outflows are:

Rent = ₹12,000

Food = ₹7,000

Transport = ₹3,000

Bills = ₹3,000

Enterainment = ₹2,000

Other spending = ₹3,000

Total Outflows: ₹30,000

₹55,000 – ₹30,000 = ₹25,000

Your toatal monthy Cash flow is +₹25,000.

Cash Flow Is Not the Same as Income

Income tell you ho much money you earn or recieve.

Cash Flow looks ar both the money coming in and money goes out.

Example:

Your Earning ₹50,000.

But you spend ₹45,000.

Your income is:

₹50,000

Your remaining cah flow is ₹5,000.

Knowing your income alone doesn’t tell you how much money you actually have avilable after your otuflows.

Cash Flow Is Not the Same as Profits

The word “Cash flow” is aslo commonly used in business.

A business might make a profit on paper but still have cash floew problems if customers haven’t paid yet or if large bills need to be paid immediately.

Simple concept for personal finance

Cash flow focus on the movement and avilability of money.

How to Improve Your Cash Flow

If your cash flow regulary tight, you genrally have borad options:

Increase money Coming In

Here are some practical steps:

1. Track Your Money

For one month, recoed your every cash inflow and outflows.

you may unnecessary expenses that you might not aware of.

2. Reduce Unnecessary Expenses

Look At subscriptions, impulse purchases, eating out,shopping and optional spending.

You have to eliminate your enjoyable expenses.

you have to just have aware of where your money goes.

3. Plan for Irregular Savings

Some expenses don’t happen every month.

Examples:

  • Annual Insurance premium
  • Repairs
  • Festivals
  • Travels
  • Schools fees
  • Property expenses

Ste money aside ahead of time so you get disrupt your monthy cash flow.

4. Build an Emergency Fund

An Emergency fund can helps you handle your unexpected expenses without immediately relying on expensive debt.

5. Increase your Income

You could potentially increase your cash inflo. doiung freelancing work, rent a you own things, buying assets and learning new skills and many more ways to increase your cash inflows.

A Simple Monthy Cash-Flow Table

CategoryAmount
Salary₹50,000
Other income₹5,000
Total inflow₹55,000
Rent & bills₹15,000
Food₹7,000
Transport₹3,000
Entertainment₹2,000
Other expenses₹3,000
Total outflow₹30,000
Cash flow₹25,000

A Simple speedsheet is enough.

What Should You Do With Positive Cash Flow?

If you consistently have money left over, don’t le it disappear withour plkan.

You can surplus between:

  • Emergency plan
  • Short-term goals
  • Debt Repayments
  • Lifestyle spending
  • Long-terms investment

The ridht between financial goals and situations.

What If Your Cash Flow Is Negative?

Don’t Panic.

Start by identify why it’s negative.

Ask:

  • Are my essential expensive too high?
  • Am I spending too much on wnarts?
  • Di i have large debt repayments?
  • Can I increase my income?
  • Aim I spending without tracking?

Once you know your reason, start appropriate step toward the solutions.

FAQs

WHat is Cash Flow in Simple words?

Cash flow simply means that movement of money coming in and out of your finances.

What is Positive Cash Flow?

Positive cashs flows when more money comes in than money goes out during that financial period.

What is Negative cash Flow?

Negative cash flow is when your money goes out more than your money comes in your fiancial period.

How Do I calculate cash flow?

Subract your total cash outflow from total cash inflow.

Is Saving money part of cash flow?

Moving money into saving is and utflow from your spending account, but it is still remains your money becaome part of saving.

Link this article to:

What Is Income? A Simple Guide to Understanding Your Money

What Is Income?

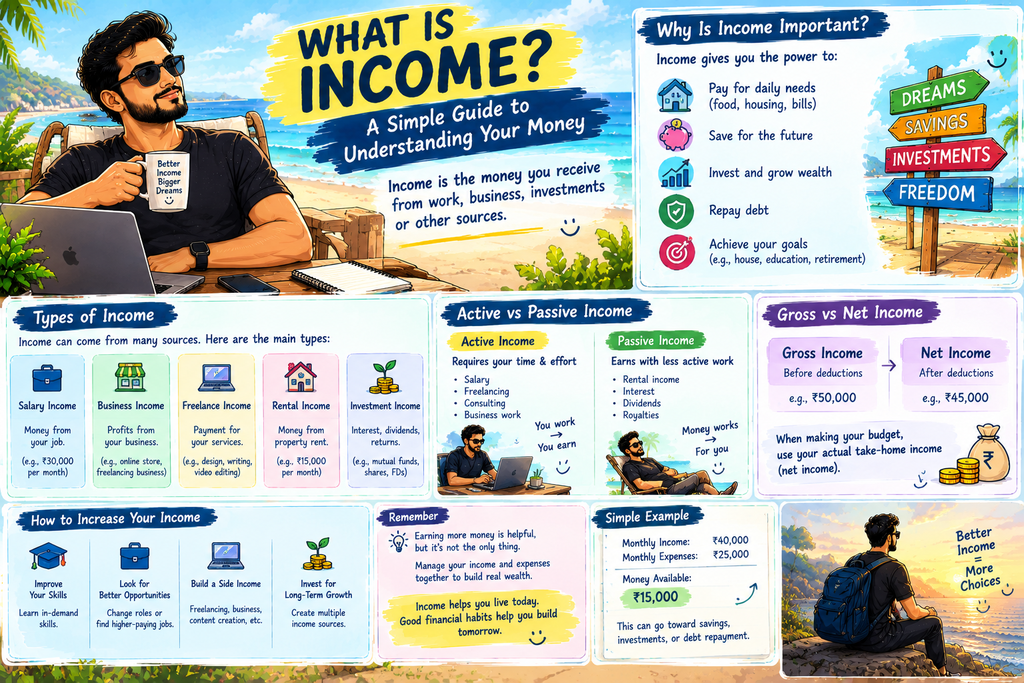
Income is the money you receive from work, business, investments or other sources.

In simple word, Money that comes into your pocket or bank account.

Example:

30,000 per month comes to your bank account as salary by doing job in a company. So, this 30,000 is a income source of yours.

But only salary income is not a limit.

You could also receive money from business, freelancing, rent, Investment or other resources.

Understanding your income is the first steps towards managing you money properly.

Why Is Money Important?

Income provides the money you use to pay for day to day life and future goals.

Your income in:

  • Pay for food gorecies
  • Rent
  • save money
  • Invest for future
  • Build an emergency fund
  • Vacation
  • achieve financial goals
  • travels

Simple step of personal finance:

Income – Expenses – Savings – Investments – Wealth

Different Types of Income

Income has many different source:

1. Salary Income

Salary is money you earn from your active work.

Example:

Monthy Salary = ₹40,000

It is easier to plan a budget. if you get salary every monthy way.

2. Business Income

Business income is money came from running a business.

Example:

Let’s say someone started a online store 1 year a old and makes around ₹40,000 in sales.

Sales are not same as income or expenses.

If your business spends ₹15,000 on products, delivery, advertising and other cost the amount left after expenses are very smaller.

This is why business owners need to understand both incomes and expenses.

3. Freelance Income

Freelancers earn money by providing a service to clients for single time or multiple times sometimes.

Examples:

  • Graphic design
  • Writing
  • Video editing
  • Programming
  • Consulting

Freelancing income changes every month to month.\

4. Rental Income

If you own any house or porperties and rent it to someone , the rent comes to you is rental income.

Example:

Monthy Rent =₹13,000

It can be residential or commerical property. If you multiple property it is good source of income.

5. Investment Income

Investment can potentially generate through thing such as:

  • Dividend
  • interest
  • rental income
  • buy low and sell high

Investment returns are not guarnteed and amount can vary after taxes reduced on your investment.

Active Income vs Passive Income

Active Income

Active income comes from where you give your time or skills. Active owrking on it to earn.

Example:

  • Job
  • Freelancing Consulting
  • Business work

You work and recieved money in return.

Passive Income

SOme income work ccontinues for 24 hours dily without your active involvement into it after it is established.

Example:

  • Certain rental income
  • Interest
  • Dividends
  • Royalties
  • online store

Passive income not fully automated, it is required some work time to time.

It is required some time updation, omgoimg management.

Gross Income vs Net Income

Gross Income

Gross income that earn amount earned before deductions.

Example: ₹40,000

Net Income

Net Income is the amount you earn after applicable deductions.

Example:

  • Gross Salary: ₹40,000
  • Deductions: ₹5,000
  • Net Income:₹35,000

When you creating budget always keep in mind make a budget on net income.

How Can You Increase Your Increase?

There are sevral ways to increase your income

Improving your skills

Learning valuable skills can increaase you earning potential.

Example:

  • Technology
  • sales
  • design
  • fiance
  • comminication

Ask for Better Opportunities

You may increases your salary by changing roles, taking on project or additioonal responsibiltiies or finding better opportunity.

Build a side income

You could potentially earn additional money through freelancing, small business, digitla products, content creation or legalimate works.

Build Long Investment

As time goes, invetemtns may create additional income of retuns or income.

Long term investment work on there on own by time into years and years.

Investing involves risk into it, it is not a gurantneed income.

The Goal Isn’t Just to earn More

Earning more money is useful, but just earning more alone doesn’t automatically create wealth.

Imagine:

Person A earns ₹50,000 ans spends ₹48,000.

Person B earns ₹40,000 and spends ₹30,000.

Person has left ₹10,000 left and less erning saving rate is more.

This is why income important but saving and investemnt also most important.

FAQs

What is Income in simple words?

Income is the money you receive from work, business, investments or other sources.

Is Salary the same as income?

Slary is one types of income. income can be many more types of incomes.

What is Gross Income?

Gross is a amount before deductions.

What is Net income?

Net income is amount after applicable deductions.

How can Increase my income?

Learning valuable skills can increaase you earning potential.

Example:

  • Technology
  • sales
  • design
  • fiance
  • comminication

Link this article to:

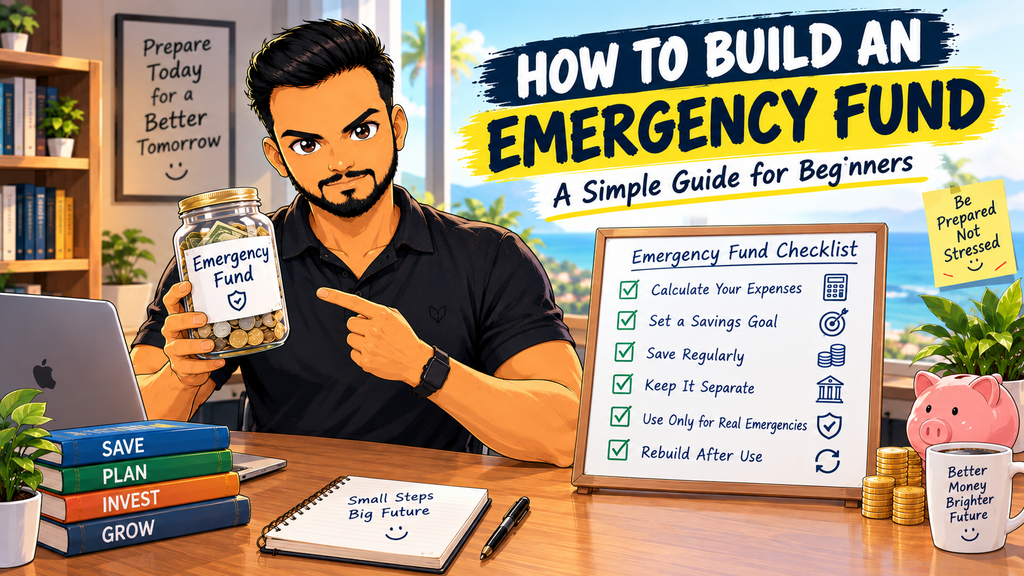
How to Build an Emergency Fund: A Simple Guide for Beginners

How to Build an Emergency Fund: A Simple Guide for Beginners

Imagine your car nneds arepair, uneexpected medical expenses ot your income stops for a while.

These situation cann be stressful especially when you have no money keep a side.

An Emergency fund gives you fiancial safety net for unexpected expenses.

It helps you to manage difficult situation without depending on loans, credit cards or any other borrowing products.

The good news is that you do not required larger salary to start. Even with small amount saved with regularly help you to build financial security.

Before we further go to in this article go check earlier related to Article

What Is Emergency Fund?

In this article, you will learn how to build an emergency fund, how much you have to save, where to keep it and how to start from zero.

What Is Emergency Fund?

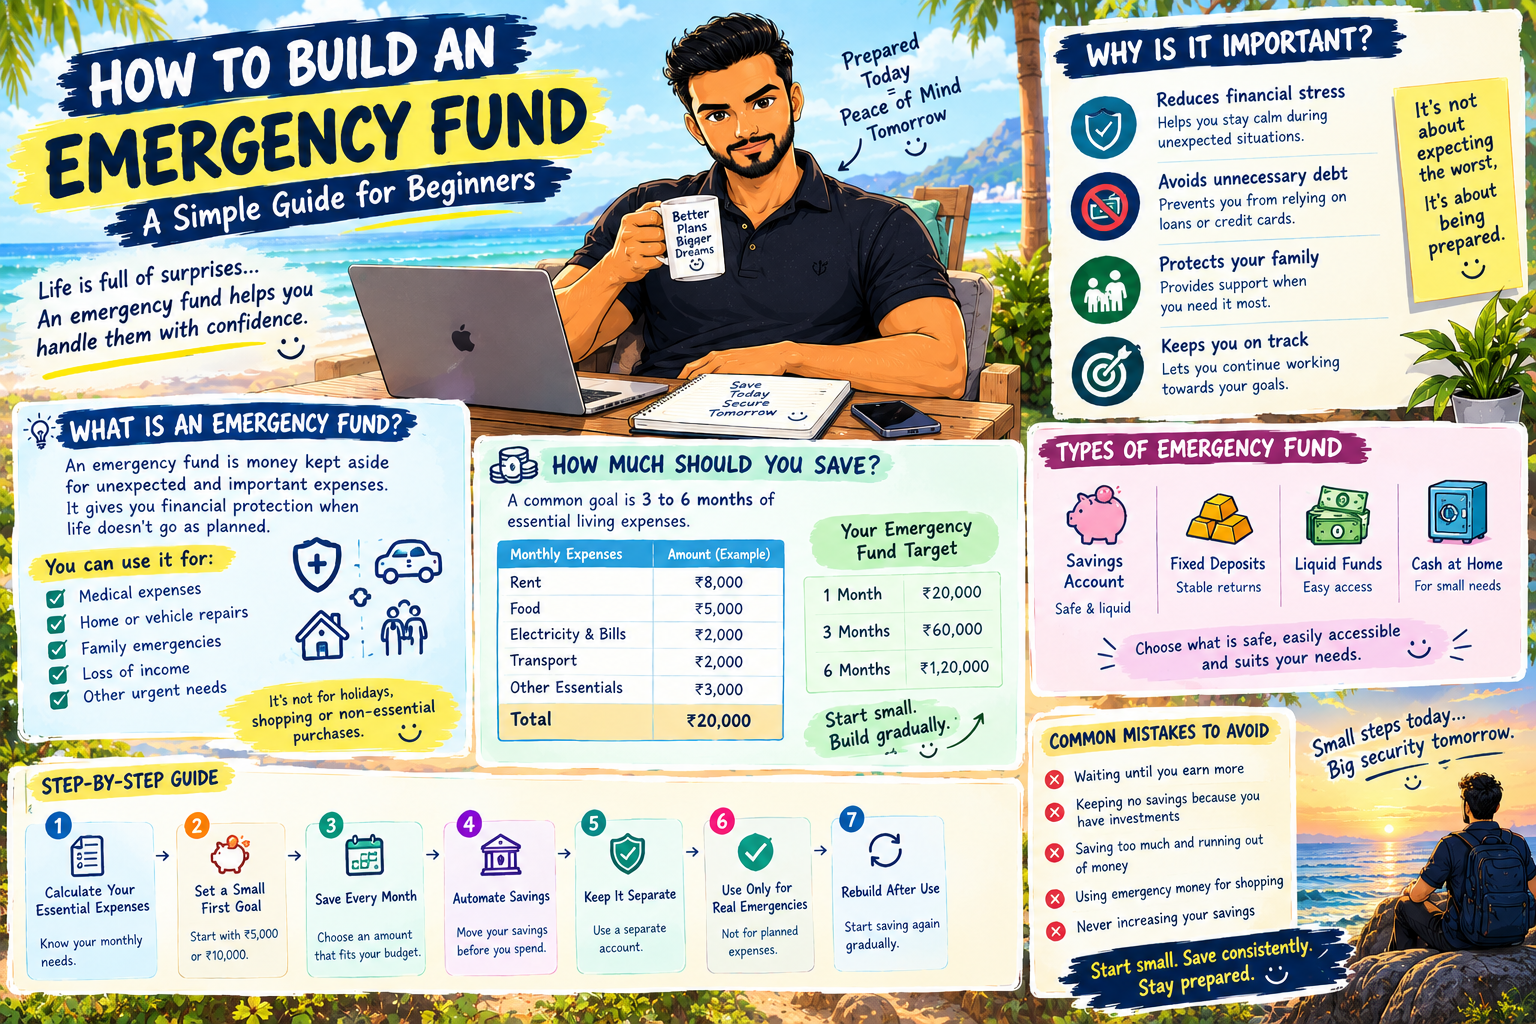
AN Emergency Fund is money that kept aside specifically for unexpected expenses and important expenses.

Example:

  • Sudden medicial expenses
  • essential home repairs
  • Unexpected Travel for family emergency
  • Temporary loss of income

The Purpose is clear if any unexpected event occured the money should be ready.

An emergency fund is different from money is save dfor like vacation, luxury gadgets, and shopping. those are comes in planned purchases. Emergency savings are meant to protect you when life does not go according to plan.

Why is an Emergency Fund Important?

Without emergency fund , an unexpectes expenses can disturb your entire monthy budget.

Last month you earn ₹40,000 ans suddenly ₹22,000 you get a home repair in monsoon and in this wheather you can not postponed. If you have no saving, you may need to borrow money or use a credit card.

But if you already have an emergency fund, you can manage the expense without any new debt.

An emergency fund can help you to:

  • Protect your monthy budgets
  • reduce financial stress
  • avoid unnecesaary debts
  • continue works towards to your financial goals
  • Stay prepared for unexpected expenses

Saving for emergency is do noit mean to inviting the unexpected events, it means be prepared for it.

How Much Emergency Fund Should You Have?

A common goals is save up to 3 to 6 months of essential living expenses.

Your target depends on your income, expenses, family responsibilities and financial stability.

Example

Suppose your essential monthly expenses are:

ExpenseMonthly Amount
Rent₹8,000
Food₹5,000
Electricity and bills₹2,000
Transport₹2,000
Other essential expenses₹3,000
Total₹20,000

Your emergency-fund target could be:

TargetAmount
1 month₹20,000
3 months₹60,000
6 months₹1,20,000

If you starting with zero do not pressure to save large immediately. start with small amount and build gradually.

Building an emergency fund helps you prepare for unexpected expenses and protect your financial future.

Step 1: Calculate Your Essential Expenses

Before decide how much to save, understand how much money you needed

Focus on your expenses for basic living:

  • Rent or house costs
  • grocies
  • electricity
  • transportion
  • Loan payments
  • insurance Premiums
  • Essential family expenses

you do not need to include every shopping expense

Your emrgency fund should cover what you need to surivive. not everything you normally spend.

Step 2: Set a Small First Goal

If you haveno emergency savings, start with e realistic target.

Example:

First Goal:₹5,000

Once you reach ₹5,000 contiue towards:

₹15,000 – ₹25,000 – ₹35,000 -₹55,000 – 3 motnhs of expenses

Smaller saving milestone make goal easier to manage.

Smaller amount saving than 0 saved.

Step 3: Decide How Much to Save Every Month

For example:

Monthly SavingTime to Save ₹30,000
₹1,00030 months
₹2,00015 months
₹3,00010 months
₹5,0006 months

The Important things is to save consitently, even amount is small.

Step 4: Automate Your Savings

One of the easiest ways to builds meergency fund is to save before spend it.

You can:

  1. Recieve your salary
  2. transfer to another saving account
  3. keep remaining to monthy expenses

Example: ₹35,000 and decide to save ₹5,000 towards every month saving transfer to another saving acccounts.

this habits helps you to build a habits.

Step 5: Keep Your Emergency Fund Separate

Keep emergency fund in separate account can make easier to avoid spending it accidentally.

THe most Important Feature are:

  • Easy access when needed
  • Low risk
  • Clear separation from daily expenses
  • no unecessary withdrawal ristrictions

Your emergency fund for safety and access nto chasing high returns.

Step 6: Use Your Emergency Fund Only for Real Emergencies

Before withdrawing money ask yourself:

“Is this expense unexpected, necessary and difficult to postpone.”

Genuine Emergencies:

  • Urgent medical emergencies
  • essential repair
  • sudden loss of income
  • important family emergency

Not an Emergency:

  • Buying a new phone
  • shoppinmg during a sale
  • eating out
  • a planned holiday

Step 7: Rebuild Your Fund After Using It

Sometimes you may to use your emergency savings. That ism exactly whta you created it.

After using the money:

  • Check how much remains
  • Calculate the amount you use
  • Restart your monthy savings
  • Rebuild the fund gradually

Rebuild your fund will easy this time because you have now habit of saving.

Using your emegency fund is not a failur. Using it for genuine emergency means it doing it jobs.

Common Emergency-Fund Mistakes

1. Waiting Until You Earn More

Many people think they will start saving after getting better salary.

But saving from ₹500 or ₹1000 todat can help you build a habit.

2. Keeping No savings because you have investments

Investement and emergency fund are build for different purposes.

Your emergency fund is for sudden unexpected expense when you need in liquided immediatelt and while investment is for long term financial goals.

3. Saving too much and running out of money

Your saving should be realistic.

If you save so muchthat you cannot manage your monthy expenses, it may not available when you really needed it.

4. Using Emergencies Money for Shopping

If you spend your money from emergency-fund for unncessary expenses purchase or shopping, it may not available when actually need the most.

5. Never Increasing Your Savings

As your income inreases, consider to increase your saving in emrgency funds.

For Example:

if you save today ₹1,000 oer month you may increase your saving ₹1,500 to 2,500 when your salary increases.

How to Build an Emergency Fund From Zero

If you start with no saving, follow this simple steps plan:

Month 1: Understand Your Expenses

Track your financial expenses and decide on realistic saving amount.

Month 2: Start Saving

Save your chosen amount every month, even if it is small.

Month 3: Reach Your First Milestone

Try to Your first ₹5,000 or ₹10,000.

Month 4-6: Continue Building

Keep saving regularly and avoid unnecessary withdrawals.

After that: Work Towards 3-6 months

Once you have build a basic emergency fund, contiue building it for long term goals.

The goal is progres not a perfection.

FAQs

How much emergency fund should a beginner have?

A beginner can start with ₹500 or ₹10,00 per month and gradually increase saving for gradually 3 to 6 months essential expenses.

Can I build an emergency fund with a small Salary?

Yes. Start with an amount that suitable from our budget and increase by time passes. Increase your savings when your salary rises.

Should I invest my emergency fund?

Emergency money should priorities safety and accessibility. avoid high risk instrument for money may need urgently.

Can I use my emrgency fund fora planned expense?

It is better create another saving plan for this types of purchasesso your emergency fund do not get disturbed or available for unexpected events.

What if I have debt and no savings?

You can start with small emegency fund while working on your debt.

The right balance depends on your interest rate, expenses and financial situation.

Link this article to:

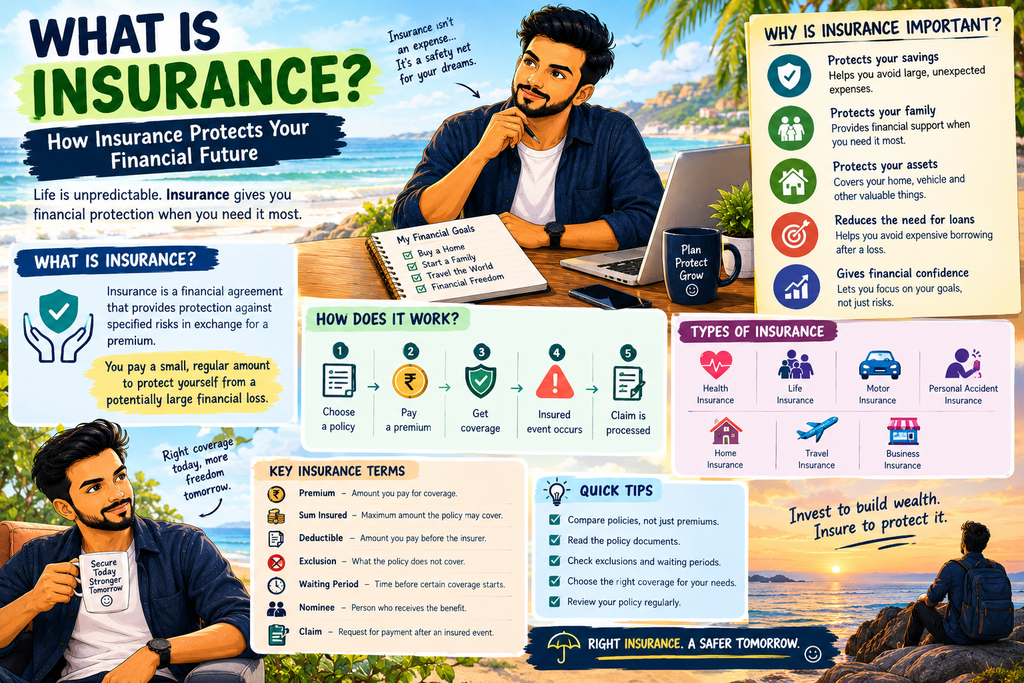
What Is Insurance? How Insurance Protects Your Financial Future

What Is Insurance? How Insurance Protects Your Financial Future

Spending years building your savings, investment and weath, suddenly emergency medicial, accident or family crises create big financial impact in your life.

Without any protection of your financial only one medicial or one unexpected emergency amaay to wipe out enitre saving and your investment.

This is where insurance is important.

Insurance helps you to portect your money from crisis or financial unnecessary debts on you.

You pay permium to a company and company provide financial coverages according to your terms.

Insurance cannot prevent every problems, but minimize your fiancial damage caused by unexpected events.

it this article we wil understand what insurance means , how it is works and types of insurance and how choose suitable insurance.

Table of Contents

What Is Insurance?

Insurance is financial agreement that provides protection againstspecified risks in exchange for preminum.

In simple words:

You pay a small, regular amount to prodect youself from unexpected large financial loss.

Example:

You may pay health insurance premium every year. the insurance company may pay egible all expense according to your policy.

How Does Insurance Work?

Insurance works 5 simple steps:

1. You choose a policy

tou selct type of protection you need, such as health, life or vehicle insurance.

2. You pay a premium

a Premiunm is a amount you pay for keep active policy.

It may be paid monthy, or yearly depends on the policy.

3. The policy provides coverage

The insurance company agrees to to cover your speciified risk under the policy.

4. An insured event occurs

Example:

  • The policyholder dies during policy period.
  • Vehicles damage in a accident.
  • Medical expense cover at hospitized.

5. A claim is processed

The Policyholder or nominee submit a required documents. If the claims get approved the isnurar get pay as per policy conditions.

What Is Sum Insured?

The sumInsured is the maxmium amount an insurance policy may cover for particular insured risk to the policy terms.

Example:

if you have health insurance suminsured upto 5 lakhs, the policy may cover eligible medical expense upto that amount.

Actual Payment may depends upto:

  • Deductibles
  • Sub-limits
  • waiting period
  • approved treatment costs
  • Remaining coverage

Alwys read the policy documents before buying policy.

What Is a Premium?

A Premium is a amount you pay to an isnurance company for coverage

Premium amount depand on factors like:

  • Age
  • Health condition
  • Coverage amount
  • Policy duration
  • Type of insurance
  • loacation
  • Occupations
  • Previous claims(if any)
  • Lifestyle

the most important factor is whether the coverage suit as per needs.

lower premium doe not means makes a better policy.

What Is Deductible?

A Deductible is the amount you must pay yourself bedore the insurance company begins paying eligible expenses.

Example:

  • Hospital bills: ₹1,00,000
  • Deductible: ₹10,000
  • Egible amount paiud by insurer: ₹90,000

The actual calculation depends on policy

A higher deductible may reduce the premium but it also means you pay more from your own pocket during claims.

Types of Insurances

The most common types of insurances:

  1. Health insurance
  2. life insurance
  3. Motor insurance
  4. Personal accident insurance
  5. Home insurance
  6. Travel insurance
  7. Business insurance

1. Health Insurance

Health Insurance helps cover medical expense according to your medical terms.

It may coverage for:

  • Hospitalisation
  • surgery
  • cetain treatments
  • Pre and Post hospitization expenses
  • Ambulance expenses

Why Is Health Insurance Important?

Medical expense can be unpredentable and expensive.

A suitable health policy protecct you from heavy expensive bill and your savings.

What to check:

  • Sum insured
  • Networks hospital
  • Waiting period
  • Room rent limits
  • Co-payment
  • exclusions
  • claim settlement ratio
  • Renewal conditions

2. Life Insurance

Life isnurance provides fiancial protection to the nominee if the insured person dies during policy peiod.

it is important for people who have:

  • Dependents
  • Family pesponsibilities
  • Children education goals
  • A spouse who lies on their income

Term insurance

Term life prvide life coverage for a specfied period.

it genrally focus on protection rather than saving or investment.

When choosing insurance, consider:

  • Number of dependents
  • future education cost
  • policy duration
  • Premium affordability
  • Income replacment needs

3. Motor Insurance

Motor isnurance protects against certains risk related to your vehicles.

it may covers:

  • Accidental damages
  • fire
  • theft
  • third party liability
  • Natrual disasters

Veicle repairs and third party claims can create signifiant expenses. motor insurance helps reduce the financial impact of covered events.

Before puchasing compare:

  • third party coverage
  • own coverage
  • isnured decaled value
  • deductible
  • add on covers
  • claim process
  • claim ratio
  • network garages

4. Personal accident Insurance

Personal Accident isnurance may provides fiancial benfits

for specfied accential or death such as:

  • Accidental death
  • perment diabities
  • Partial Diability
  • Tmeporary Diability
  • Accidental related Expenses

This type of insurance can be useful beause of accident may affect your income and your ability to work.

5. Home Insurance

Home insurance may portect your house or belonging against certains risks.

it may Cover

  • fire
  • theft
  • natural disaster
  • structural damage
  • household
  • certain personal liabilities

Home owners and tenants may nedd different types of policies.

6. Travel Insurance

Travels Insurance may provide protection during domestic or international travels.

Possible benefits include:

  • Medicial Emergencies
  • trip cancellation
  • loast baggage
  • travels delays
  • passport loss

Coverage differs between policies and destinations.

7. Business Insurance

Business insurance helps protect businesses aganist certain fiancial risks.

It may covers:

  • Property damage
  • employee relted risk
  • theft
  • equipment damage
  • business interruption

the right policy depends on risk and size of the policy.

Insurance vs investment

Insurance and investment serve different purposes.

FeatureInsuranceInvestment
Main purposeFinancial protectionWealth creation
Primary benefitReduces financial riskBuilds wealth over time
ExampleHealth insuranceMutual fund
Return expectationProtection according to policyPotential financial growth
Main focusRisk managementLong-term returns

A common financial mistake is buying a product only because it promises both insurance and investment without understanding the costs, returns, and coverage.

The right choice depends on your goals and financial situation.

Why Insurance Is Important for Financial Planning?

Insurance is important of complete fiancial plan because it protects the waleth tou are building.

1. Protects your savings

A major medical bill or accident can reduce your savings.

2. Protect your Family

Life insurance helps dpendents manage expense if primary earner dies.

3. Protect your assets

Motor or home insurance can reduce the fiancial impact of certain financial damages.

4. Reduces the needs for expensives loans

Insurance may help you avoid borrowing after an unexpected events.

5. Provides financial Confidence

Proper coverage helps you to focus on our long-term goals without worrying and financial emergencies.

How Much Insurance Do You Need?

There is no single amount suitable for everyone

Tour coverage should depend on:

  • Age
  • SIncome
  • Family Reponsibilities
  • Saving
  • Health risk
  • No. Of dependents
  • Futuer financial goals
  • Existing Insurance coverage(if any)

For Life Insurance

Amount your family need to manage

  • Daily expense
  • loans
  • education
  • housing
  • Future financial goals

For Health Insurance

  • Local hospital cost
  • family size
  • Medical history
  • Employer coverage
  • Rising healthcare cost

Review the coverage when your income, family or repsonsibilities change.

Employer Insurance vs Personal Insurance

Some employer provide health or life insurance benfits

Employer coverage can be useful, but it may not always enough.

Employer Insurance

Advantges:

  • affordable
  • convenient
  • may cover employee or dpendnets
  • premium may be partly paid by the employer

limititation:

  • Coverage may be limited
  • policy terms may not controlled by you
  • policy ended when you leave the job

Personal Insurance

  • you contol your policy
  • you choose your suitable sumisnured
  • it may provide lomg term contiunity

Important Insurance Terms

Policyholder

The Person who owns the Insurance policy.

Insured

The person or asset covered by the policy.

Nominee

The person named to receive eligible benfitsunder policies.

Claim

A request made to the insurer for payment or cover age bills after unexpected events.

Exlusion

A expense that policydo not coverge under the policy.

Waiting Period

A period that policy will cover not available.

Co-payment

the percentage of an alegible claims paid by policyholder.

Grace Period

Additional time allowed to renwal the policy after a due date subject to policy terms.

Claim settlement

The process through wjich an insuruer reviews an dpays an approved claim

Common Insurance Mistakes

Buying only the cheapest policy

A low premium may come with limited coverage and less benefits.

Not reading the policy documents

always understand what is covered and what is not covered.

Hiding Important information

Incorrect or incomplete information can reduce your claim.

Buying too little coverage.

Insufficient coverage may not protect you when you needed the most.

Ignoring policy renewal

A policy may lapsed if premium will not paid as policy period.

Depending entirely on employer insurance

Your coverage may change when you change jobs.

buying isnurance only for tax benefits

Tax benefits should not be mains reason to buy insurance policy.

Not Reviewing coverage

Your insurance may required after marriage, children, new loan or increase salary.

How to Choose the Right Insurance Policy

Step 1: Identify your risks

Think aboutthe risks that could create fiancial problems.

Step 2: Check your existing coverage

review your employerinsurance, existing policy and government benfits.

Step 3: Decide the rquired coverage

estimate the fiancial support your family and asset may need.

Step 4: Compare policy terms

Compare:

  • Coverage
  • Premium
  • exclusion
  • deductibles
  • waiting period
  • claim process
  • claim settlements ratio od precentage

Step 5: Read the policy documents

Do not rely on written or vernal promisies.

Step 6: Review the policy regularly

update your cpoverage when fiancial repsonsibilities changes.

FAQs

Is insurance necessary for everyone?

the types and amoutn of insurance dpendon your risk, income, assets and responsibilities. most people should cosnider protection aginst major financial risks.

Is health insurance important if i am young?

Yes. health emrgencies can happen to any age and buying coverage earlier get more benfits.

Is Life isnurance necessary if I have no dependents?

You may have less immediate need for life insurance, but your situation changes in future . cosnsider future responsibilties, loans , family.

Is Insurance an investment?

Insurance primarily provides protection. Some insurance ploicy parts gives investment but get more returns and very less coverage.

What happens if I Stop paying Premiums?

the policy became inactive or collapse depending on your policy terms.

Can I Have more than one Insurance Policy?

Yes. You may have mulitple policies but benfits and claims rules depend on the types of insurance and policy conditions.

Link this article to:

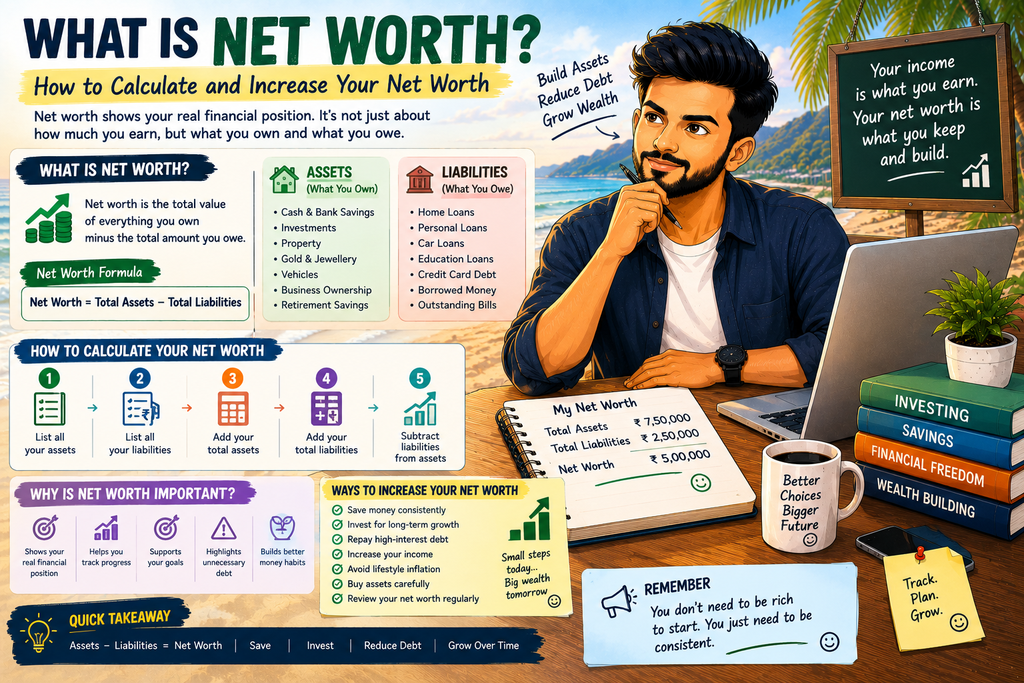
What Is Net Worth? How to Calculate and Increase Your Net Worth

What Is Net Worth? How to Calculate and Increase Your Net Worth

Many ask you simple to measure finacial situation:

“how Much money do you earn every month?”

But income just part of yolpur financial life.

A person earning 1 lakh per month may have higher loans and very less saving from salary. On other hand 50,000 rupees earning person saving more and spending less may havbe strong financial situation.

Net Worth shows your where are you at now, where your financial situation goes and whethere you closer to your financial goals.

In this article, we will talk about net worth how we calculate and simple way to increase it.

What Is Net Worth?

In simple words:

Net Worth means total amount of asset or everything that owns and subtract by with that amount of you owe money.

Net Worth Formula

Net Worth = TOtal asset – total liabilities

Asset is a that create value over time.

Liabilities are loans, debts and other money owe.

What Are Assets?

Assets are things that you own and create an value over time period.

  • Business
  • Cash
  • Savings
  • FDs
  • Investment
  • House
  • Gold
  • Retirements savings
  • Vehicles(use as business)
  • Stocks
  • Mutual Funds

Some asset may increase over a time , some may still maintain same value and some even loss value over a time.

What Are Liabilities?

Liabilities are financial hurdles that to stop your grow towards your financial goals. liabilities are like your money goes out of your pocket.

  • House loans
  • car loans
  • Personal loans
  • Education loans
  • Credit card
  • Buy – now – pay – later

Net Worth Can Be Positive or Negative

Positive Net Worth

You have more asset than liabilities.

Example:

  • Assets: 25 laks rupees
  • Liabilities: 6 lakhs rupees
  • Net Worth: 19 Laks rupees

Negative Net Worth

Your Liabilities is more than your asset.

Example:

  • Assets: 10 laks rupees
  • Liabilities:14 lakhs rupees
  • Net Worth: -4 Laks rupees

Negative net worth does not means you failed in you finacial life. it simply shows that your debt currently more than your assets.

The important thing is to create a plan to improve your financial situation.

Net Worth vs Income

Income that you earning every month.

Net worth is th wealth you have built adter subractinng debt.

FeatureIncomeNet Worth
MeaningMoney earnedAssets minus liabilities
MeasuredMonthly or yearlyAt a specific point in time
ShowsEarning abilityOverall financial position
Can increase throughSalary, business, side incomeSaving, investing, debt repayment
Example₹50,000 monthly salary₹8 lakh total wealth

Higher income can help you create wealth , but only if if you manage it wisely.

Why Is Net Worth Important?

1. it shows your real financial position

Your salary alone does not show how financialyyh strong.

your net worth show your real situation of your assets and debts.

2. It helps you track progress

You can calculate your net worth every six months or once a year.

3. It helps you set realistic goals

Knowing your currect s=networth makes you easier to plan:

  • buying a home
  • retirement
  • Chiildre’s education
  • Starting a business
  • Financial independence

4. It highlights unnecessary debt

If your liabilities increase quickly, your net worth maye be falling.

5. It encourages better money habits

Tracking net worth can motivates you to save more, invest reguylarly and repay debts.

How to Calculate Your Net Worth Step by Step?

Step 1: List all your assets

Writ down all everything you own that has financial value.

  • cash
  • FDs
  • Investment
  • Stocks
  • Mutual funds
  • Property
  • vehicles
  • Business assets

Use current realsistic value of your assets.

Step 2: List all your liabilties

Write down all your liabilities

  • House loans
  • car loans
  • Personal loans
  • Education loans
  • Credit card

Step 3:Add your total assets

Example:

  • Savings: ₹1,00,000
  • Investment : ₹3,00,000
  • Gold: ₹4,00,000
  • Vehicle: ₹1,00,000

Total Assets: ₹9,00,000

Step 4: Add your liabilities

Example:

  • Personal loans:₹1,00,000
  • Credit card loans:₹10,000

Total Liabilities: ₹1,10,000

Step 5: Subract your liabilities from assets

₹9,00,000 – ₹1,10,000 = ₹7,90,000

Your Net worth is ₹7,90,000.

How to Increase Your Net Worth?

Increasing your net worth is simple doing two things:

  1. Increase your assets
  2. Decrease your Liabilities

1. Save money cosnsistenly

Saving is foundation of waelth creation.

Even small amount od money every month can help you to create:

  • Emergency fund
  • Investment capital
  • homw fund to buy
  • Debt repayment

The amount matters, consistency matter the most.

2. Invest for long-term Investment

Once you have suitable saving, consider to invest accordign your goals and risk tolercence.

Possible investment include:

  • Mutuals fund
  • stocks
  • Fds
  • PPF
  • Retirements savings

3. Repay High-Interest Debt

High-interest debt can rduce your net worth becuase it is increase your liabilities.

Priorities expensive Debts:

  • Credit card
  • Highe interest loans
  • Unncessary loans like gadget, home appliances.

4. Income Your Income

A higher salary can help you to more saving and invest more.

You can improve your income ny:

  • Learning new skills
  • Increase SIPs
  • Clear your debt by extra EMIs
  • Start a side hustle
  • Offer Freelanceing
  • Building onlime income
  • Increase emergency fund

The goal is simple to save more and invest more.

5. Avoid Lifestyle Inflation

Lifestyle inflation means increase as your expenses whenever your income increases.

Example: If your salary rises ny 10,00- do not spend it all.

Instead put in:

  • Investment
  • Debt repayments
  • saving
  • Necessary Lifestyle upgrading

6. Buy Assets Carefully

Ask yourself first before buying assets:

  • Will this items add value in my net worth?
  • Will I lose value quickly
  • Is a liabilities or assets as time passes?
  • Can i afford after living regular expenses?

7. Review Your Net Worth Regularly

Calculate your net worth evry six months or every once a year:

Track:

  • Total Assets
  • Total Liabilities
  • Investment Growth
  • Loan Repayments
  • Saving Progress

Regular Review helps you identify your problems early and make better decisions.

Does Buying a House Increase Net Worth?

A house can increase your net worth, but it depends on its value and remaining loans.

Example:

  • Home Value: ₹50 lakh
  • Loan Valuue remaining: ₹20 lakh

Your Home Equity is ₹30 lakhs.

That ₹30 lakh value will be include in your net worth.

Property Ownership includes like:

  • mainteance costs
  • taxes
  • insurance
  • interest paymenmts
  • Registrations costs

A Home evaluated based on your fiancial goals, affrodability and long term plans.

Should You Include Your Car in Net Worth?

Yes, A car is an asset because it has resale value.

tou should you a current market value in your net worth.

Example:

  • Car original Value: ₹13.50 lakh
  • Current resell value: ₹8 lakh
  • Loan Remaining: ₹4 lakh

₹8 lakh – ₹4 lakh = ₹4 lakh

Remenber that vehicle depreciate, it decrase it’s value over a time period.

Common Mistakes When Calculating Net Worth

Using the Purchase price of asset

Use the current estimated value instead.

Forgetting small debts

Credit card balance, and unpaided bills also be included.

Counting the full property value while ignoring the loans

Only ownership portion or equity contributes to net worth.

Including future income

Salary may increase in the future is not current asset.

Comparing your net worth with others

Proplr have different ages, responsibilities and goals.

Comapre your net worth is not good to every body

stop comparing.

Expecting rapid growth

Building wealth usually takes time and consistent efforts.

FAQs

What is a good net worth?

There is no such single number good for everyone. A Suitable net worth depends on goals, saving, investment, debts.

Can I have a high Income but low net worth?

Yes. High Incopme, large loans and low savings can results in negative net worth.

Is a House an asset?

Yes. house is a asset., but home loan suvstrat from calculate net worth.

Should I include nmy Pesronal belongings?

You can added it in your net worth, but ir’s has to some market resale value. Keep realistic amount to calculate.

How often should I calculate net worth?

It every six month or once a year is good. in short new worth does to sky rocket.

How can i increase net worth quickly?

there is no such guaranteed shorcut. quick scheme makes you into scam.

Remember:

Your income is what you earn. Your net worth is what you keep and build.

Link this article to:

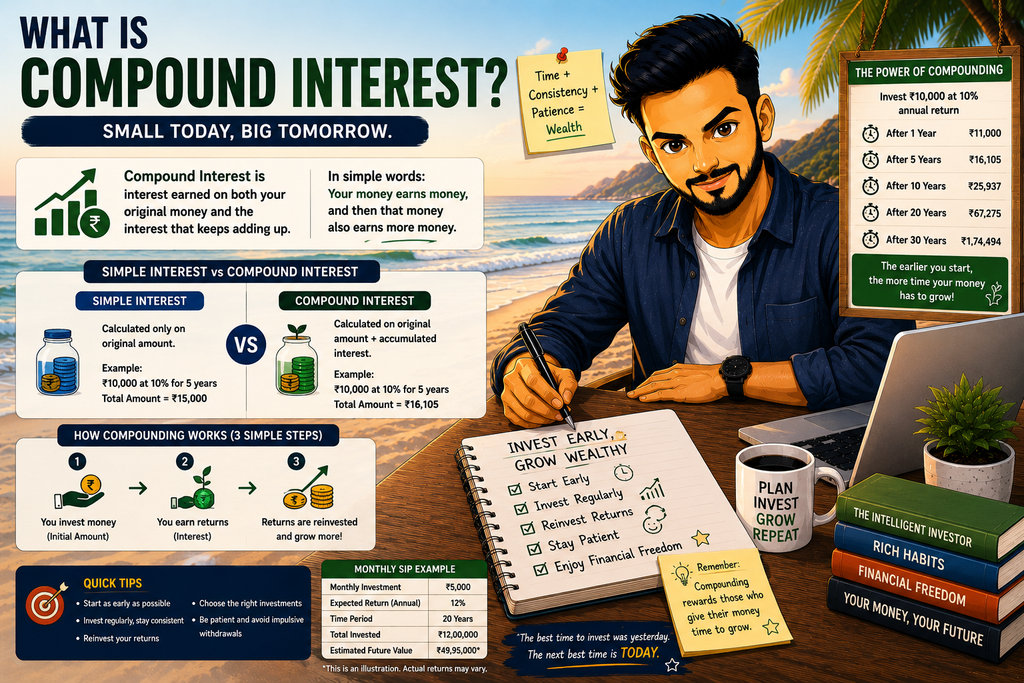
What Is Compound Interest? How Your Money Grows Over Time

What Is Compound Interest? How Your Money Grows Over Time

havew you ever wondered how to smallamoutnof money can become bigger amount over peroid of time?

The answer is often compounf Interest.

Compound interest means the money invest in asset make a return on your money, and that returns on money earn more returns. this crates powerful growth over long peroid of time, which konown as Power of compounding.

You do not always need huge amount of money to start investing. it matters of time so start early, regularly keep investing to maintain compound effect keep this money untouch for konger peroid to make difference larger amount.

In this article, we will understand compound interest in simple words, learn how it works how it is important for your future.

What Is Compound Interest?

Compound interest is the interest earned from its orginal money and from return make more return in it.

In Simple Words:

Your money eanrs money and then that extra money also start making money.

For Example Suppose you invest ₹10,000 and earn 10% interest in that one year.

  • Orginal Invest: ₹10,000
  • Interest earned: ₹1,000
  • Total after one year: v 11,000

In Secodn Year, with same amount of invest and same interest earned at 10% per year.

  • Investment at beginning after first year: ₹11,000
  • Interest earned second year: ₹1,100
  • Total After two year: ₹12,100

Your interest is now earn interest itself.

that is power of compounding interest.

Simple Interest Vs Compounding Interest

FeatureSimple InterestCompound Interest
Intterest Claculated onInvest amountInvest and Accumulated return
GrowthslowFaster over time
Interest on interestNoYes
Best understoodFixed interestgrowing money
Common usesome loans and basic calculatesaving, investment and deposits

Simple Interest:

Invest ₹10,000 at 10% annually for 5 peroid of time.

  • Interest every year: ₹1,000
  • Total Interest:₹5,000
  • Final amount:₹15,000

Compound Interest:

  • Final Amount Approx. ₹16,105
  • Interest earned amount Approx ₹6,105

In this example it is just smaller difference but over peroid of time make larger numbers.

How does Compound Interest Work?

Compound interest work in three simple steps.

1. you invest or save money

You beginning with inital amount ₹5,000 or ₹10,000.

2. Your Money earns returns

Your Investemnt will earns interest on based market performence and product.

3. The Returns are reinvested

Insted of withdrawn the returns they remain invested earn more additional returns.

The Longer this process continues the more effect can become.

Why Time So Important?

The most powerful part of compound interest is time.

When you give your money to grow, your money will generate more additional returns.

Investment Period₹10,000 at 10% Annual Compounding
1 year₹11,000
5 years₹16,105
10 years₹25,937
15 years₹41,772
20 years₹67,275
30 years₹174,494

The Power of Starting Early

Starting Early can be more important than a investing larger amount.

For Example:

Person Amit:

  • Start invest ₹5,000 per month
  • Start at 25 years age
  • COntinues for 20 years

Person Vinit

  • Start invest ₹5,000 per month
  • Start at 35 years age
  • COntinues for 10 years

Both Invest same amount Amit has more time than vinit for compound for work.

The earlier you begin the more compound work itself.

Time is most valuable assets in investing.

Compound Interest and Monthy investments

Compound interest can become more powerful when you invest regularly.

For example:

₹5,000 every month for years with annual return of 12%.

  • Total Amount Invested: ₹12,00,000
  • Estimated final value: Approx ₹49,00,000
  • Estimated Growth: Approx. ₹37,00,000

This is just a example for you this return are guarantee for fixed returns and results change accordingly to markey perform or product.

Compound Interest in Mutual Fund ans SIPs

Many People experience through financial product:

  • Mutual funds
  • SIPs
  • Retirements fund
  • Recurring deposits
  • Reinvested in business profits

SIP does not give gurantee fixed returns. By Investing regularly and remains invested in long period of time, you get benefits of compounding interest.

Undertand your risk capacity before investing these all are market linked products.

Compound Interest Can Also Work Against You

Compound interest is not always work for you on positive.

It can also works against you in form of borrowing money.

when you keep unpaid debt for long time it’s works aginst you.

For Example:

If you keep a credit card and do not paid on time.

  • Interest may be added on outstanding balance
  • The larger loan amount the more interest will added.
  • It will difficult to repay
  • it’s may goes out of limit which can uncontrol after some sort of time.

THis is why Compound interest in work for you when you keep investment purpose and work against you when keep unpaided debt is increasing by time to time.

Let’s compound for your investment not against in debt.

How to Use Compound Interest to build Wealth?

1. Start as early as possible

Even a small investment can benefit in londer period of time.

2. Invest Regularly

Consistency helps you create great wealth over period of time.

3. Reinvest Your Returns

Avoiding withdrawn every returns If your goals is long term growth.

4. Choose investments Accvording to your risk

Understand difference between fixed returns and market retated returns.

5. Avoid unnecessary High-interest Debt

High Interest debt can reduce your ability of saving and invest.

6. Be patient

Compounding Interest Works slowly in the beginning. the Result become more noticable over time.

7. Increase your investment When your income grows

Annual Increase in your investment can improve your long term results.

Common Mistakes That Reduce the Benfits of Compounding

Start too late

Waiting for the perfect time can reduce the number of years your money has to grow.

Investing only when you have extra money

Regular invest is more effective than investing randomly.

Withdrawing rteurns Frequently

Removing your returns reduces for future money to grow.

Ignoring Fess and taxes

Investment cost and taxes can reduce your actual returns.

Taking too much Risk

A high expected return can comes with higher risk.

Never invest money without understanding the psoobility of loss.

FAQs

Is compound interest the same as simple.

no. Simple interest earn only fixed interest from orginal money invest. Compound interest helps you to earn interest and your interest more money from in it.

Is compound Interest Guaranted?

Compound interest are mostly market linked product so say its give you not fixed returns and there is not any guarantee of returns.

How Often can interest be compounded?

Interest may be compunded annually, half-year, in quarterly or according to the term od financial products.

Is compound interest good for investors?

Yes. Reinvested returns csn help investement grow over time. investemnt should in longer period time.

Can Compound Interest Increase Debt?

Yes. Upaid Debt can be increase in compound interest because increase may accumulate on orginal amonunt and interest.

What is best way of benefits from compounding?

Start Early, Invest regularly, reinvest in returns and remains patients.

Link this article to:

What Is an Emergency Fund? How Much Should You Save?

What Is an Emergency Fund?

Imagine you suddenly call from parent for medical .

Your vehicle required repair. your essential bills arrives. Urgent travel comes and your income stop for some issue in company payroll system.

No saving. id you don’t any saving . you go first for borrow money or use credit line for escape the situation.

This is why Emergency fund is first to do with your money.

In simple Words

An Emergency fund is money kept aside to help pay in unexpected but important and necessary expense.

Main purpose for this fund to safe guard from this emergency or unexpected situation.

Why Is an Emergency Fund Important?

Your regular income and expense cover your every month routine expense.

But our life don’t work on our fingertips.

Unexpected events brings unexpected expenses at any time.

Example:

  • Vehicle Repairs
  • Essential home repairs
  • Urgent Medical treatment
  • Temporary lost in source of income
  • unexpected Travel

Without emergency saving, you might go this creditors like:

  • Credit Cards
  • Personal Loans
  • Borrowing from relatives or friends
  • selling investments

Emergency fund can gives you mental peace and helps as another source of income.

It’s simple motive is to just prepared for unexpected events so you don’t has borrow money from others.

Emergency Fund vs Regular Savings

You might thinking like

Emergency fund is also saving money and regular saving also saving money

here it’s catch emergency fund only use in your difficult situation and regular saving we use in normal day to day life fund.

Regular Saving

  • buying phone
  • Holidays Trips
  • laptop
  • Education
  • Planned Purchase

Emergency Funds

  • urgent Medical Expense
  • Home Repair
  • Exam Fees
  • Family Resposnibility
  • Job Loss

Separate saving are just for not use money of emergency in normal life.

Howw Much Should You Have in a Emergency Fund?

There is no such exact amount for emergency funds.

Common point to keep in mind is to funds helps for 4 to 6 month up to 1 year essential expense.

Atlhough it is depends on your family responsibility and income etc.

Eesential Expense Like:

ExpenseAmount
Rent₹10,000
Food₹7,000
Household expense₹5,000
Transportation₹3,500
Other essential₹4,500
Total₹30,000

For Three Months

₹30,000 x 3 = ₹90,000

For Six Months

₹30,000 x 6 = ₹1,80,000

your fund should be around 90k to 2 lakhs. It may change for over peroid of time.

it not perfect amount it’s just a example.

your fund may because of:

  • chage in income
  • Increasing bills
  • Debt
  • Family responsibility
  • Unexpected purchase

What Are Essential Expense?

Expense that had to be paid even in your difficult situation.

This amount should be built for around 6 month to 1 year essential expense.

these include:

  • Rent
  • Essential home payment
  • Basic meals
  • Groceries
  • Electricity
  • Water
  • Gas
  • Internet
  • Fuel
  • Public transport card fees
  • Essential Vehicle checkup or top up
  • EMIs repayments

the goal is maintain your essential expense fulfill.

Do You Need ₹1 Lakh Before Starting?

NO.

this big common mistunderstanding.

If your target is to save upto 1 lakh to 1.5 lakhs it’s seems like impossible just by thinking of it.

Simple break into parts to saving as per situation:

First target: ₹5,000

Second target:₹10,000

Third Target: ₹30,000

Fouth Target:₹60,000

Final Target: 1,50,000

Don’t give target month to achieve.

Keep going as long as you can go to achieve your target.

Important is to start saving and kept built it and achieve it.

How to Build an Emergency Fund Step By Step?

Step 1: Calculate Your Essential Monthy Expenses

Start by Identify how much you need for basic Essential living expense

Example:

Essential Expense = ₹25,000 per month

Step 2: Choose Your Target

Target gives you destination of fund where to reach a goal.

Target = ₹1,00,000

Step 3: Choose a Monthy Saving Amount

decide your monthy saving amount

Monthy Amount = ₹5,000 Per month

consistency is key to build your emergency fund.

Step 4: Keep the Money Separate

keeping emergency fund separate day to day routine expenses.

Not to spend in:

  • buying gadgets
  • shopping
  • apps subscription

Small of routine spend will loss discpline in saving money.

Step 5: Increase Your Saving when it Possible

If your incoem increase or your expense same, Putting into emergency fund is a good decision for build better fund. It goes to wards future emergencies.

Where Should You keep an Emergency Fund?

Emergency Fund is diffrent from long term investment money.

Because you may required money in urgent, so accessibility ans stability is more important.

Depend on your circumstances, people commonlu conside option like:

  • saving account
  • liquid debt fund

key Question?

Can I access the money when I need it?

Is the money stable all time?

Emergency fund main purpose to just save and it is not give ighest return on investment.

As we say above, priority is to prepared for monye when you needed the most.

What Counts as an Emergency?

This is a most important question.

Not unexpected situation is a financial emergency.

Ask Yourself:

“Is this expense necessary, unexpected and difficult to handle using with normal saving money.”

Possible Emergencies

  • Urgent Medical expense
  • Essential home repair
  • loss of income
  • vehicle repairs

Not Emergencies

  • Buying new pone on lauched day
  • holiday trip
  • upgrade laptop
  • enterainement
  • impulse purchase
  • unwanted spending on bag
  • buying expepsnsive shoes

The main purpose to protect your money from everyday routine purchases.

What If You Have to Use Your Emergency Fund?

Using emergency money does not mean you failed in financial way.

exactly why you created it.

Example:

Emergency Fund ₹70,000

Unexpected cost ₹32,000

After Paying

₹70,000 – ₹32,000 = ₹38,000

Emregency fund done it’s job.

Even if you don’t reach to your target in between you have redeem your money without second thought you have take money money pay it.

that why we called unexpected expense.

restart or resume to built your emergency fund untill get achieve your goal.

Emergency Fund vs Investing

Emergency fund and Investing work for different purpose.

Emergency Fund

Main Purpose:

Finacial accessibility and Protection.

Long Term Investment

Main Purpose

grow your money over a long peroid of time.

Example:

If unexpected situation arise and you had to pay it just today you just ATM or Bank liquided your fund and pay it.

this for emrgency fund to work for it.

Now, You invest in long term growth long peroid of time if withdrawn you fund in this type of situation and asset value is low at that time you had to accept your loss.

This main reason to create or built first emrgency fund and then start investment on your money.

It also way of protecting your investment portfolio.

What If You Have Debt?

If you have debt, deciding how much to put in emergency fund or debt repayments.

let’s see some consider:

  • Interest Rate of the debt
  • Your income stability
  • Your existing no. of loans
  • debt at higher cost

For many people, emergency fund works as to repayment of debt, unexpected expense leads to additional debt.

5 Common Emergency Fund Mistakes

1. Waiting Until You can save a Large Amount.

Start with realistic amount or smallest you have.

2. Treating Emergency Money Like Spending Money

Your emergency fund should not go for shopping.

3. Taking too much Investment Risk

Emergency money may need urgent, taking unnecessary risk take away your money.

4. Forgetting About Income Loss

Dpending on your circumstances, it can works as your temporary income when you get loss your job.

5. Not Rebuilding after Using it

If you use part of your emrgency fund, stop rebuild your fund for future situation.

How long Does it Take to Build an Emergency Fund?

It depend how much you can save for it.

Example:

Target:₹60,000

monthy saving: ₹6,000

this takes you to ₹60,000 ÷ ₹6,000 = 10 Months

It’s all depend on your saving.

There is no time ristriction. Take as many as time to build it.

FAQs

1. What is Emergency Fund?

An Emergency fund is money kept aside to help pay in unexpected but important and necessary expense.

2. How Much should an emergency Fund be?

Common expected counting of essential expense of 6 month to 1 year.

But All depend on you cicumstances, responsibilty, income and expense.

3, Can I use my emergency Fund?

Yes. It name we had given to saving. it’s all about save to use for unexpected expense and once it is use. Start rebuild you fund again.

4.Can I start an Emergency fund with ₹1,000?

Yes. Staring with small amount gives you momentum and sense of safety. Increase you fund adding more money into it.

5. Should an Emergency Fund be invested in stocks?

Emergency fund is main prupose to stability and accesibility for unexpected expense. By puting in market gives you unstability and fluctation in value.

Link this article to: