What Is Risk vs Return? — Understanding the Relationship

What Is Risk vs Return?

when you invest money, two important ideas you should understand are risk and return.

  • Risk means the possibility that your investment may lose money or perform differently than expected.
  • Return means the money you gain or lose from an investment over period of time.

Risk vs return describes the relationship between the amount of risk you take and the potential return you may receive.

In simple Words:

Investments with higher potential returns often come with higher levels of risk.

However, Higher risk does not guarantee higher returns.

Understanding this relation ship can help beginners make informed investment decisions.
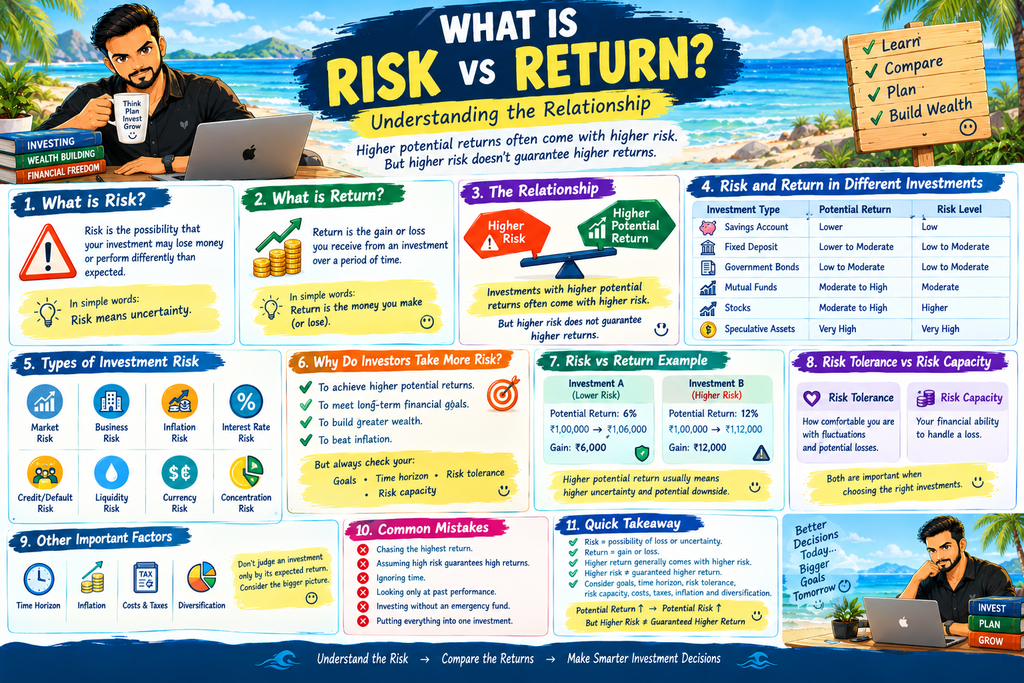
Risk and return: The Basic Idea

Let’s say you have ₹10,000 to invest.

You have several possible choices.

Investment TypePotential ReturnRisk
Savings accountLowerLow
Fixed depositLower to moderateRelatively low
Government bondsLow to moderateRelatively low
Mutual fundsModerate to highModerate
StocksModerate to highHigher
Speculative investmentsVery high potentialVery high

Actual risk and returns vary dpending on the specfic Investment, tim period market conditions and products.

The important idea is that you generally cannot expect high potential returns without accepting some possibility of loss or uncertainty.

What Is Risk?

Investment risk is the possibility that your investment may not produce the results you expected.

Example:

You invest ₹10,000 in stock.

Later, its value falls to ₹8,500.

Your investment has decreased by ₹1,500.

That is an example of investment risk.

Risk can come form many sources including:

  • Market movment
  • business problems
  • inflation
  • inetrest rate changes
  • default or credit problems
  • Lack og liquidity
  • Currency movemnts
  • Concentrationm in one investment

We discussed these different types of investment risk in the pervious article,”What Is Risk in Investing?“

What Is Returns?

Returns is th gain or loss you recieve from an investment.

Example:

You invest ₹10,000

After sometime, your investment becomes ₹11,500.

Your gain is:

₹11,500 – ₹10,000 = ₹1,500

Your return is:

₹1,500 ÷ ₹10,000 x 100 = 15%

So, your investment produced a 15%n return before considering applicable costs, taxe or other factors.

Returns can be:

Positive Return

you make money

  • ₹10,000 ➔ ₹12,000
  • Return = 20%

Zero Return

You neither gain or loss.

  • ₹10,000 ➔ ₹10,000
  • Return = 0%

Negative return

You lose money.

  • ₹10,000 ➔ ₹9,000
  • Return = -10%

The basic relationship can be undrstood like this:

Higher potential return ➔ Usually higher potential risk

Lower potential return ➔ Usually lower risk

But this is not guarantee.

Example

Let say Investment A has a potential return of 6%, while Investment B could Potentially earn 12%.

This means an investor seeking the possinility of higher returns may have to acdcept greater uncertainty.

Does Higher Risk Always Men Higher Return?

NO.

This is one of the most importan things beginners should understand.

Taking more risk does not guarantee that you will make more money.

Consider two investments:

  • Investment A has moderate risk and eventually earns 10%.
  • Investment B has high risk but eventually loses 20%.

Investment B involved more risk, but it produced a negative return.

Higher risk = Higher potential return, nit guranteed higher return.

The word potential is important.

Why Do Investors Accept More Risk?

Investors may accept greater risk because they want the possibility od achieving higher returns.

Example:

Someone investing for a lonf term financial goal may consider investment with higher potential frowth than atraditional savings product.

But beofre taking additional risk, an investor should cosnsider.

  • Fiancial Goals
  • Investment time horizons
  • Ability to handle losses
  • Emergency savings
  • Existing investments
  • Income Stability
  • Investment Knowledge

Risk should not be taken simply because an investment promises a higher return.

Risk vs Return and Time Horizon

Your time horizon can also affect how you think about risk.

A time horizon is the length of time you expect to keep your money invested.

Short Term Goals

Let’s say you need ₹2 lakh for an expense next year.

A large loss shortly before you need the money could create a problems.

Long Term Goal

Let’s say are investing for a goal many years away.

You may have more time to deal with market fluctuations,athough losses are still possible.

This does not mean long term investments are automatically safe.

It means the amount of time available can effect how much short term volatility you may be able to tolerate.

Risk Tolerance vs Risk Capacity

Two Term are useful for beginners:

Risk Tolerence

This refers to how confortable you are with investment losses and price fluctuations.

Example:

If you seeing your investment fall 20% would make you panic and sell immediately, you may have lower tolerance for large fluctuations.

Risk Capacity

This refers to how much financial loss you can actually afford.

Example:

Someone with an emergency fund, stable income and a long investment horizon may have greater financial cpacity to withstand temporary losses than someone who needs the money soon.

These are different concept.

You ight be emotionally comfortable with high risk but financially unable to afford a large loss.

Risk vs Return Example in Real Life

Let’s say three Hypothetical investors.

Investor A – Low Risk Preference

Invest mostly in reltively lower risky-risk products.

Potential returns may be lower but large fluctuationsmay also be less likely

Investor B – Moderate Risk

Uses a mixture of idfferent investments.

The protfolio may have a balance between growth potential and risk.

Investor C – Higher Risk

Invests a Larger portion in assets with significant price fluctuations.

There may be greater potential form growth, but also greater potential losses.

None of these approches automatically produces a better results.

The appropriate level of risk depends on the person’s fiancial situation, goals, time Horizon and ability to handle losses.

Risk vs Return in Stocks

Stocks are a common example of the risk return relationship.

A stock’s price can rise signifantly.

But it can also fall signifcantly.

Example:

You invest ₹50,000

If the investment rises by 20%.

₹50,000 ➔ ₹60,000

Gain = ₹10,000

But if it falls by 20%:

₹50,000 ➔ ₹40,000

Loss = ₹10,000

The same investment can produce very different outcomes.

This is why potential return should al;ways be considered longside risk.

Risk vs Return in Mutual Funds

Mutual funds invest in a collection of securities according to their investment strategy.

Different types of mutual funds can have different levels of risks.

Example:

  • Some funds focus on equities.
  • Some focus on bonds
  • Some combine different types of assets.

A fund’s historical return does not gurantee its future returns.

Therefore beginners should look at more than just the return percentage.

The Role of diversification

One way investors can manage certain types of risk is through Diversification.

Diversification means spreding money across different investmebnt insted of putting everything into one investment.

Example:

Instead of investing your entire ₹1,00,000 in one stock, an investor may spread money across different assets.

Diversification cannot eliminate investment risk, but it can help reduce the impact of apoor performance from one particular investment.

Our nect article will explain diversification in detail.

Risk, Return, and Inflation

There is another factor beginners should remember:

Let say your investment earns 6% per years, but inflations is 5%.

Your money has grown in nominal terms, but its puchasing power not have not have increased by the same amount.

Therefore, when thinking about returns, investors should consider:

Return + Risk + Inflation + Costs + Time

Looking at the return percentage alone may not give you the comlete picture.

Risk vs Return vs ROI

These concept are related but differently

ConceptMeaning
RiskPossibility of loss or uncertainty
ReturnGain or loss from an investment
ROIA percentage measure comparing gain or loss with the original investment
Risk vs ReturnRelationship between potential returns and the level of risk involved

Example:

You invest ₹10,000 and recieve ₹12,000.

Your gain is ₹2,000.

Your ROI is:

₹2,000 ÷ ₹10,000 x 100 = 20%

But ROI Alone doesn’t tell you how much risk was invilved or how long it took to acieve that returns.

Common Beginner Mistakes

1. Chasing the Highest Return

A high expected return can come with significant risk.

2. Assuming High Risk Gurantees High Returns

It doesn’t

Higher risk means greater uncertainly, not guranteed profit.

3. Ignoring Time

A 20% return over one year is different from a 20% return over ten years

4. Looking Only at past Peformance

Past Performance does not gurantee future results.

5. Investing Without an Emergency Fund

Money Needed for emergencies generally shouldn’t depend on risky investment.

6. Putting Everything Into One Investment

Concentration can increase the impact of a single invesment performing poorly.

FAQs

Is Higher risk Always better?

No Higher risk simply means greater unceertainly and potential downside. Whether a particular level of risk is appropiate depdns on the investor’s circumstances and goals.

Can a low risk investment lose money?

Yes.”Lower risk” does not mean “zero risk.”

Does higher return mean a better investment?

Not necessarily. You Should also consider risk, time period, costs, taxes, inflation, anmd your financial goals.

What is the main idea of risk vs return?

The basic idea is that investment offering higher potential returns generally ivolve greater uncertainly and potential losses.

Can Diversification reduce risk?

Diversification can reduce certain concertration related risks, but it cannot eliminate all investment risk.

Should Beginners always choose low risk investments?

Not necessaril;y. The appropriate level of risk depends on factors such as financial goals, time horizons, financial capacity and riskl tolerences.

Link this article to:

What Is Risk in Investing? — Why Every Investment Has Some Risk

What Is Risk in Investing?

When people start lesarning about investing, they often focus on one question.

“How much money can I make?”

But there is another question that is just as important:

“How much could I lose?”

This is where investment risk comes into the picture.

Investment risk is the possibility that an investment may not perform as expected, You could receive a lower return that expected, lose part of your original money or in some cases lose most or all of the amount invested.

Different investment have different types and levels of risk.

Udnerstnding risk does not mean avoiding investing completely. It mean understanding what could happen to your money before you invest.

What Does Risk Mean in Investing?

In simple words:

Investment risk is the possibility that the actual results of an investment will be differently from what you expected.

Example

Let say you have ₹10,000 in an investment expecting it ot grow.

Instead ts value falls to ₹9,000.

You have have potential loss of:

₹10,000 – ₹9,000 = ₹1,000

Teh investment therefore carried the risk pf losing value.

Risk can also mean something other than losing money.

Example an investment may perserve your money but grow too slawly to keep up with inflation.

Why Does Every Investment Have Some Risk?

There is no investment that can guarantee the exact outcome of every future situation.

Different risks can come from:

  • Chanmges in market prices
  • Inflation
  • Interest rated
  • Economic codnitins
  • Company performance
  • Governament policies
  • Currency movements
  • Liquidity problems
  • Changes in demand
  • Unexpected events

The amount and type of rsik vary significantly between investments.

Example:

The risk associated with a bank deposits can be vary different from the risk associated with an individual stock.

A Simple Example of Investment Risk

Suppose you have ₹50,000.

You invest it in a stock.

After some time, the stock price increases and your investment becomes:

₹60,000

Your gain is:

₹10,000

But the stock price could also fall.

If your investment becomes:

₹40,000

your loss is:

₹10,000

This uncertainty is one form of investment risk.

The important point is that market-based investments can move both upward and downward.

Different Types of Investment Risk

Investment risk is not just one thing.

there are several different types of risk that investors should understand.

1. Market Risk

Market risk is a possibility that an investment will lose value because the overall market or market codnitions change.

Example

Stock prices fall because of

  • Econcomic concerns
  • Interest rate change
  • Investor sentiments
  • Company or industry news

A stock was worth ₹500 could later trade at ₹450 or ₹400.

Market prices can change frequently.

2. Business Risk

When you invest in a company, you are exposed to the possibility that the company mat perform poorly.

A business could face:

  • Falling Saless
  • Increasing costs
  • Strong Competition
  • Poor managment decisions
  • regulartory changes
  • Technologicial disruption

If the company’s performance deteriorates it share price may also decline.

This is known as business risk.

3. Inflation Risk

Inflation means that the rpices of goods and services generallyincreases over time.

prices rise the purchasing power of money can decrease.

Example

Let say you have ₹10,00 todays.

If prices rise significantly over several years, ₹10,000 in the future may not but same amount of goods and service.

Thgis creates inflation risk.

An investment can increase in value while still providing limited growth in real purchasing power if inflation is high.

4. Interest Rate Risk

Interest rates affect different investment in diferent ways.

Example

Changes in interest rates can influence the price of bands.

When the interest rates change,existing bonds with fixed interest payments can become more or less attractive compared with newly issued bonds.

Interest rates can also affect businesses because borrowing costs may increases or decreases.

Therefore, investors should understand how interest rate changes can affect the types of investment they own.

5. Credit or default Risk

Credit risk is particularly relevent when you lend money through an investment such as a bond.

The borrower may have difficulty making interest payments or repaying the principal.

Example:

You lend a company ₹50,000 through a bond.

The company is expected to pay interest and eventually return your ₹50,000.

If the company experiences serious financial problems, there may be e risk that payments are delayed or not fully made.

This is called credit or default risk.

6. Liquidity Risk

Liquidity refers to how easily can buy or sell an investment without signifcantly affecting its price.

An investment may be difficult to sell quickly.

Example

Let’s may have to wait to find buyer or accept a lower price to sell quickly.

That is liquidity risk.

7. Currency Risk

Currency risk can affect people who invest in assets denominated in another currency.

Let say an indian investor invests in an asset priced in UD Dollars.

Even if the investment’s dollar value stays unchanged, changes in the USD/INR Exchange rate can affect the investment’s value when converted back into rupees.

This is known as currrency risk.

Risk and Return

There is an important relationship between risk and potential return.

Generally investment with greater uncertaintymay offer the posibility of higher returns, while investments with lower risk may offer lower potential returns.

But this does not mean:

Higher Risk = Guranteed higher returns.

It doesn’t A risky investment can produce a high return or a loss.

InvestmentPotential RiskPossible Outcome
Savings/deposit productsGenerally lowerLower potential return
Government securitiesGenerally lower, depending on the securityRelatively predictable payments if held under applicable terms
BondsVariesInterest income and possible price changes
Mutual fundsVaries by fundReturns can rise or fall
StocksCan be highSignificant gains or losses are possible
Speculative assetsCan be very highLarge gains or losses are possible

Teh exact risk depends on the specfic product not simply its category.

Can You Avoid Investment Risk Completely?

You generally cannot eliminate all investment risk.

However, you can understand and manage risk.

Some common approaches includes:

Diversification

Spread investment across different assests rather than relying heavily on one investment.

Understanding What You Buy

Learn how an investment works before putting your money onto it.

Considering Your TIme Horizon

An investment may behave differently over a few months compared with several years.

Maintaining an Emergency Fund

Money needed fo unexpected expenses genrally should not depend on selling a volatile investment at an inconvenient time.

Avoiding Unnecessary Concentration

Putting too much money into one company, sctor or assest can increase concentration risk.

Reviewing Costs

Fees and other Costs can reduce investment returns.

Risk Tolerance vs Risk Capacity

Two People can have the same investment but very different abilities to handle ot risks.

Risk Tolerence

This is about how comfortable you are wuth investment fluctuations and potential losses.

Somone may be uncomfortable seeing their investment fall 20%.

Another person may be mire comfortable with signifant fluctuations.

Risk Capacity

This is about your financial ability to handle a loss.

Someone with stable income, adequate savings and along investment horizon nay have a different financial capacity for risk than somone who needs the oney soon.

Both concept are important when thinking about investments.

Wht Time Horizon Matters?

Yor Time Horizon is how long you expect to keep your money invested.

let’s say you need ₹2 lakh in three months.

Putting that money into a highly volatile investment could expose you to the possibility of needing to sell after a market deline.

Now consider money that you don’t expect to need for many years.

You my have more time to expernience and portentially recover from matket fluctuations, although recovery is never guaranteed.

Therefore, your investment time horizon is an important part of understanding risk.

What Happens When You Take TOO Much Risk

Taking more risk than you can finacially or emotonally handle can create problems.

Example:

You invest ₹5 lakh in a highly volatile investment.

The value falls to ₹3.5 lakh.

If you need the money immedtiatelly you may feel forced to sell during the decline.

This casn turn a temporacy declineinto permanent realized loss.

That’s why investment should genrally be matched with your financial goals, time horizonsand ability to handle losses.

Risk Does Not Mean an Investment IS Bad?

An Investment having risk does not automatically make it a bad insvestment.

Risk is simply a charcteristic that needs to be understood.

Example:

Stocks can experience significant price movements,but they are also commonly used by investors seeking long term growth.

Smilaarlylower risky investments may provide greater atavility but may have lower growth potential.

The important question is not simply:

“Does this investment have risk?“

Instead consider:

“What risks does this investment have, and can I handle Them?“

A Simple Risk Checklist for Beginners

Before investing, ask yourself:

1. What am I in vesting in?

do you understand the investment?

2. How can I make money?

Understand where the potential return comes from.

3. How can I Losemoney?

Identify the major risks.

4. How long can I keep my money Invested?

Think about your time horizon.

5. How easily can I access my money?

Cosnider liquidity.

6. What Happens if the investment falls?

Think about Whether you could financially handle a decline.

7. Are there fees or taxes?

These can effect your actual returns.

8. Is my moey diversified?

Avoid unncessary concentration in one Investment.

Common Mistakes Beginners Make

Mistake 1: Looking Only at Potential Returns

A high potential return can come with high uncertainly.

Always consider both potentialreturn and risk.

Mistake 2: Believing Past Performance is Guaranteed

An Investment that performed well in the past may not perform the same way in the future.

Mistake 3: Investing Money You Need Soon

Short Term Financial Needs and long term investments sholud be Considered Separately.

Mistake 4: Putting Everything Into One Investment

Concentration can increase the impact of an singl;e investment performing poorly.

Mistake 5: Following Others Without Undrstanding the Investment

Someone else’s investment choice may not match your fianncial situation, goal or risk tolerence.

A negative ROI means the investment lost value relative to the Original Investment.

Link this article to:

What Is a Return on Investment (ROI)? — Understanding Investment Returns

What Is a Return on Investment (ROI)?

When you invest your money one of the first question you may have is:

“How much did I actually make from this investment?”

This is where Return On Investment, commonly called ROI becomes useful.

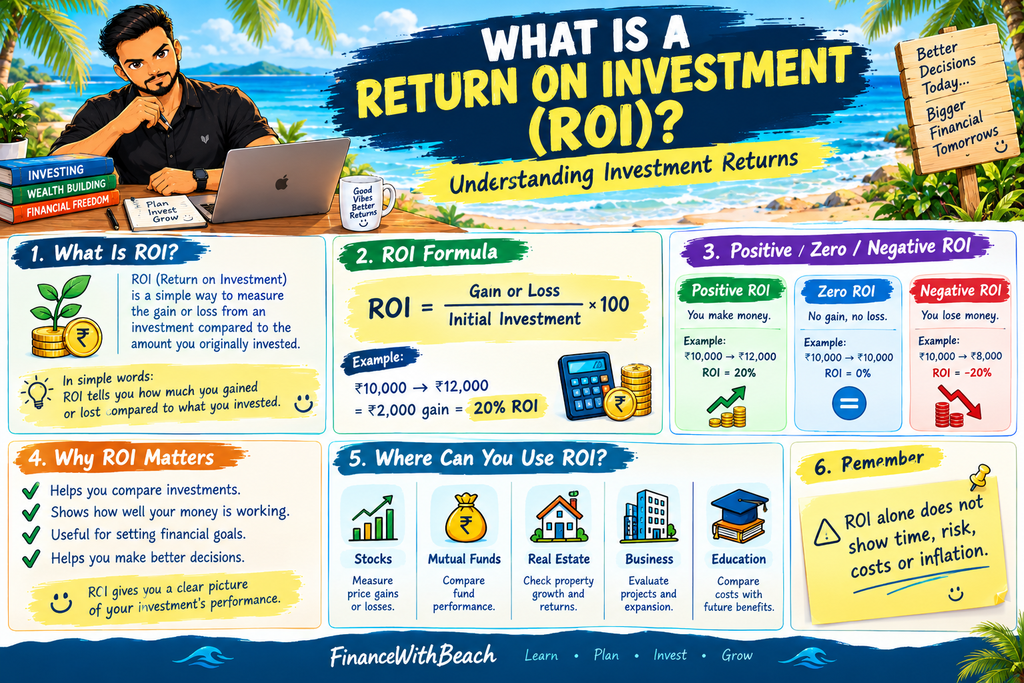
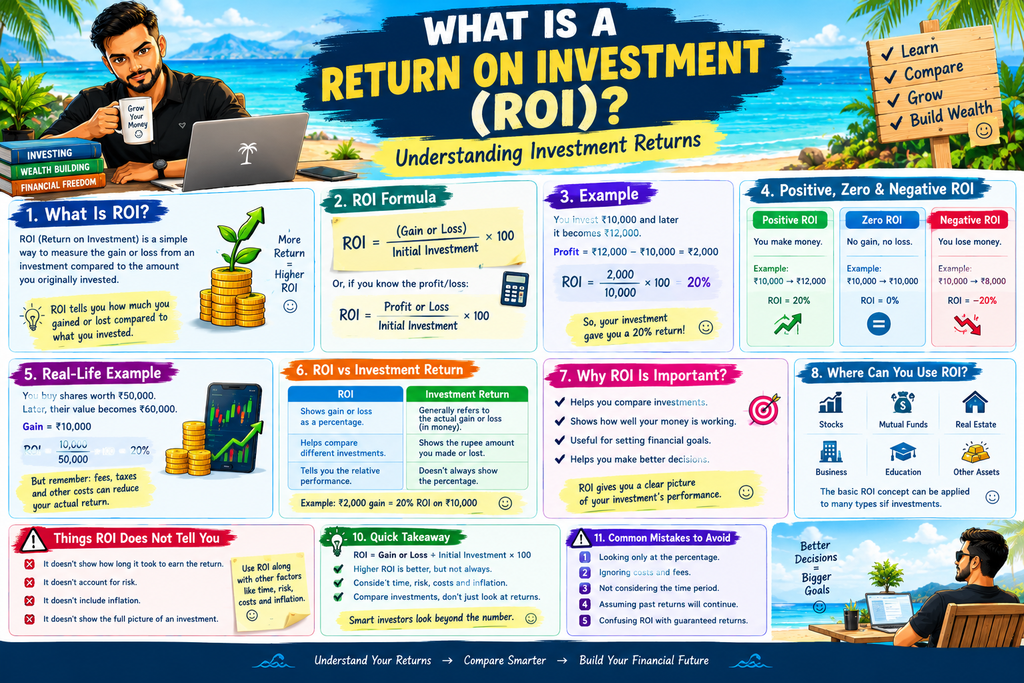
ROI is a simple way to measure the gain or loss from an investment compared with the amount of money you orginally invested.

In simple Words:

ROI tells you how much you gained or lost compared with that you invested.

Understanding ROI can help beginners compare diferent investments and understand whether an investment produced a profit or loss.

What Does ROI mean?

ROI stands for Return on Investment.

It measures the return generated by an investment relative to its original cost.

Example

Let say you invested ₹10,000 in something and later sell at ₹12,000.

Your profits on

₹12,000 – ₹10,000 = ₹2,000

Your ROI is:

₹2,000 ÷ ₹10,000 x 100 = 20%

So your investment produced a 20% ROI.

ROI Formula

The basic formula is:

ROI = (Investment Gain – Investment Cost) ÷ Investmetn Cost x 100

or if you already know the profit or loss

ROI = Profit or loss ÷ Initial Investment x 100

Example

You Invest ₹20,000.

After some time, your investment becomes ₹24,000.

Your gain is:

₹24,000 – ₹20,000 = ₹4,000.

Therefore:

ROI = ₹4,000 ÷ ₹20,000 x 100

ROI = 20%

Your ROI is 20%.

Understanding Positive and Negative ROI

ROI can be positive,zero or Negative.

Positive ROI

If you make money, your ROI is positive.

Example:

Investment = ₹10,000

Final value = ₹12,000

ROI = +20%

Zero ROI

If you neither gain nor lose money, your ROI is Zero.

Example:

Investment = ₹10,000

Final value = ₹10,000

ROI = 0%

Negative ROI

If you lose money, your ROI is negative.

Example:

Investment = ₹10,000

Final value = ₹8,000

Loss:

₹8,000 – ₹10,000 x 100 = -20%

ROI = -20%

ROI vs Investment Return

These terms are related but should not always be treated as exactly the same thing.

Investment rteurn generally refers to th gain or loss genrated by an investment.

ROI expresses that gain or loss relative to the amount invested usually as percentage.

Example:

  • Investment: ₹10,000
  • Gain: ₹2,000
  • ROI: 20%

The ₹2,000 is th gain.

The 20% is th ROI.

Why is ROI Important.

ROI provides a simple way to understand invetment performance.

Let say have two investments:

Investment A

  • Investment: ₹10,000
  • Gain: ₹1,000
  • ROI: 10%

Investment B

  • Investment: ₹10,000
  • Gain: ₹2,000
  • ROI: 20%

Looking only at the rupee profit shows that Investment B Genrated More Profits.

ROI also Puts the returns into percentage terms, making it easier to compare investments with diferent amounts.

Can ROI Be Used for Different Investments?

YES.

The baisc ROI concept can be applied to many Situations.

Example:

Stocks

You can claculate the gain or loss compared with the amount invested.

Mutual Funds

You can Campare your investment amount with its current or final value.

Real Estate

You can compare the gain from selling a property with the amount invested, athough a complete property analysis may need to include expenses such as maintenance, taxes, financing cost5s and transaction costs.

Business

A business owner can compare the profit generated by a project with amount spend on it.

Education

People sometimes use ROI as framework for thinking about education by comparing its costs with potential financial benefits, although many non-financial factors also matter.

ROI Does Not Tell the WHole Story

ROI is useful, but it hase an important Limitation:

It doen’t automatically tell you how long it took to earn the return.

Investment A

You invest ₹10,000 and make a 20% return in 1 year.

Investment B

You invest ₹10,000 and make a 20% return in 5 year.

Both have ROI 20% total ROI.

But the time period is very different.

This is why you should consider time when comparing investment returns.

ROI vs Annualized Return

If two investment have different time periods, a simple ROI comparison may not be enough.

Example:

Investment A: 20% ROI in 1 Year

Investment B: 20% ROI in 5 Year

The total ROI is the same, but the investment periods are not.

Measures such as annualized return can help provide a time adjusted view investment performance.

For investment that compared, the annualized return of often more informative than simply dividing total ROI by the number of years.

ROI and Compound Growth

ROI and Compound growth are coonnected, but they are not the same concept.

ROI tells you the overall percentage gain or loss relative to the original investment.

Compounding describes how reurns hat remain invested can contribute to futre growth.

Example: Let say ₹10,000 grows at a hypothetical 10% annual rate:

  • Year 1 – ₹11,000
  • Year 2 – ₹12,100
  • Year 3 – ₹13,310

The total gain after three years is ₹3,310 giving a total ROI of 33.1%

This example assumes the same return every year and is purely for illustration.

ROI Example With a Loss

ROI isn’t only about profits.

Let say you invest ₹25,000 i n an investment.

Later, its value falls to ₹22,500.

Your loss is:

₹22,500 − ₹25,000 = −₹2,500

ROI:

−₹2,500 ÷ ₹25,000 × 100 = −10%

Your ROI is therefore −10%.

This is why investments should not be judged only by the possibility of making money. Investment values can also decline.

What Can Affect Your Actual ROI?

The simple ROI formula does not automatically account for every cost.

Dpedning on the investment you may need ot consider:

  • Brokerage fees
  • Transaction charges
  • Taxes
  • Managment fess
  • Maintenance costs
  • Pruchase and selling costs
  • Loan interest
  • Other investment related expenses

Simple Example

Suppose:

Investment = ₹10,000

Final value = ₹12,000

Before costs, your profit is ₹2,000.

But suppose you paid ₹200 in relevant costs.

Your net gain becomes:

₹2,000 − ₹200 = ₹1,800

Your net ROI would then be:

₹1,800 ÷ ₹10,000 × 100 = 18%

So the return after costs can be lower than the headline ROI.

ROI IS NOt teh Same as Risk

A high ROI does not automatically mean an investment is suitable for everyone.

Two investment could produce different returns while also having very different levels of risks.

Example:

  • Investment A may have a lower potential return and lower risk.
  • Investment B may have a higher potential return but greater uncertainly.

ROI measueres the return, not the complete risk profile of an investment.

This is why investors should cosnider both risk and returns.

Common Mistakes Beginnerss Make With ROI

1. Looking onaly at percentage

A 50% ROI sound large, but you should also understand the amount invested and the time time involved.

2. Ignoring Costs

Fees, Taxes and other expenses can reduce your actual return.

3. Ignoring the time period

A 20% return over one year is different from a 20% return over five years.

4. Assuming past ROI will continue

A pervious return does mot guarantee that the sam return will happen in the future.

5. Confusing ROI with Guaranteed returns

ROI can be positive or Negative. Investment involving market risk do not guarantee a particular ROI.

ROI and Inflation

Another Important consideration is Inflation.

Let’s your investment grows by 6% over a period while prices increase significantly during the same period.

Your money may have have increased in nominal valu but its purchasing power may not have increased by the same amount.

Therefore, when evaluating long term investment, it can be useful to think about both:

Investment return + Inflation

rather than looking only ROI alone.

FAQs

What does ROI stand For?

ROI stands for Return on Investment.

What is a good ROI?

There is no sim=ngle ROI percentage that is automatically “good” for ecery investment. it’s all dpends on time horizon, fees , taxes, costs and market conditions.

How do you calculate ROI?

ROI = Profit or loss ÷ Initial Investment x 100

Is ROI the same as profit?

No.

Profit is usally expressed as money amount while ROI expresses the gain or loss relative to the investment as a perecentage.

Can ROI be Negative?

Yes.

A negative ROI means the investment lost value relative to the Original Investment.

Link this article to:

Simple Interest vs Compound Interest — What’s the Difference?

Simple Interest vs Compound Interest — What’s the Difference?

When you saver, or invest money you will often come across the word interest.

Interest is the extra money earned on savings or investments or the extra money paid when norrowing money.

There two ways to caluclated the interest:

  • Simple Interest
  • Compound Interest

Athough boyh include interest, they work diffrently. understadning the difference is important because is can affect how quickly your money grows or how much you eventually pay on a loan.

In this article, we will explain simple and compund interest using easy example.

What is Simple Interest?

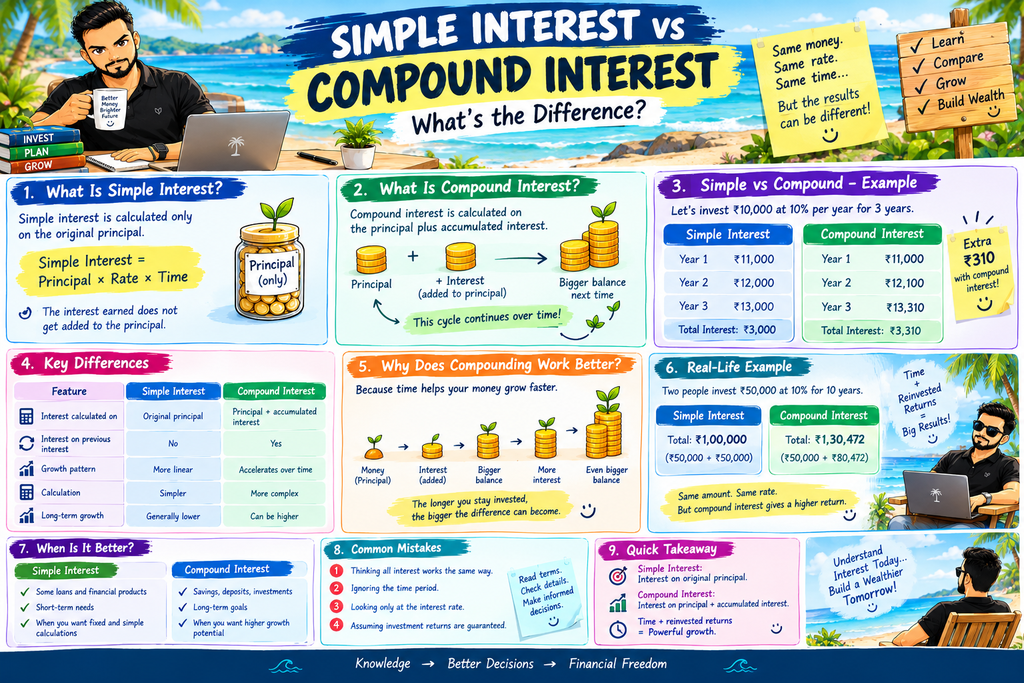
Simple Interest is calculated only on the original amount of money, called Principal.

The interest earned does not get added to the principal when calculating interest for the next period.

Simple Interest Formula

Simple Interest = Principal x Rate x Time

Example:

Let’s say you invests ₹10,000 at 10% simple interest per year for 3 years.

  • Principal = ₹10,000
  • Interest Rate = 10%
  • Time = 3 years

Interest Earned:

₹10,000 z 10% x 3 = ₹3,000

So after 3 years:

Total = ₹10,000 + ₹3,000 = ₹13,000

The interest is calculated on the original ₹10,000 eavet year.

What Is Compound Interest?

Compound Interest is different because the inetrest you earn can be added to your original money.

Then, Future interest can be calculated on both:

Original Money + Previously earned money

This is often described as “interest on interest.”

FV=PV(1+r)nFV=PV(1+r)^n

Example:

Let’s say you invests ₹10,000 at 10% simple interest per year for 3 years.

Year 1

₹10,000 earns ₹1,000 interest

Balance = ₹11,000

Year 2

Now the 10% interest is claculated on ₹11,000.

Interest = ₹1,100

Balance = ₹12,100

Year 3

Interest is calculated on ₹12,100.

Interest = ₹1,210

Balance = ₹13,310

So after 3 years:

Total = ₹13,310

This is higher than the ₹13,000 produced by simple interest.

Simple Interest Vs Compound Interest:

Example

Let’s compare noth using the same starting amount.

Suppose:

  • Intial amount = ₹10,000
  • Interest rate = 10% per year
  • Period = 3 years
YearSimple Interest BalanceCompound Interest Balance
Start₹10,000₹10,000
Year 1₹11,000₹11,000
Year 2₹12,000₹12,100
Year 3₹13,000₹13,310

Difference

After 3 years:

Simple Interest = ₹13,000

Compound Interest = ₹13,310

The difference is ₹310.

The difference may look small over small year, but it can become much larger when money compounds for many years.

Key Difference Between Simple and Compound Interest

The easiest way to remember the difference is:

Simple Interest works on the original Principal. Compound interest works can be calculated on the principal plus accumlated interest.

Simple Interest

You earn interest on the original amount.

Compound Interest

You can earn interst on the original amount and perviously earned interest.

Simple Interest vs Compound Interest

FeatureSimple InterestCompound Interest
Interest calculated onOriginal principalPrincipal + accumulated interest
Interest on previous interestNoYes
GrowthMore linearCan accelerate over time
CalculationSimplerMore complex
Long-term growthGenerally lowerCan be higher at the same rate
Common useCertain loans and financial calculationsSavings, deposits, investments and some loans

The exact way interest is applied depends on the financial product ans its terms.

Why Does Coompound Interest Become Powerful Over Time?

The biggest difference between the two becomes visible over a longer period.

With simple interest, the interest amount remains based on the principal original princicpal.

With compound interest, the base used to calculate future interest can keep investing.

Example:

Your investment earn interest and you leave that interest invested instaed of taking it out.

Your money can follow a cycle lile this:

Money ➔ Interest ➔ Larger Balance ➔ More Interest ➔ Even Larger balance

This is why is an important part of compounding.

The longer money remains invetsed and compounds, the greater the potential difference can become.

Is Compound Interest Always Better?

Nit necessarily.

It depends on whether you earning interest or paying it.

When you are earning interest

Compound interest can help your money grow because previously earned interest can generate additional interest.

When you are brorrowing money

Compound interest can increase amount you owe when unpaid interest is added to the balance and subsequently acruese more interest.

That’s why very important to understanding the temr sof loans, credit products, deposits and investment before making financial decisions.

Simple Interest vs Compound Interest In Everyday Finance

You may encounter these concept in different areas of personal finance.

Savings

Some savings products may pay interest according to specfic compounding rules.

Fixed Deposits

Interest may be calculated and compounded according to the terms of the deposits.

Loans

Some loans use interest clalculations that can involve compounding while others use different methods.

Investments

Compounding is an important mathematical concept behind long term investment growth when returns remains invested.

Always check the specfic product’s terms rather than asuming that every financial product uses the same interest method.

Why Started Early Matters?

One of the important lessons from compound interest is the value of time.

Supppose two investors eventually invest the sme amount of money, but one starts several years earlier.

The earlier investor has more time for returns to portentially generate additional returns.

Example:

₹10,000 ➔ Returns ➔ Larger Returns ➔ more returns ➔ Larger balance

Over a long period, this repested process can have a signifcant effect.

This is ine reason compound interest is often discussed when learning about long-term investing and wealth building.

Simple Interest vs Compound Interest:Which Formula Should You Know?

For Simple Interest:

Simple Interest = P x R x T

Where

  • P = Principal
  • R = Interest rate
  • T = Time

For Compound Growth, a commonly used annual-compounding formula is:

A = P(1 + r)ⁿ

where:

  • A = Final amount
  • P = Principal
  • r = Annual interest rate expressed as decimal
  • n = Number of years

the actual calulation can differ when interest compund monthy, quarterly or at another frequency.

Common Mistakes Beginners Make

1. Thinking all interest works the same way

Different financial products can use different interest calculations.

2. Ignoring the time period

A rate tht looks attractive overa shor period may have a very different effect over period a long period.

3. Looking only at the interest rate

Fees, taxation,inflation, compunding freuqency and prdsouct terms can also affect the actual outcome.

4. Assuming investment returns are guaranteed

Compound growth examples often use a fixed rate for simplicity. Real market investments can rise and fall and actual returns may differ.

FAQs

Is Compound intereet better than simple interest?

When you are earning interest, compound interest can produce more growth than simple interest at the same rate and over the same period because perviously earned interest can also genenrate interest.

What is the main difference between simple and compound interest?

Simple Interest works on the original Principal. Compound interest works can be calculated on the principal plus accumlated interest.

Does Compound Interest Help investment Grow?

Compounding can cintrubute to long term growth when returns remains invested, However, market investment do not guarantee a fixed returns.

Can compound Interest increase Debt?

Yes. Depending on the product’s terms, unpaid interest can become part of the balance on which future returns is calulated.

Why is compound interest important?

it helps explain why money can gorw increasingly faster over long periods when reurns remain invested.

Link this article to: